
2025年6月24日3 分钟阅读
想象一下,你的钱包里躺着 5,000 美元的加密货币,一直原地不动,既不增值,也不产生任何收益。于是你开始关注借贷平台——希望像存款账户一样赚取利息。但随即你意识到一个问题:这样做究竟有多安全?无论你是打算投身 DeFi,还是继续留在令人安心的中心化金融(CeFi)世界,托管权的问题都会很快浮出水面。你是应该把私钥交给像 BlockFi 这样的应用,还是自己掌控一切、选择非托管方式?这就像是在时髦的新型银行里选择一份高息储蓄账户,与把金条藏在床垫底下之间做选择。两者各有优势,也各有风险。DeFi(去中心化金融)让你掌握主导权,但同时也要求你具备一定的技术素养。CeFi(中心化金融)承诺简单便捷,但要求你给予盲目的信任。这不仅仅是技术层面的讨论——这关乎你的生计。数十亿美元的用户资金,已经因黑客攻击、破产以及糟糕的决策而付诸东流。理解托管型与非托管型借贷平台之间的区别,或许正是决定你能否获得稳定收入、还是眼睁睁看着资金蒸发的关键所在。让我们来仔细拆解一下。
Why This Safety Comparison Matters
因为数字资产借贷并非没有风险。总部位于新泽西州的 BlockFi 曾因对 FTX 的敞口而暂停提款并申请破产,据路透社报道。2022 年,Celsius 在市场压力下崩溃,给客户留下 10 亿美元的资金缺口,后来修正为 70 亿美元。 与此同时,Cream Finance 等去中心化借贷协议应用在第三次攻击中被黑客盗取超过 1.3 亿美元。
Safety isn’t just about code or reputation. It’s about control, transparency, and trust. And depending on how much risk you can stomach, one platform may suit you better than the other. So let’s dissect each side.
What Are Custodial Lending Platforms?
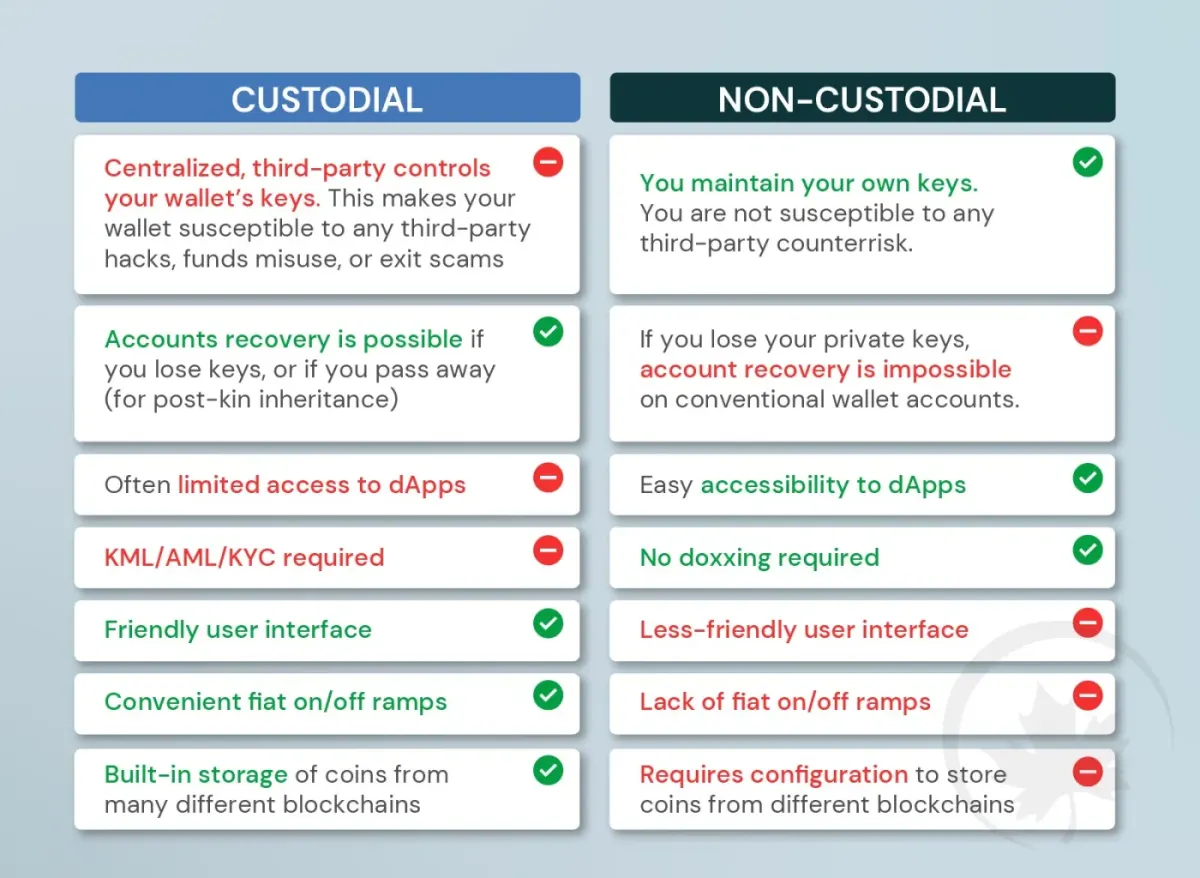
托管式平台就是数字资产领域的中心化托管银行。当你存入资产时,你就把控制权交了出去——它们持有你的资金、管理贷款并承诺回报。这类机构通常像传统机构那样运作,从风险评估到利息支付一手包办。
例如 Nexo、Celsius(在它还存在的时候)和 BlockFi。你把数字资产交给它们,它们把资产借出去,你收取利息。很简单,对吧?直到出问题的那一天。
Custodial lenders often operate behind closed doors. That means you don’t see where your money’s going or how they manage risk – until something breaks. When FTX collapsed, even platforms not directly tied to it suffered. Because trust is fragile when control is elsewhere.
Here’s a quick breakdown of the pros and cons of custodial learning:
| Pros | Cons |
|---|---|
| Easy to use – no wallets or 去中心化借贷协议 jargon | You don’t control your keys or assets |
| Often offer customer support | Risk of platform insolvency or mismanagement |
| Sometimes insured or regulated | Funds may be lent to risky borrowers |
| Fixed interest rates | Withdrawals can be paused in crises |
| KYC/AML processes help with compliance | Little transparency into internal operations |
What Are Non-Custodial Lending Platforms?
这就是狂野却透明的去中心化借贷协议世界。非托管应用让你在保有控制权的同时出借数字资产。你连接自己的钱包(例如 MetaMask),选择借贷池,直接赚取利息。你的数字资产留在你自己的钱包或智能合约中——而不是别人的保险库里。
There’s no support team holding your hand. But you get full autonomy, real-time data, and (usually) better rates. It's like doing your own taxes with spreadsheets – painful, but transparent. But heads up – non-custodial doesn’t mean risk-free. Smart contracts can be exploited. And if you lose access to your wallet? That's tough luck.
Here's a look at the pros and cons of noncustodial lending:
| Pros | Cons |
|---|---|
| Complete control of assets | Non-existent tech care – you're on your own |
| Transparent, open-source protocols | Possible contract bugs |
| Usually greater returns | Requires more technical know-how |
| No KYC – privacy-focused | Regulatory uncertainty can affect usage |
| Liquidity pools visible in real time | UX may spook beginners |
Security Risks Compared
数字资产借贷并非没有风险,无论应用界面多亮眼、模式多有前景。托管式和非托管式平台都曾遭受严重的安全问题冲击。
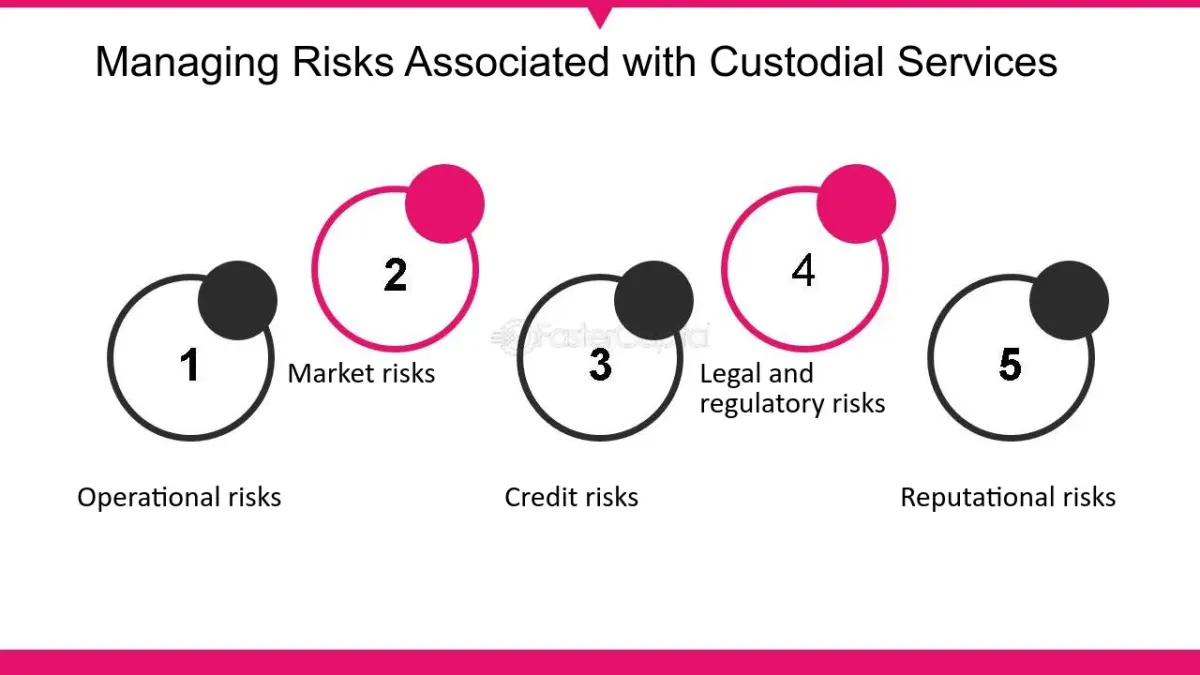
Custodial environments face risks like:
- Platform mismanagement
- Regulatory slamming
- Internal fraud or leaks
- Bankruptcy events (BlockFi, FTX-related collapses)
Non-custodial environments deal with:
- Smart contract exploits
- Oracle manipulation (price feed attacks)
- Flash loan attacks
- Code vulnerabilities left unpatched
Number of Major Lending Platform Exploits (2020–2024)
| Year | Custodial Incidents | Non-Custodial Incidents |
|---|---|---|
| 2020 | 3 | 5 |
| 2021 | 6 | 9 |
| 2022 | 11 | 14 |
| 2023 | 7 | 6 |
| 2024 | 5 | 4 |
Here’s the twist: custodial apps tend to fail big – one collapse and users lose everything. Non-custodial exploits often affect one protocol or contract, not the whole ecosystem. The damage is visible and traceable.
User Responsibility and Risk Tolerance
So who should hold the keys – you or the site?
If you use a custodial service, you are outsourcing accountability. This is okay if you’re just getting your feet weet or don’t wish to manage your own repository. Bear in mind though that should they mess up, you eat it.
In dealing with non-custodial services, you’re the bank. You approve smart contracts, manage private keys, and decide which pools to lend into. Passwords can’t be refetched. No customer support hotline.
It’s a trade-off between control and less hassle.
Basically:
- Custodial: Like a ride-hailing program. The driver and app control everything.
- Non-custodial: Like riding your own motorbike. More freedom, more skill required.
Custody Risk Scale (User vs Platform Control)
| Type | User Asset Control | Transparency | Technical Skill Required | Potential Yield |
|---|---|---|---|---|
| Custodial | Low | Low | Low | Medium |
| Hybrid | Medium | Medium | Medium | Medium |
| Non-Custodial (e.g., Aave) | High | High | High | High |
Tip: If you’re not ready to manage your private keys, don’t go buck-wild into 去中心化借贷协议 with your life savings. Start small. Test the tides.
Regulatory and Insurance Implications
我们来谈谈房间里的大象:监管。如果你把数千美元的数字资产托付给某个平台,就该问一句:万一出事,谁来救你?
事实是——大多数托管式借贷平台并未获得 FDIC 承保。即便它们声称自己“受监管”,也不意味着你的资金有保障。在传统银行体系中,如果你当地的银行倒闭,美国联邦存款保险公司(FDIC)会介入并最高赔付 25 万美元。而在数字资产领域——这基本不可能。
Take BlockFi, for instance. Before its collapse, many users thought their funds were “safe” because the company claimed to follow U.S. regulations. But when it went bankrupt, users became creditors in a long legal queue – not insured depositors.
Now compare that to non-custodial platforms like Aave or 8lends. They don’t claim to be regulated. They’re protocols, not companies. And because they never take custody of your funds, there’s no false sense of protection. You’re in full control – and full responsibility. One of the innovative measures that 8lends offers is it backs its loans with borrower collateral in addition to the ability to spread out investor risk inherent in crowdlending. That’s another important consideration when it comes to risk.
Let’s break it down with a comparison:
Compliance Comparison: Custodial vs Non-Custodial Platforms
| Platform | Custodial? | Registered Entity | FDIC Insurance | Regulatory Oversight | KYC Required |
|---|---|---|---|---|---|
| BlockFi (RIP) | Yes | Yes (USA) | No | SEC lawsuits pre-collapse | Yes |
| Nexo | Yes | Yes (EU) | No | Regulatory pressure in EU | Yes |
| Celsius (RIP) | Yes | Yes (USA) | No | Ongoing bankruptcy process | Yes |
| Aave | No | No | No | Community-governed | No |
| Compound | No | No | No | Open-source protocol | No |
So what should you look for?
If you choose custodial, look for:
- Registration with a financial regulator (SEC, FCA, ASIC)
- Clear terms of service regarding fund handling
- External insurance (some platforms have limited private insurance)
If you go non-custodial:
- Verify the resource is open-source and community-audited
- Use wallets you control
- Learn how to interact safely with smart contracts
Bottom line: There’s no FDIC safety net in digital assets. The safest approach is understanding the trade-offs – and avoiding platforms that overpromise.
Transparency & Audits
With custodial lending platforms, transparency is often optional and mostly PR-driven. You get dashboards, newsletters, maybe a blog post or two about “strategic partnerships.” But behind the scenes, you rarely know how loans are collateralized, who’s borrowing, or how liquid the platform really is.
That was a huge issue with Celsius and Voyager. Both operated in the dark. Both froze withdrawals with zero warning. Users only found out after their funds were already gone.
Non-custodial platforms, on the other hand, wear their code on their sleeves. Their smart contracts are open-source. You can check how funds move, when, and why. Want to see how much is locked in a liquidity pool, you don't need a login or permission.
But transparency isn’t enough. Smart contracts must be audited. Just like you wouldn’t live in a house that hasn’t passed inspection, you shouldn’t trust your digital assets to a protocol with unaudited code.
Pro Tip: If a non-custodial app hasn’t been audited within the last year, proceed with caution. Blockchain code moves fast. Bugs discovered in 2021 could still be lurking in 2025.
And always check who did the audit. Trustworthy names include:
- Trail of Bits
- CertiK
- OpenZeppelin
- Quantstamp
One more thing: a site might claim it’s audited, but never publish the results. That’s a red flag. If you can't verify the audit yourself, it doesn’t count.
Final Thoughts: Which Is Safer?
There’s no general answer for everyone. If you want simplicity, support, and a familiar interface, custodial platforms might suit you – as long as you’re okay with counterparty risk. If you want transparency, control, and a future-proof digital-asset experience, non-custodial platforms offer powerful tools but come with a steeper learning curve.
So ask yourself:
- Are you comfortable managing your own keys?
- Do you understand the risks of smart contracts?
- How much research are you willing to do?
The safest choice isn’t necessarily the most convenient. But it is the one that matches your risk tolerance, technical ability, and investment goals. Because in digital assets, safety isn’t just about technology but about making informed choices.
It’s hard to go wrong though with shared crowdlending, when you’re sharing the risk with a bunch of other lenders, in addition to collateral backing. If profiting in a low-risk milieu appeals to you, don’t hesitate to sign up on 8lends today.
接着读
有任何疑问吗?
全部问题平台已通过 CertiK 和 Cyberscope 审计,所有交易在 Base 区块链上公开可查。平台背后是两家职责清晰的公司:CLEARCHAIN CORP 负责平台运营,并在加拿大以 Money Services Business 身份在 FINTRAC 注册;Maclear AG 负责尽调与抵押物监管。平台受到良好监管,公开透明且责任清晰
若项目带有 BuyBack,逾期满 60 天后合作方将买断贷款并返还 100% 本金。若无 BuyBack,Maclear AG 将启动抵押物出售,所得按比例分配给投资者。平台上线以来从未发生违约
平台由 CLEARCHAIN CORP 运营,其在加拿大注册为 Money Services Business(MSB),并须在 FINTRAC 下履行强制性 AML/CFT 合规要求。结算以 USD 进行。平台并非 CASP,因此 DAC8 要求不适用
发展中地区的中小企业难以获得银行融资,愿意支付比欧盟或美国企业更高的利率
到期前可在二级市场将头寸卖给其他投资者。Fastlending 没有固定期限:本金和收益随时可提取
最低投资额为 100 USD
企业不还款的风险、抵押物价值波动的风险、二级市场无买家时的流动性受限风险,以及智能合约相关的技术风险
100 至 500 USD 的投资无需 KYC。超过 500 USD 需完成完整认证:身份证件和地址证明