
Custodial vs Non-Custodial Lending Platforms: Which Is Safer?
June 24, 20253 min read
Imagine you’ve got $5,000 in digital assets just sitting in your wallet. It’s not growing. It’s not earning any yield. So you start looking at lending platforms – so you can earn interest, like a savings account. But then it hits you: how safe is this really?Whether you’re diving into non-custodial lending protocols or sticking with the comfort of a centralized custodial platform, the question of custody comes up fast. Should you hand over your keys to an app like BlockFi? Or stay in control and go non-custodial? It's like choosing between a high-interest savings account at a flashy neobank versus stashing gold bars under your mattress. Both have pros. Both have risks.Non-custodial lending protocols put you in charge but demand tech smarts. Centralized custodial platforms promise simplicity but ask for blind trust. This is not just tech talk – this is your livelihood. Billions in user funds have been lost to hacks, bankruptcies, and poor decisions. Comprehending custodial vs non-custodial lending platforms may be what determines earning regular income versus it evaporating. Let’s break it down.
Why This Safety Comparison Matters
Because blockchain-powered lending isn’t risk-free. New Jersey-based BlockFi once paused withdrawals and declared bankruptcy due to exposure to FTX, according to Reuters. In 2022, Celsius collapsed under market pressure, leaving customers with a shortfall of $1 billion, later revised to $7 billion Meanwhile, lending protocols like Cream Finance were hacked for over $130 million, in a third attack.
Safety isn’t just about code or reputation. It’s about control, transparency, and trust. And depending on how much risk you can stomach, one platform may suit you better than the other. So let’s dissect each side.
What Are Custodial Lending Platforms?
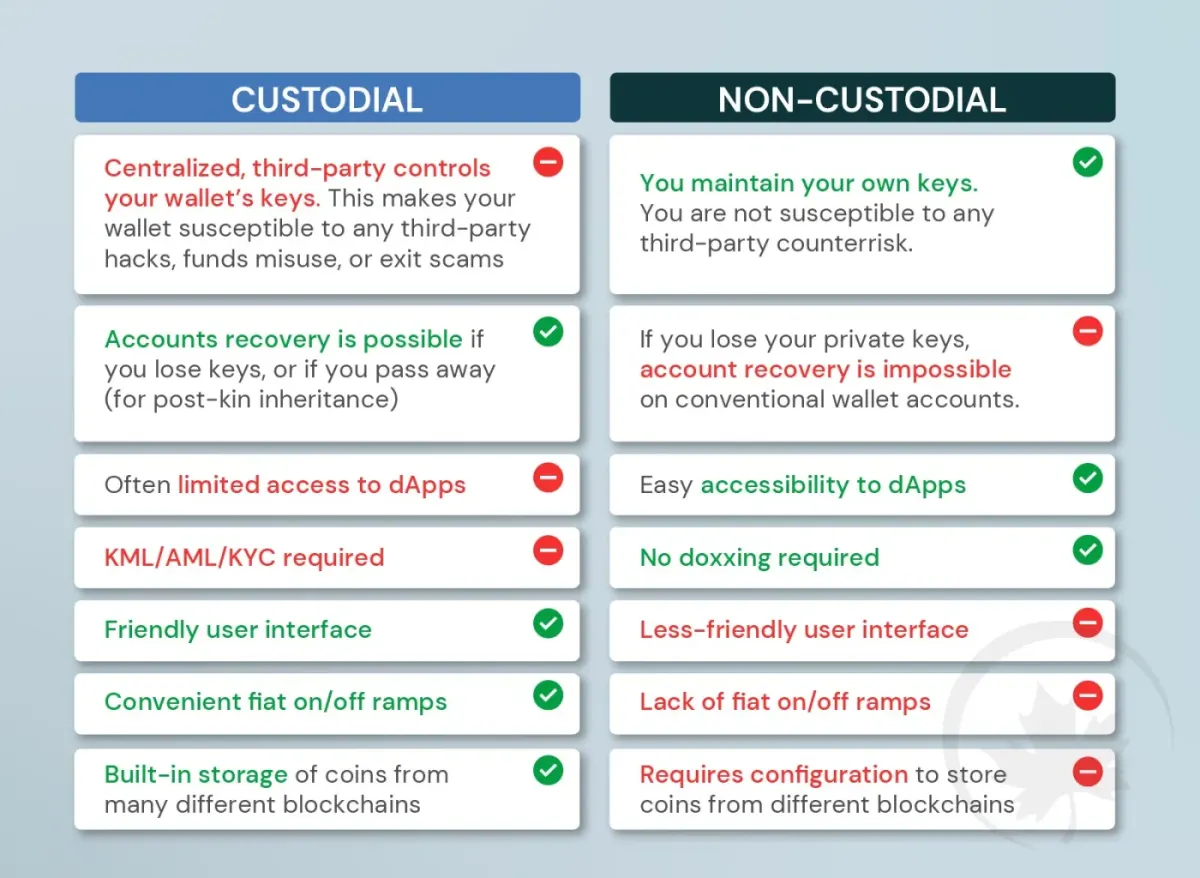
Custodial platforms are the banks of digital assets. When you deposit your assets, you’re handing over control – they hold your funds, manage the loans, and promise returns. These resources typically act like traditional institutions, handling everything from risk assessment to interest payouts.
Examples include Nexo, Celsius (back when it was alive), and BlockFi. You send them your digital assets, they lend them out, and you collect interest. Easy, right? Until it isn’t.
Custodial lenders often operate behind closed doors. That means you don’t see where your money’s going or how they manage risk – until something breaks. When FTX collapsed, even platforms not directly tied to it suffered. Because trust is fragile when control is elsewhere.
Here’s a quick breakdown of the pros and cons of custodial learning:
| Pros | Cons |
|---|---|
| Easy to use – no wallets or protocol jargon | You don’t control your keys or assets |
| Often offer customer support | Risk of platform insolvency or mismanagement |
| Sometimes insured or regulated | Funds may be lent to risky borrowers |
| Fixed interest rates | Withdrawals can be paused in crises |
| KYC/AML processes help with compliance | Little transparency into internal operations |
What Are Non-Custodial Lending Platforms?
Here's the wild but transparent world of non-custodial lending. Non-custodial apps let you lend your digital assets while holding onto control. You connect your wallet (like MetaMask), choose lending pools, and earn interest directly. Your digital assets stay in your wallet or smart contract – not in someone else's vault.
There’s no support team holding your hand. But you get full autonomy, real-time data, and (usually) better rates. It's like doing your own taxes with spreadsheets – painful, but transparent. But heads up – non-custodial doesn’t mean risk-free. Smart contracts can be exploited. And if you lose access to your wallet? That's tough luck.
Here's a look at the pros and cons of noncustodial lending:
| Pros | Cons |
|---|---|
| Complete control of assets | Non-existent tech care – you're on your own |
| Transparent, open-source protocols | Possible contract bugs |
| Usually greater returns | Requires more technical know-how |
| No KYC – privacy-focused | Regulatory uncertainty can affect usage |
| Liquidity pools visible in real time | UX may spook beginners |
Security Risks Compared
Digital-asset lending isn’t risk-free, no matter how shiny the app looks and promising the model is. Both custodial and non-custodial platforms have been hit hard by security issues.
Custodial environments face risks like:
- Platform mismanagement
- Regulatory slamming
- Internal fraud or leaks
- Bankruptcy events (BlockFi, FTX-related collapses)
Non-custodial environments deal with:
- Smart contract exploits
- Oracle manipulation (price feed attacks)
- Flash loan attacks
- Code vulnerabilities left unpatched
Number of Major Lending Platform Exploits (2020–2024)
| Year | Custodial Incidents | Non-Custodial Incidents |
|---|---|---|
| 2020 | 3 | 5 |
| 2021 | 6 | 9 |
| 2022 | 11 | 14 |
| 2023 | 7 | 6 |
| 2024 | 5 | 4 |
Here’s the twist: custodial apps tend to fail big – one collapse and users lose everything. Non-custodial exploits often affect one protocol or contract, not the whole ecosystem. The damage is visible and traceable.
User Responsibility and Risk Tolerance
So who should hold the keys – you or the site?
If you use a custodial service, you are outsourcing accountability. This is okay if you’re just getting your feet weet or don’t wish to manage your own repository. Bear in mind though that should they mess up, you eat it.
In dealing with non-custodial services, you’re the bank. You approve smart contracts, manage private keys, and decide which pools to lend into. Passwords can’t be refetched. No customer support hotline.
It’s a trade-off between control and less hassle.
Basically:
- Custodial: Like a ride-hailing program. The driver and app control everything.
- Non-custodial: Like riding your own motorbike. More freedom, more skill required.
Custody Risk Scale (User vs Platform Control)
| Type | User Asset Control | Transparency | Technical Skill Required | Potential Yield |
|---|---|---|---|---|
| Custodial | Low | Low | Low | Medium |
| Hybrid | Medium | Medium | Medium | Medium |
| Non-Custodial (e.g., Aave) | High | High | High | High |
Tip: If you’re not ready to manage your private keys, don’t go buck-wild into non-custodial lending with your life savings. Start small. Test the tides.
Regulatory and Insurance Implications
Let’s discuss the elephant in the room: regulation. If you trust a site with thousands in digital assets, it’s fair to ask: who’ll save you if matters head south?
Here’s the truth – most custodial lending platforms are not FDIC-insured. Even if they say they’re “regulated,” that doesn’t mean your funds are guaranteed. In traditional banking, if your local bank folds, the Federal Deposit Insurance Corporation (FDIC) steps in and covers up to $250,000. In digital assets – it’s unlikely.
Take BlockFi, for instance. Before its collapse, many users thought their funds were “safe” because the company claimed to follow U.S. regulations. But when it went bankrupt, users became creditors in a long legal queue – not insured depositors.
Now compare that to non-custodial platforms like Aave or 8lends. They don’t claim to be regulated. They’re protocols, not companies. And because they never take custody of your funds, there’s no false sense of protection. You’re in full control – and full responsibility. One of the innovative measures that 8lends offers is it backs its loans with borrower collateral in addition to the ability to spread out investor risk inherent in crowdlending. That’s another important consideration when it comes to risk.
Let’s break it down with a comparison:
Compliance Comparison: Custodial vs Non-Custodial Platforms
| Platform | Custodial? | Registered Entity | FDIC Insurance | Regulatory Oversight | KYC Required |
|---|---|---|---|---|---|
| BlockFi (RIP) | Yes | Yes (USA) | No | SEC lawsuits pre-collapse | Yes |
| Nexo | Yes | Yes (EU) | No | Regulatory pressure in EU | Yes |
| Celsius (RIP) | Yes | Yes (USA) | No | Ongoing bankruptcy process | Yes |
| Aave | No | No | No | Community-governed | No |
| Compound | No | No | No | Open-source protocol | No |
So what should you look for?
If you choose custodial, look for:
- Registration with a financial regulator (SEC, FCA, ASIC)
- Clear terms of service regarding fund handling
- External insurance (some platforms have limited private insurance)
If you go non-custodial:
- Verify the resource is open-source and community-audited
- Use wallets you control
- Learn how to interact safely with smart contracts
Bottom line: There’s no FDIC safety net in digital assets. The safest approach is understanding the trade-offs – and avoiding platforms that overpromise.
Transparency & Audits
With custodial lending platforms, transparency is often optional and mostly PR-driven. You get dashboards, newsletters, maybe a blog post or two about “strategic partnerships.” But behind the scenes, you rarely know What Is RWA-Backed Lending? Real-World Collateral Explained, who’s borrowing, or how liquid the platform really is.
That was a huge issue with Celsius and Voyager. Both operated in the dark. Both froze withdrawals with zero warning. Users only found out after their funds were already gone.
Non-custodial platforms, on the other hand, wear their code on their sleeves. Their smart contracts are open-source. You can check how funds move, when, and why. Want to see how much is locked in a liquidity pool, you don't need a login or permission.
But transparency isn’t enough. Smart contracts must be audited. Just like you wouldn’t live in a house that hasn’t passed inspection, you shouldn’t trust your digital assets to a protocol with unaudited code.
Pro Tip: If a non-custodial app hasn’t been audited within the last year, proceed with caution. On-chain code moves fast. Bugs discovered in 2021 could still be lurking in 2025.
And always check who did the audit. Trustworthy names include:
- Trail of Bits
- CertiK
- OpenZeppelin
- Quantstamp
One more thing: a site might claim it’s audited, but never publish the results. That’s a red flag. If you can't verify the audit yourself, it doesn’t count.
Final Thoughts: Which Is Safer?
There’s no general answer for everyone. If you want simplicity, support, and a familiar interface, custodial platforms might suit you – as long as you’re okay with counterparty risk. If you want transparency, control, and a future-proof digital-asset experience, non-custodial platforms offer powerful tools but come with a steeper learning curve.
So ask yourself:
- Are you comfortable managing your own keys?
- Do you understand the risks of smart contracts?
- How much research are you willing to do?
The safest choice isn’t necessarily the most convenient. But it is the one that matches your risk tolerance, technical ability, and investment goals. Because in digital assets, safety isn’t just about technology but about making informed choices.
It’s hard to go wrong though with shared crowdlending, when you’re sharing the risk with a bunch of other lenders, in addition to collateral backing. If profiting in a low-risk milieu appeals to you, don’t hesitate to sign up on 8lends today.
Read next
Do You Have Any Questions?
All questionsThe platform has been audited by CertiK and Cyberscope, and all transactions are publicly visible on the Base blockchain. Two companies with clear responsibilities stand behind the platform: CLEARCHAIN CORP operates the platform and is registered as a Money Services Business with FINTRAC (Canada), and Maclear AG conducts due diligence and monitors collateral. So the platform is well regulated, transparent and accountable
If the project has BuyBack, the partner buys the loan and returns 100% of the principal once it is overdue for 60 days or more. Without BuyBack, Maclear AG initiates the sale of the collateral, and the proceeds are distributed proportionally among investors. Since launch there have been no defaults
The platform is operated by CLEARCHAIN CORP, registered in Canada as a Money Services Business (MSB) and subject to mandatory AML/CFT compliance requirements under FINTRAC. Settlements are made in USD. The platform is not a CASP, so DAC8 requirements do not apply
Small and medium-sized businesses in developing regions do not have easy access to bank financing and are willing to pay higher rates than businesses in the EU or US
You can sell your position to another investor through the Secondary Market before the end of the loan term. With Fastlending there is no fixed term: the principal and accrued income can be withdrawn at any time
The minimum investment is 100 USD
Risk of non-payment by the business, risk of changes in the value of the collateral, risk of limited liquidity if there is no buyer on the Secondary Market, and technical risk associated with the smart contract
Investments from 100 to 500 USD are available without KYC. For amounts over 500 USD, full verification is required: an identity document and proof of address