
カストディアル型 vs ノンカストディアル型レンディングプラットフォーム:どちらがより安全か?
2025年6月24日3 分で読めます
暗号資産5,000ドル分がウォレットの中でただ眠っている状況を想像してみてください。それは増えていません。利回りも生んでいません。そこで、貯蓄口座のように利息を得られる融資プラットフォームを検討し始めます。しかし、ふと気づくのです。これは本当にどれほど安全なのか、と。DeFiに飛び込むにせよ、中央集権型金融(CeFi)の快適さにとどまるにせよ、カストディ(資産管理)の問題はすぐに浮上します。BlockFiのようなアプリに自分の鍵を預けるべきか?それとも自分でコントロールを保ち、ノンカストディアルを選ぶべきか?それはまるで、派手なネオバンクの高金利貯蓄口座を選ぶか、マットレスの下に金塊を隠しておくかを選ぶようなものです。どちらにも利点があります。どちらにもリスクがあります。DeFi(分散型金融)はあなたに主導権を与えますが、技術的な知識を要求します。CeFi(中央集権型金融)はシンプルさを約束しますが、盲目的な信頼を求めます。これは単なる技術的な話ではありません。これはあなたの生計そのものに関わることです。何十億もの利用者資金が、ハッキング、破産、そして誤った判断によって失われてきました。カストディアル型とノンカストディアル型のレンディングプラットフォームを理解することが、安定した収入を得られるかどうかと、それがすべて消え去ってしまうかどうかを分ける決め手になるかもしれません。では、詳しく見ていきましょう。
Why This Safety Comparison Matters
なぜなら、ブロックチェーンを活用したレンディングにリスクがないわけではないからです。ニュージャージー州に拠点を置くBlockFiは、FTXへのエクスポージャーを理由に出金を一時停止し、破産を申請しました(ロイター報道)。2022年には、Celsiusが市場の圧力で破綻し、顧客に10億ドルの不足額を残しました(その後70億ドルに修正)。 一方、Cream Financeのような分散型レンディングアプリは、3度目の攻撃で1億3,000万ドル以上をハッキングされました。
Safety isn’t just about code or reputation. It’s about control, transparency, and trust. And depending on how much risk you can stomach, one platform may suit you better than the other. So let’s dissect each side.
What Are Custodial Lending Platforms?
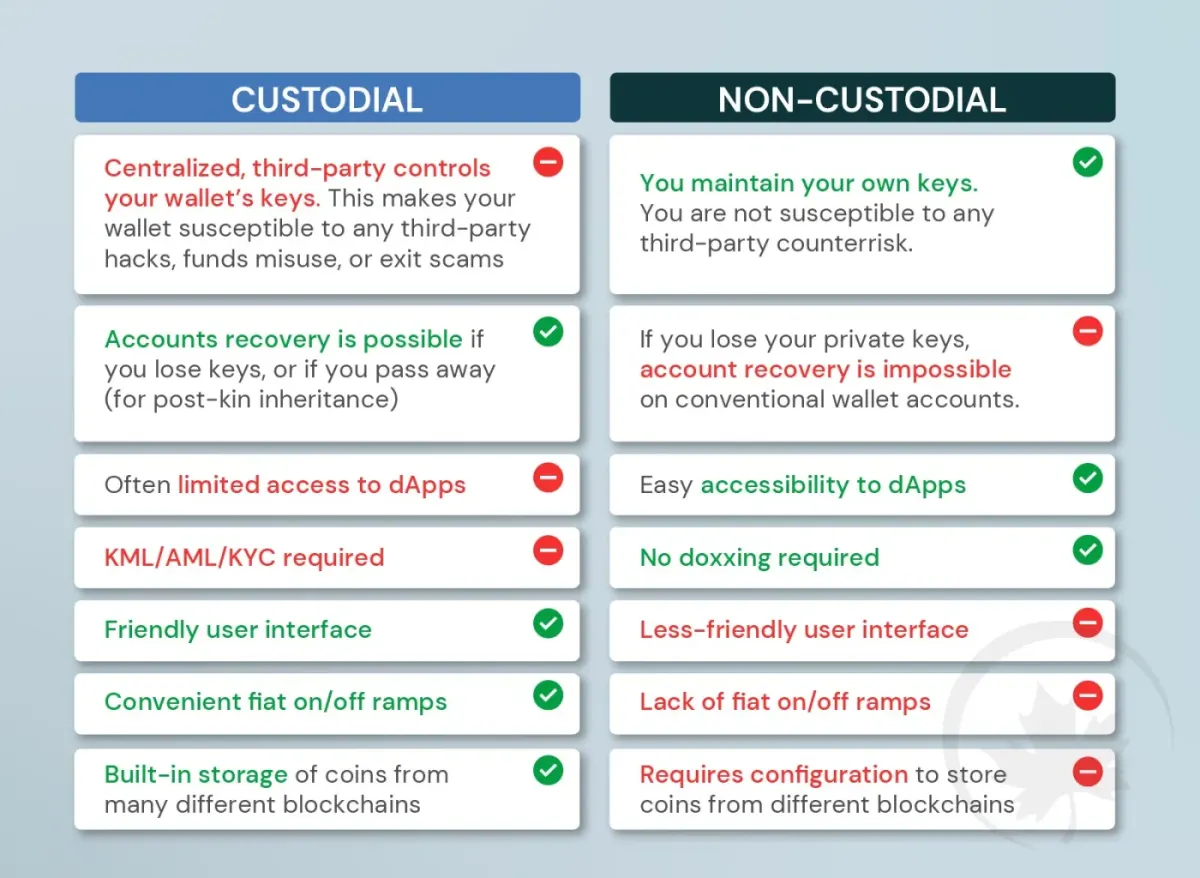
カストディアル型プラットフォームは、デジタルアセット業界における中央集権型カストディ型プラットフォームの銀行のような存在です。資産を預けると、その管理権を委ねることになります。プラットフォームが資金を保管し、ローンを管理し、リターンを約束します。これらのサービスは通常、リスク評価から利息の支払いまで、すべてを担う従来型の金融機関のように機能します。
例としてはNexo、Celsius(存続していた当時)、BlockFiなどがあります。デジタル資産を預けると、プラットフォームがそれを貸し出し、利息を受け取れます。簡単でしょう?ただし、うまくいかなくなるまでの話です。
Custodial lenders often operate behind closed doors. That means you don’t see where your money’s going or how they manage risk – until something breaks. When FTX collapsed, even platforms not directly tied to it suffered. Because trust is fragile when control is elsewhere.
Here’s a quick breakdown of the pros and cons of custodial learning:
| Pros | Cons |
|---|---|
| Easy to use – no wallets or blockchain jargon | You don’t control your keys or assets |
| Often offer customer support | Risk of platform insolvency or mismanagement |
| Sometimes insured or regulated | Funds may be lent to risky borrowers |
| Fixed interest rates | Withdrawals can be paused in crises |
| KYC/AML processes help with compliance | Little transparency into internal operations |
What Are Non-Custodial Lending Platforms?
これが、大胆でありながら透明性の高いブロックチェーンレンディングの世界です。ノンカストディアル型のアプリでは、管理権を保持したままデジタル資産を貸し出せます。ウォレット(MetaMaskなど)を接続し、レンディングプールを選び、直接利息を得られます。あなたのデジタル資産は、他人の保管庫ではなく、自分のウォレットやスマートコントラクトの中にとどまります。
There’s no support team holding your hand. But you get full autonomy, real-time data, and (usually) better rates. It's like doing your own taxes with spreadsheets – painful, but transparent. But heads up – non-custodial doesn’t mean risk-free. Smart contracts can be exploited. And if you lose access to your wallet? That's tough luck.
Here's a look at the pros and cons of noncustodial lending:
| Pros | Cons |
|---|---|
| Complete control of assets | Non-existent tech care – you're on your own |
| Transparent, open-source protocols | Possible contract bugs |
| Usually greater returns | Requires more technical know-how |
| No KYC – privacy-focused | Regulatory uncertainty can affect usage |
| Liquidity pools visible in real time | UX may spook beginners |
Security Risks Compared
アプリの見た目がどれほど洗練され、モデルがどれほど有望に見えても、ブロックチェーンを活用したレンディングにリスクがないわけではありません。カストディアル型もノンカストディアル型も、セキュリティ問題で大きな打撃を受けてきました。
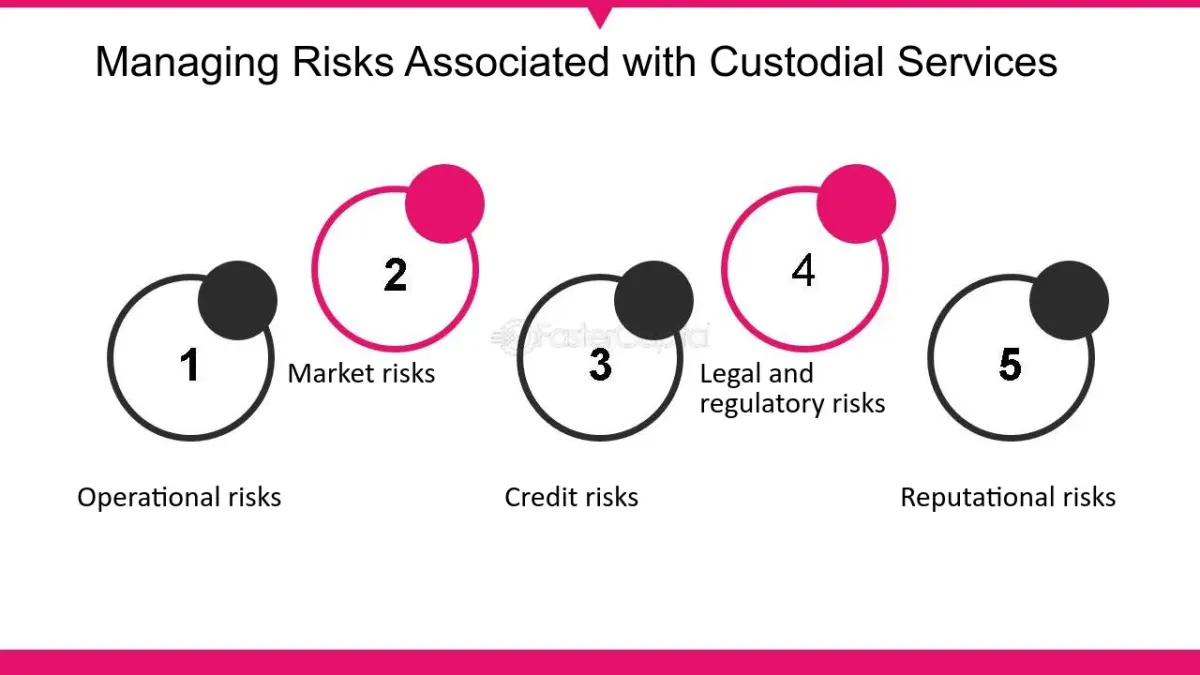
Custodial environments face risks like:
- Platform mismanagement
- Regulatory slamming
- Internal fraud or leaks
- Bankruptcy events (BlockFi, FTX-related collapses)
Non-custodial environments deal with:
- Smart contract exploits
- Oracle manipulation (price feed attacks)
- Flash loan attacks
- Code vulnerabilities left unpatched
Number of Major Lending Platform Exploits (2020–2024)
| Year | Custodial Incidents | Non-Custodial Incidents |
|---|---|---|
| 2020 | 3 | 5 |
| 2021 | 6 | 9 |
| 2022 | 11 | 14 |
| 2023 | 7 | 6 |
| 2024 | 5 | 4 |
Here’s the twist: custodial apps tend to fail big – one collapse and users lose everything. Non-custodial exploits often affect one protocol or contract, not the whole ecosystem. The damage is visible and traceable.
User Responsibility and Risk Tolerance
So who should hold the keys – you or the site?
If you use a custodial service, you are outsourcing accountability. This is okay if you’re just getting your feet weet or don’t wish to manage your own repository. Bear in mind though that should they mess up, you eat it.
In dealing with non-custodial services, you’re the bank. You approve smart contracts, manage private keys, and decide which pools to lend into. Passwords can’t be refetched. No customer support hotline.
It’s a trade-off between control and less hassle.
Basically:
- Custodial: Like a ride-hailing program. The driver and app control everything.
- Non-custodial: Like riding your own motorbike. More freedom, more skill required.
Custody Risk Scale (User vs Platform Control)
| Type | User Asset Control | Transparency | Technical Skill Required | Potential Yield |
|---|---|---|---|---|
| Custodial | Low | Low | Low | Medium |
| Hybrid | Medium | Medium | Medium | Medium |
| Non-Custodial (e.g., Aave) | High | High | High | High |
Tip: If you’re not ready to manage your private keys, don’t go buck-wild into blockchain lending with your life savings. Start small. Test the tides.
Regulatory and Insurance Implications
ここで避けて通れない話題、規制について取り上げましょう。数千ドル規模のデジタル資産をあるサイトに預けるのであれば、こう問うのは当然です。事態が悪化したとき、誰が助けてくれるのか?
実情はこうです。ほとんどのカストディアル型レンディングプラットフォームはFDICの保険対象ではありません。「規制されている」と謳っていても、資金が保証されるとは限りません。従来の銀行業務では、地元の銀行が破綻した場合、連邦預金保険公社(FDIC)が介入し、最大25万ドルまで補償します。デジタル資産の世界では、それは期待しにくいのです。
Take BlockFi, for instance. Before its collapse, many users thought their funds were “safe” because the company claimed to follow U.S. regulations. But when it went bankrupt, users became creditors in a long legal queue – not insured depositors.
Now compare that to non-custodial platforms like Aave or 8lends. They don’t claim to be regulated. They’re protocols, not companies. And because they never take custody of your funds, there’s no false sense of protection. You’re in full control – and full responsibility. One of the innovative measures that 8lends offers is it backs its loans with borrower collateral in addition to the ability to spread out investor risk inherent in crowdlending. That’s another important consideration when it comes to risk.
Let’s break it down with a comparison:
Compliance Comparison: Custodial vs Non-Custodial Platforms
| Platform | Custodial? | Registered Entity | FDIC Insurance | Regulatory Oversight | KYC Required |
|---|---|---|---|---|---|
| BlockFi (RIP) | Yes | Yes (USA) | No | SEC lawsuits pre-collapse | Yes |
| Nexo | Yes | Yes (EU) | No | Regulatory pressure in EU | Yes |
| Celsius (RIP) | Yes | Yes (USA) | No | Ongoing bankruptcy process | Yes |
| Aave | No | No | No | Community-governed | No |
| Compound | No | No | No | Open-source protocol | No |
So what should you look for?
If you choose custodial, look for:
- Registration with a financial regulator (SEC, FCA, ASIC)
- Clear terms of service regarding fund handling
- External insurance (some platforms have limited private insurance)
If you go non-custodial:
- Verify the resource is open-source and community-audited
- Use wallets you control
- Learn how to interact safely with smart contracts
結論:デジタル資産の世界にFDICのようなセーフティネットは存在しません。最も安全なアプローチは、トレードオフを理解し、過剰な約束をするプラットフォームを避けることです。
Transparency & Audits
With custodial lending platforms, transparency is often optional and mostly PR-driven. You get dashboards, newsletters, maybe a blog post or two about “strategic partnerships.” But behind the scenes, you rarely know how loans are collateralized, who’s borrowing, or how liquid the platform really is.
That was a huge issue with Celsius and Voyager. Both operated in the dark. Both froze withdrawals with zero warning. Users only found out after their funds were already gone.
Non-custodial platforms, on the other hand, wear their code on their sleeves. Their smart contracts are open-source. You can check how funds move, when, and why. Want to see how much is locked in a liquidity pool, you don't need a login or permission.
しかし、透明性だけでは十分ではありません。スマートコントラクトは監査を受けている必要があります。検査に合格していない家に住まないのと同じように、監査されていないコードのプロトコルに自分のデジタル資産を預けるべきではありません。
プロのヒント:ノンカストディアル型アプリが過去1年以内に監査を受けていない場合は、慎重に進めてください。ブロックチェーンのコードは急速に進化します。2021年に発見されたバグが2025年になってもまだ潜んでいる可能性があります。
And always check who did the audit. Trustworthy names include:
- Trail of Bits
- CertiK
- OpenZeppelin
- Quantstamp
One more thing: a site might claim it’s audited, but never publish the results. That’s a red flag. If you can't verify the audit yourself, it doesn’t count.
Final Thoughts: Which Is Safer?
すべての人に当てはまる一般的な答えはありません。シンプルさ、サポート、慣れ親しんだインターフェースを求めるなら、カウンターパーティリスクを受け入れられる限り、カストディアル型プラットフォームが合っているかもしれません。透明性、コントロール、そして将来にも通用するブロックチェーン体験を求めるなら、ノンカストディアル型プラットフォームは強力なツールを提供しますが、学習曲線は急になります。
So ask yourself:
- Are you comfortable managing your own keys?
- Do you understand the risks of smart contracts?
- How much research are you willing to do?
最も安全な選択は、必ずしも最も便利な選択ではありません。しかしそれは、あなたのリスク許容度、技術的な能力、投資目標に合致する選択です。なぜならブロックチェーンの世界では、安全性は技術だけの問題ではなく、十分な情報に基づいて選択することの問題だからです。
It’s hard to go wrong though with shared crowdlending, when you’re sharing the risk with a bunch of other lenders, in addition to collateral backing. If profiting in a low-risk milieu appeals to you, don’t hesitate to sign up on 8lends today.
次に読む



ご質問はありますか?
すべての質問プラットフォームはCertiKとCyberscopeの監査を受けており、すべての取引はBase上で公開されています。明確な役割を持つ2社が支えています:CLEARCHAIN CORP(プラットフォームの運営、カナダのFINTRACにMSBとして登録)、Maclear AG(デューデリジェンスと担保)。適切に規制され、透明性と説明責任のある運営です
BuyBack付きの案件なら、60日以上の延滞でパートナーがローンを買い取り、元本の100%を返還します。BuyBackがない場合はMaclear AGが担保の売却を開始し、収益は投資家に比例配分されます。ローンチ以来デフォルトはありません
プラットフォームを運営するのはCLEARCHAIN CORPで、カナダでMoney Services Business(MSB)として登録され、FINTRACのもとで義務的なAML/CFTコンプライアンス要件の対象となっています。決済はUSDで行われます。プラットフォームはCASPではないため、DAC8の要件は適用されません
発展途上地域の中小企業は銀行融資へのアクセスが難しく、EUや米国の企業より高い金利を受け入れています
満期前にセカンダリーマーケットで他の投資家にポジションを売却できます。Fastlendingには固定期間がなく、元本と収益はいつでも引き出せます
最低投資額は100 USDです
企業の不払いリスク、担保価値の変動リスク、セカンダリーマーケットで買い手がいない場合の流動性リスク、スマートコントラクトに関わる技術的リスク
100〜500 USDの投資はKYC不要です。500 USD超は本人確認書類と住所証明による完全な認証が必要です