
How P2P User Funds Are Protected Behind the Scenes
August 7, 20255 min read
Peer-to-peer crowdlending is a revolutionary, modern financial framework that bypasses intermediary banks by directly connecting investors and borrowers. While more investors want diversification and higher returns, they usually have one question about P2P crowdlending: “How safe are the users’ funds?”In this article, we'll dive into the unique blend of technology, regulatory oversight, and operational strategies that keep investor money safe.
How P2P Crowdlending Has Evolved Over the Years
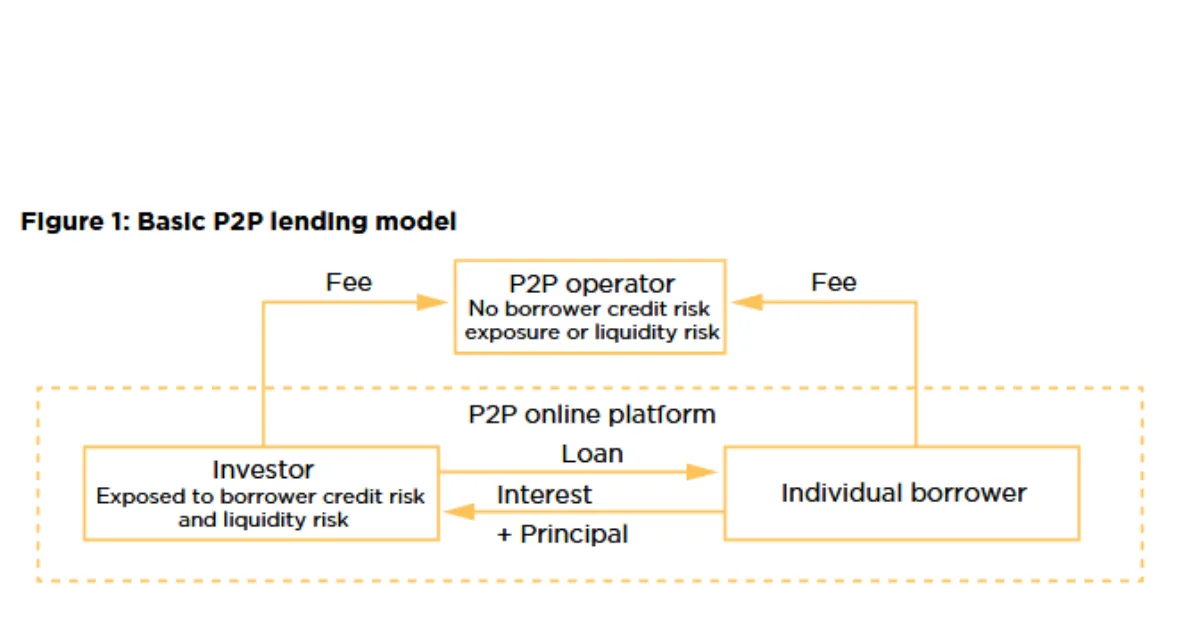
P2P crowdlending platforms have gone mainstream over the past decade. Initially, most people considered P2P lending a special market suited only to tech-savvy early adopters. Today, decentralized credit apps command headlines, and investors and borrowers flock to them for all their funding and income-generation needs.
These innovations allow individuals to invest small amounts that collectively fund big loans. Over the years, the system has evolved rapidly, and so has the complexity of the systems used to safeguard investors' funds. Through advanced and integrated risk analysis tools, multi-level security measures, and adherence to rigorous regulatory frameworks, P2P websites are as secure as ever, especially in a decentralized digital community.
Historically, as P2P lending apps evolved, so did the threat environment; this prompted operators to rethink and strengthen their security systems and protocols. But security isn't just about keeping up with the latest tech. It's also about building and maintaining trust in the entire credit exchange process.
Why to Protect User Funds
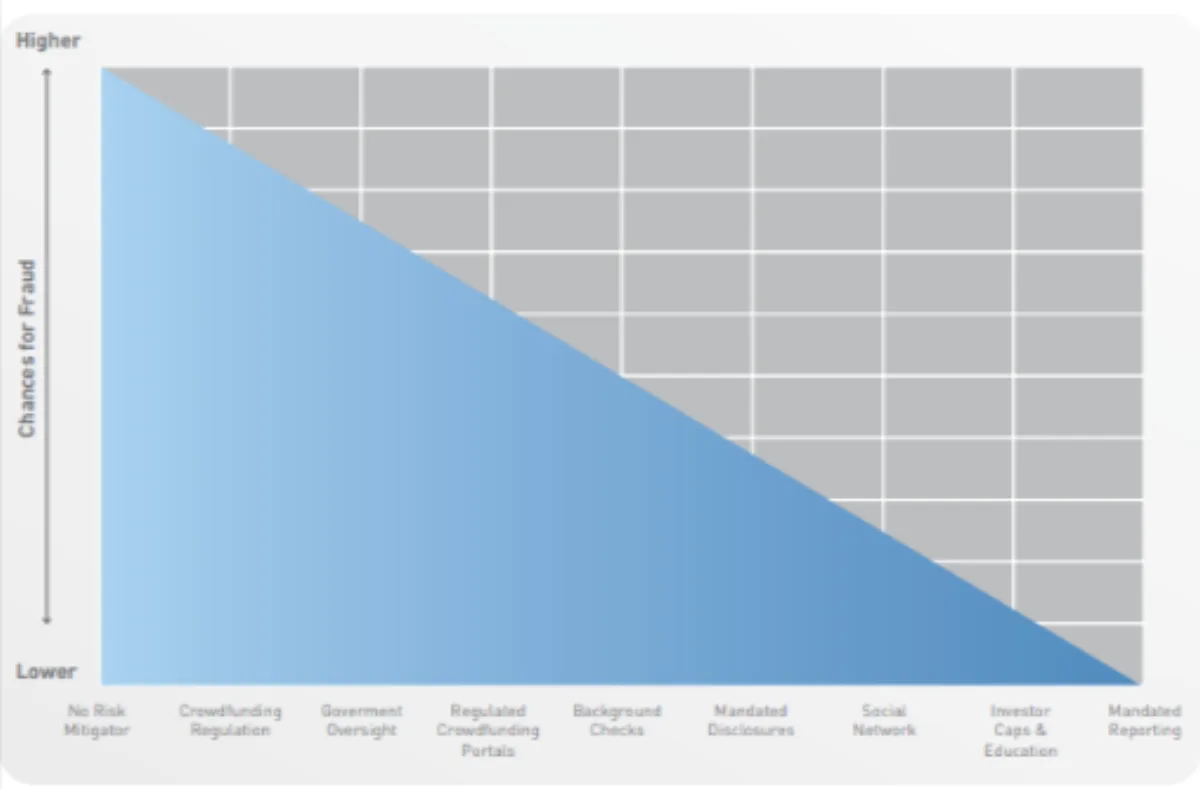
Traditional banks have decades of established regulations, oversight bodies, and deposit insurance. Since they're relatively new, decentralized exchanges must earn user trust by going above and beyond to protect investors' funds from fraud and modern threats like cyberattacks.
Studies from reputable financial journals emphasize that trust in any financial transaction is crucial, and risk mitigation strategies directly influence investor behavior.
Investors need to know they have transparency, good governance, and foolproof procedures in systems that can ensure every dollar is safe regardless of the market environment. The importance of this is impossible to overstate. Investors invest more when they know their money is safe from cyberattacks and other modern security threats.
Key Mechanisms Behind the Security Curtain
Separation of Funds
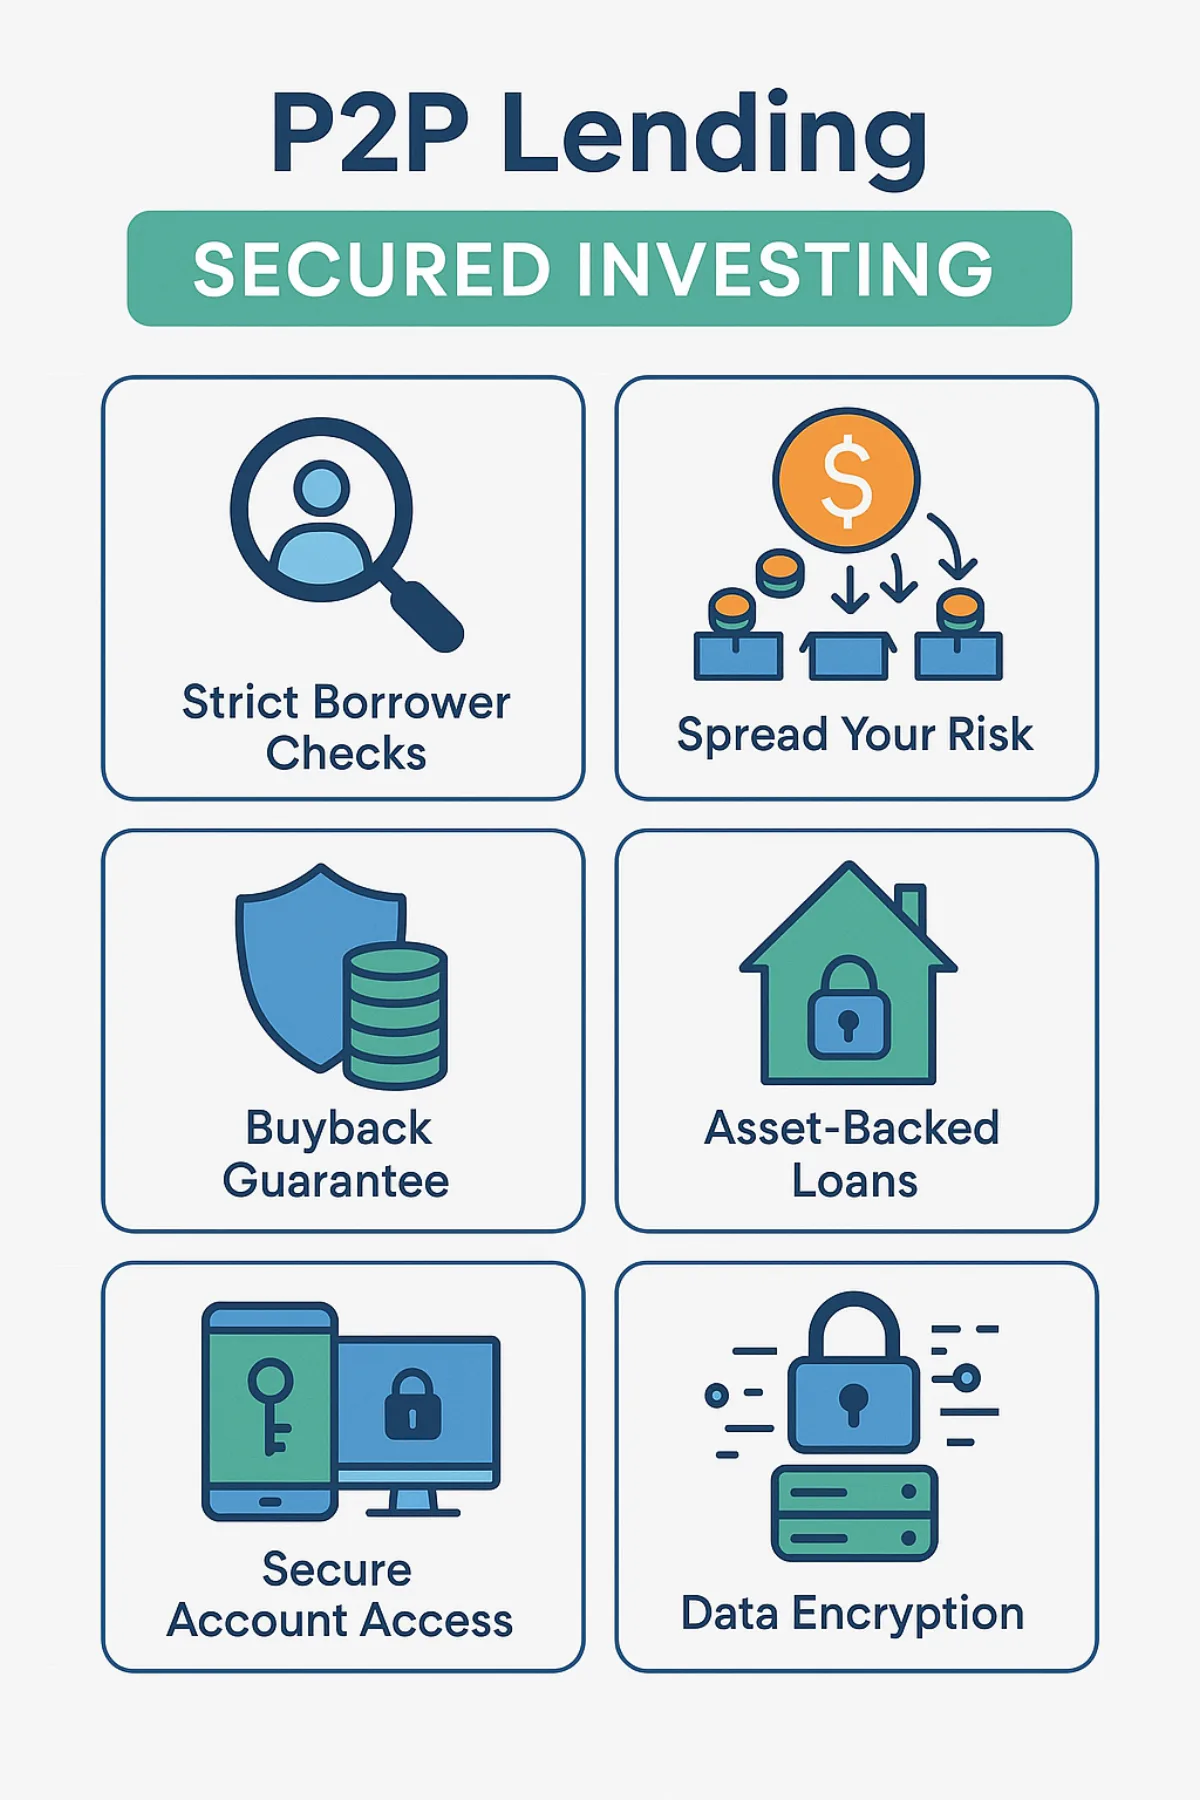
One of the most important security shields in peer-to-peer crowdlending is the segregation of funds. Basically, most such apps have 'baskets' for all accounts. This separates all accounts and ensures that a vulnerability on a specific account does not become systemic. This simple strategy is practical and effective.
Additionally, certified custodians work with these apps to add extra layers of protection and separation for deposited funds.
Escrow Accounts and Third-Party Custodians
Top peer-to-peer websites use escrow accounts to manage the transfer of funds. A typical transaction in this milieu involves an investor financing a loan by directing funds into an escrow account. After that, when borrowers meet the loan terms, the system processes and dispenses the loan.
Escrow accounts promote protection on P2P lending apps because they minimize fraud and system abuse by checking and verifying the legitimacy of each transaction. Reputable third-party custodians enhance security by conducting external audits for P2P platforms, such as 8lends for example, that check and verify each transaction and system.
Regulatory Compliance and Oversight
The decentralized credit landscape is no longer ungoverned, thanks to increasing regulatory oversight that has brought much-needed discipline. Today, crowdlending systems abide by rules and guidelines created by federal and state bodies like the SEC, FCA, and ESMA.
Regulatory bodies protect investors' money by overseeing financial activity and enforcing rigorous fund protection measures, risk disclosure, and transparency. Regulation compliance lowers system-wide risks, threats, and vulnerabilities that hackers could exploit to game the system.
Digital Safety and Cyber Awareness
The modern world has many evolving and developing cybersecurity threats. That's why well-established decentralized credit platforms advocate for digital awareness and cyber safety.
Most of these apps use various security practices to protect investor money.
- Firewalls and intrusion detection systems: These systems monitor the front and backend systems for threats and malicious activity.
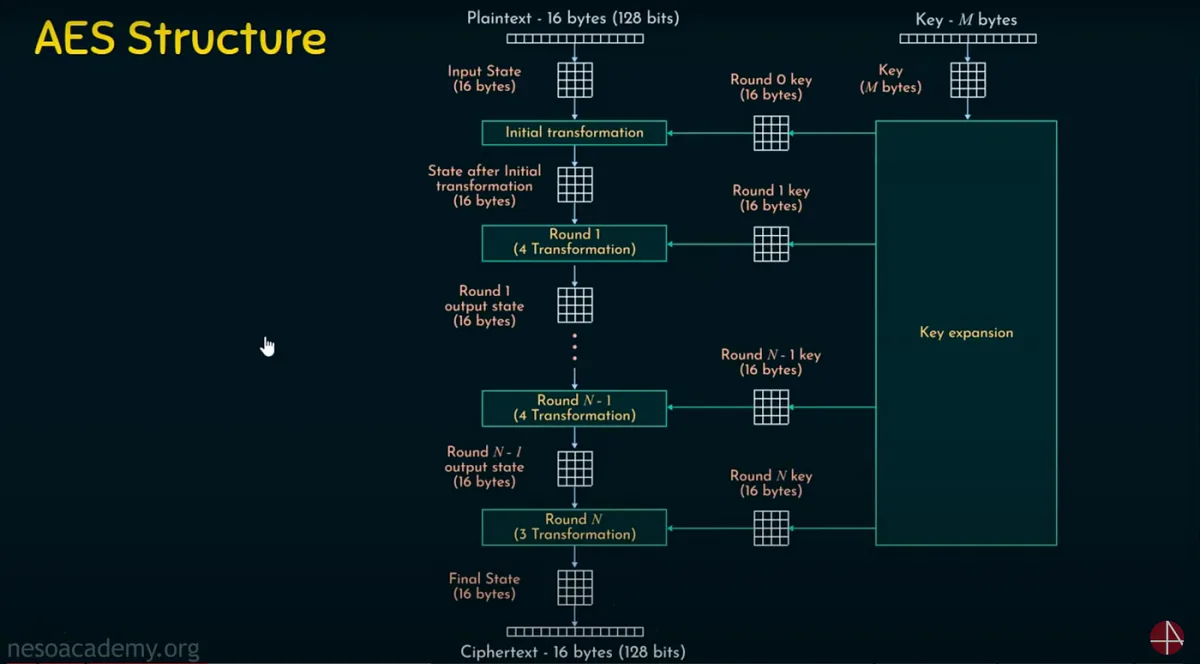
- Encryption protocols: Data encryption protects sensitive information while it's in transit and at rest. Protocols like the Advanced Encryption Standard (AES) are critical because they protect the systems and every transaction.
- 2FA: Almost all P2P crowdlending resources have implemented app or USSD-based two-factor authentication. Adding this security layer significantly reduces unauthorized account access.
- Regular What Is RWA-Backed Lending? Real-World Collateral Explained: Periodic audits by custodians and third-party cybersecurity experts can help confirm a system’s ability to ward off evolving cybersecurity threats.
Risk Detection and Fraud Management Algorithms
Since we're knee-deep in the AI era, many peer-to-peer crowdlending resources have integrated sophisticated large language and machine learning models as well as tools into their backend security systems to identify and stop fraudulent activity.
These algorithms scan massive data sets to discover anomalies, trends, or warning signs in borrowers' behavior and transactions. This integration minimizes the probability of fraud and reduces the marketplace's overall risk profile.
Transparent Reporting and Independent Audits
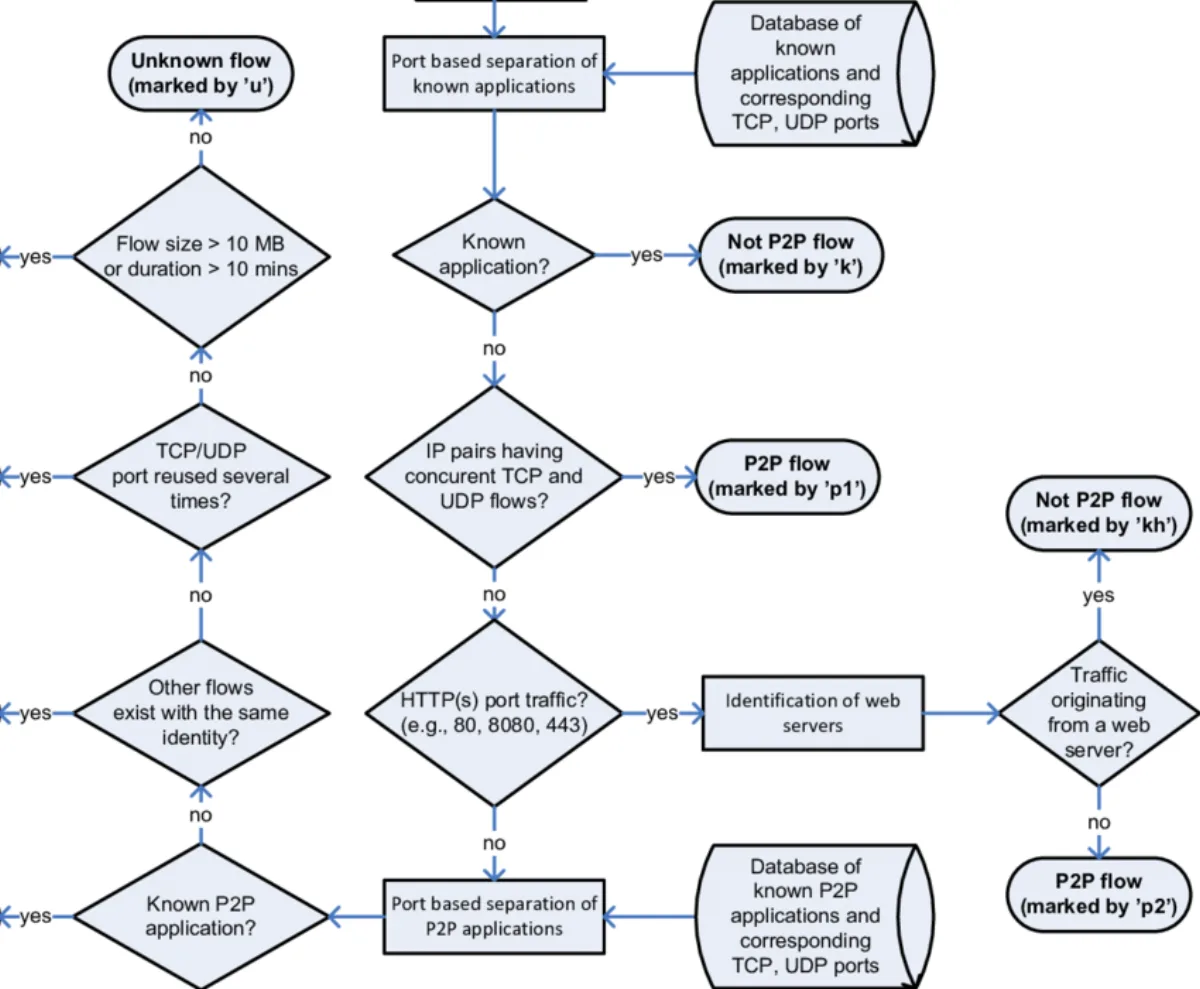
Transparency is a cornerstone in building long-term investor trust. To that end, most popular peer-to-peer apps issue regular transparency reports that include in-depth fund flow breakdowns, risk assessments, and security procedures.
Independent third-party annual or bi-annual audits enhance security and user trust by objectively assessing the platform's financial health and operational integrity.
Technology and Human Oversight
State-of-the-art technology is the core system that secures user funds on P2P crowdlending platforms. Still, the human element – think oversight, expertise, and moral sophistication – is important to complete the security landscape.
Regulatory experts, cybersecurity professionals, and risk managers work together to monitor the virtual and operational worlds for threats. Coordinated human supervision can intervene promptly, even when an algorithm fails to identify a potential threat. When P2P lending platforms integrate AI and human monitoring, it creates a secure system that investors and borrowers can trust.
Platforms take things a step further by engaging with their communities, providing access to security protocols, sharing updates on threat intelligence, and offering support in the case of suspicious account behavior. This transparency builds trust, community, and security awareness among users.
Conclusion
A delicate dance between innovation and security lies at the heart of all the successful P2P crowdlending platforms. From keeping funds separate and using escrow accounts to utilizing next-generation encryption and AI-driven anti-fraud analysis, these platforms spend enormous amounts of money on protecting each dollar placed in their care.
There are many reasons to take advantage of this spectacular technology to access credit opportunities like never before and profit handsomely off of providing it with minimal risk. 8lends has meanwhile never encountered a default or a late payment and allows investors to share their risk, spreading it out among multiple projects, with no commission fee.
Read next



Do You Have Any Questions?
All questionsThe platform has been audited by CertiK and Cyberscope, and all transactions are publicly visible on the Base blockchain. Two companies with clear responsibilities stand behind the platform: CLEARCHAIN CORP operates the platform and is registered as a Money Services Business with FINTRAC (Canada), and Maclear AG conducts due diligence and monitors collateral. So the platform is well regulated, transparent and accountable
If the project has BuyBack, the partner buys the loan and returns 100% of the principal once it is overdue for 60 days or more. Without BuyBack, Maclear AG initiates the sale of the collateral, and the proceeds are distributed proportionally among investors. Since launch there have been no defaults
The platform is operated by CLEARCHAIN CORP, registered in Canada as a Money Services Business (MSB) and subject to mandatory AML/CFT compliance requirements under FINTRAC. Settlements are made in USD. The platform is not a CASP, so DAC8 requirements do not apply
Small and medium-sized businesses in developing regions do not have easy access to bank financing and are willing to pay higher rates than businesses in the EU or US
You can sell your position to another investor through the Secondary Market before the end of the loan term. With Fastlending there is no fixed term: the principal and accrued income can be withdrawn at any time
The minimum investment is 100 USD
Risk of non-payment by the business, risk of changes in the value of the collateral, risk of limited liquidity if there is no buyer on the Secondary Market, and technical risk associated with the smart contract
Investments from 100 to 500 USD are available without KYC. For amounts over 500 USD, full verification is required: an identity document and proof of address