
Common misconceptions about P2P lending risk exposure
September 2, 20253 min read
Peer-to-peer lending (P2P) lets people lend money to others through online sites instead of going through banks. It offers higher interest for lenders and easier loans for borrowers. Simple and helpful as it seems though, there are risks too which people don’t suspect. Here, we clear up common misunderstandings about P2P lending risks with insights from several places, to give you a well-rounded perspective.
What is P2P Lending?
Peer-to-peer lending began as a new choice beyond banks so that lenders could earn more and borrowers could get money faster. Yet the risks are often missed. Borrowers can default, and platforms have the possibility of failing. P2P lending grew out of crowdfunding and expanded fast when fintech took off, bringing many new users on board. Yet some ideas about its dangers are off the mark, and that can lead to choices that cost people.
The biggest problems though are the myths that grew with the popularity of P2P lending. Let’s tackle eight of these myths while backing up our stand with up-to-date data and expert insights.
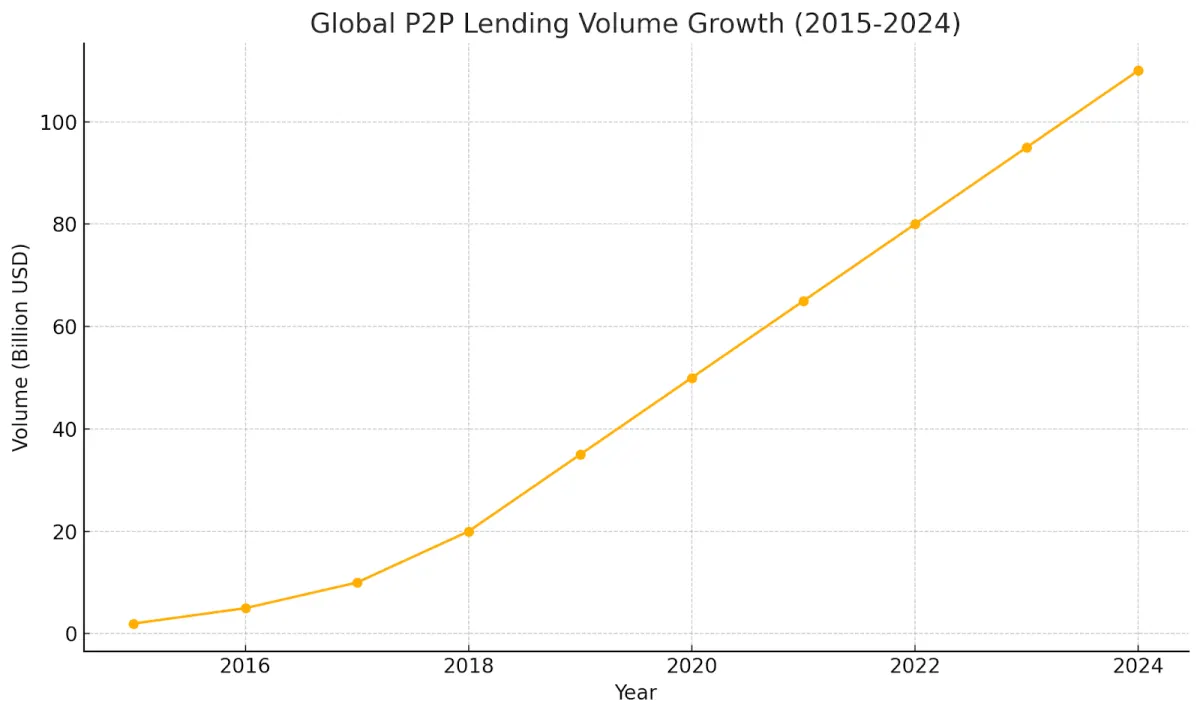
Detailed Misconceptions and Realities
Many investors put all their faith in broad claims about peer-to-peer lending without reading the fine print. Digging into the real rules, tools, and safeguards gives a clearer view of what lies ahead. Some stories make P2P lending sound like a free-for-all. Others make it seem safer than it truly is.
We will cut through the hype and show the frameworks and practices that shape real outcomes. This close look explains how regulation, credit checks, default handling, and market shifts work together so that your choices rest on solid ground. With that settled, we can tackle the first big myth.
Misconception #1: P2P Lending is Unregulated and Unsafe
Myth: Many investors think P2P lending runs without rules like the Wild West and is very risky.
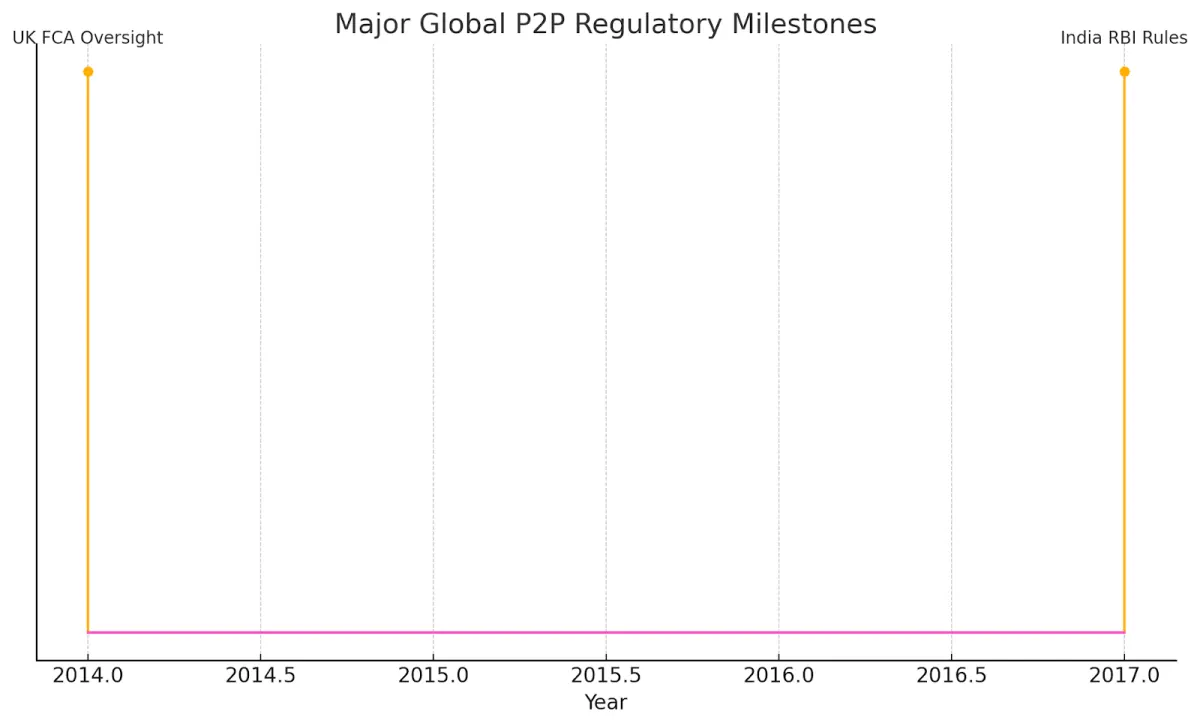
Reality: P2P lending faces rules in many places. In the UK, the Financial Conduct Authority (FCA) has overseen it since 2014 so that platforms follow clear standards and protect users. In India, the Reserve Bank of India (RBI) set rules in 2017 requiring clear disclosures, escrow accounts, and risk warnings. Rules cut some risk, but defaults and platform failures still happen, so investors need to stay alert.
Misconception #2: All Borrowers on P2P Platforms Are High-Risk
Myth: People assume P2P only serves borrowers that banks reject.
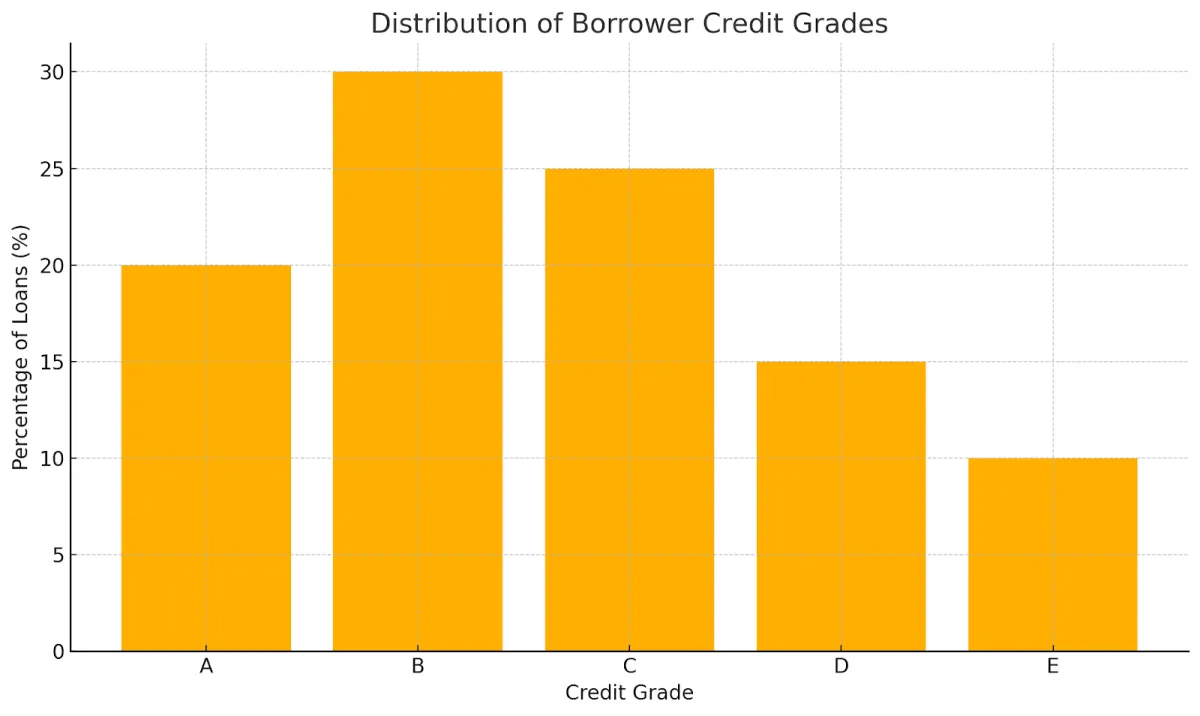
Reality: Platforms use tools and data to check credit. 8lends, for example, shows detailed borrower stats so lenders can judge risk for themselves. In Switzerland, rules force platforms to match lenders with a mix of credit grades, from top to lower scores. Investors choose loans by score, which cuts the sense that all borrowers are risky.
Misconception #3: P2P Lending Platforms Guarantee Loans
Myth: Some believe platforms insure loans like banks do with deposits.
Reality: Most P2P sites only connect lenders and borrowers. Lenders bear all the credit risk if a borrower can’t pay. Investopedia warns that lenders must plan for defaults. RBI rules in India bar platforms from promising repayment support. A few platforms offer “provision funds,” but these vary in scope and do not guarantee full repayment.
Misconception 4: Diversification Eliminates All Risk in P2P Lending
Myth: Spreading money across many loans eliminates all risk.
Reality: Putting money into many loans cuts the hit if one fails, but it does not remove other risks. Experts note risks like too much exposure on one platform or a broad market downturn. A study shows that lending too much to any one borrower still raises default probability. Diversification helps, but it is not a complete shield.
Misconception #5: P2P Lending is as Safe as Bank Deposits
Myth: Some compare P2P safety with bank savings accounts.
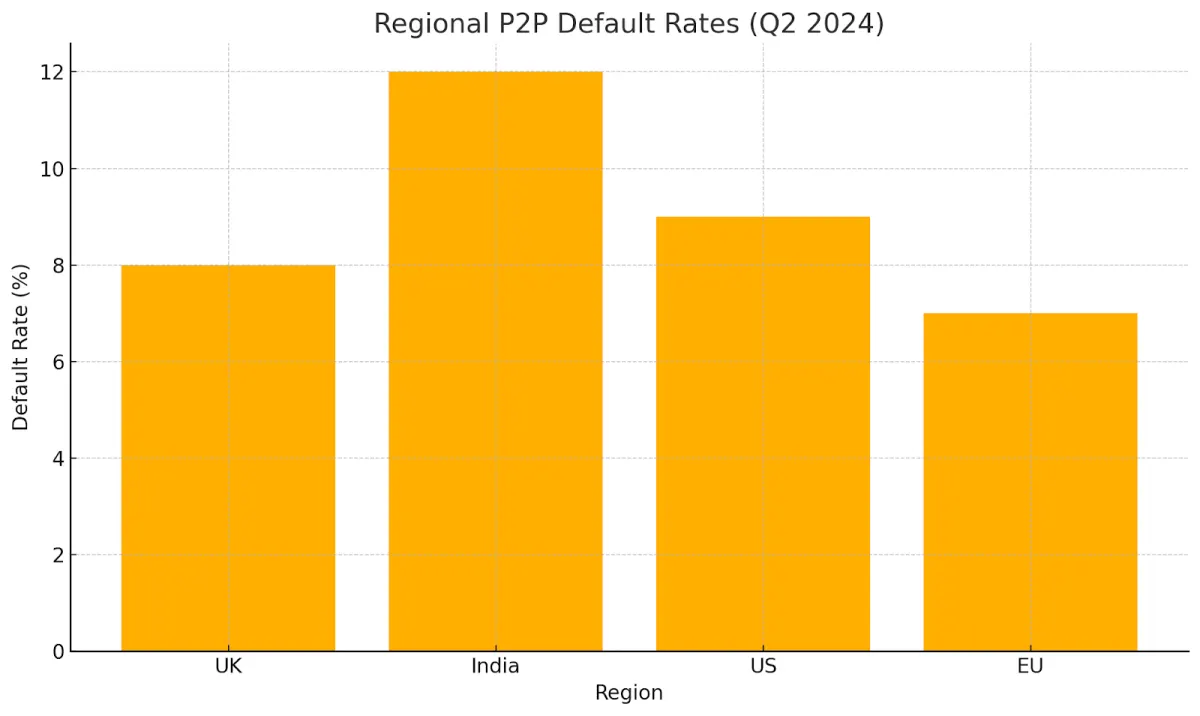
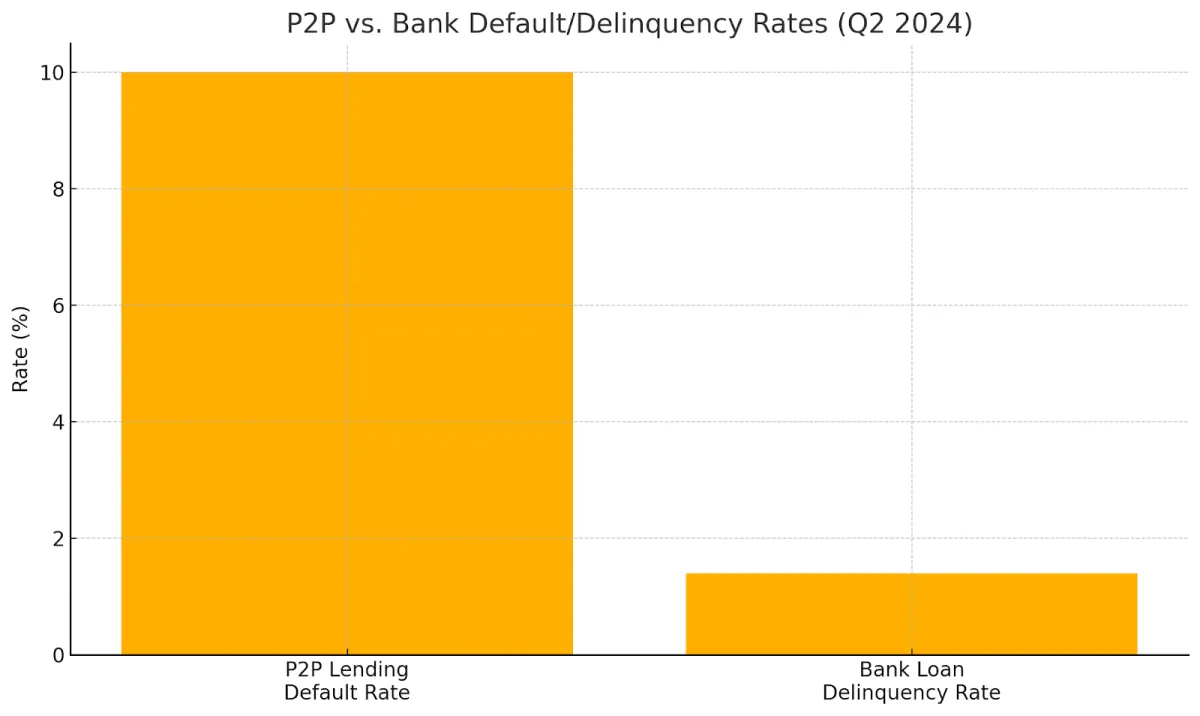
Reality: Bank deposits often carry government insurance, but P2P loans do not. Individual investors take all the risk. P2P default rates can top 10 percent, while bank delinquency sits near 1.4 percent as of Q2 2024. Higher returns reflect higher risk, making P2P very different from a savings account.
Misconception #6: It’s Impossible to Assess Risk in P2P Lending
Myth: Many assume risk checks are too complex or that data is lacking.
Reality: Platforms give plenty of tools: credit scores, loan grades, and past performance charts. Third-party services like Orchard and dv01 add more layers of risk analysis. Investors use these details to match loans to their own comfort level.
Misconception #7: P2P Lending Investments Are Highly Liquid
Myth: Investors often think they can pull out money anytime.
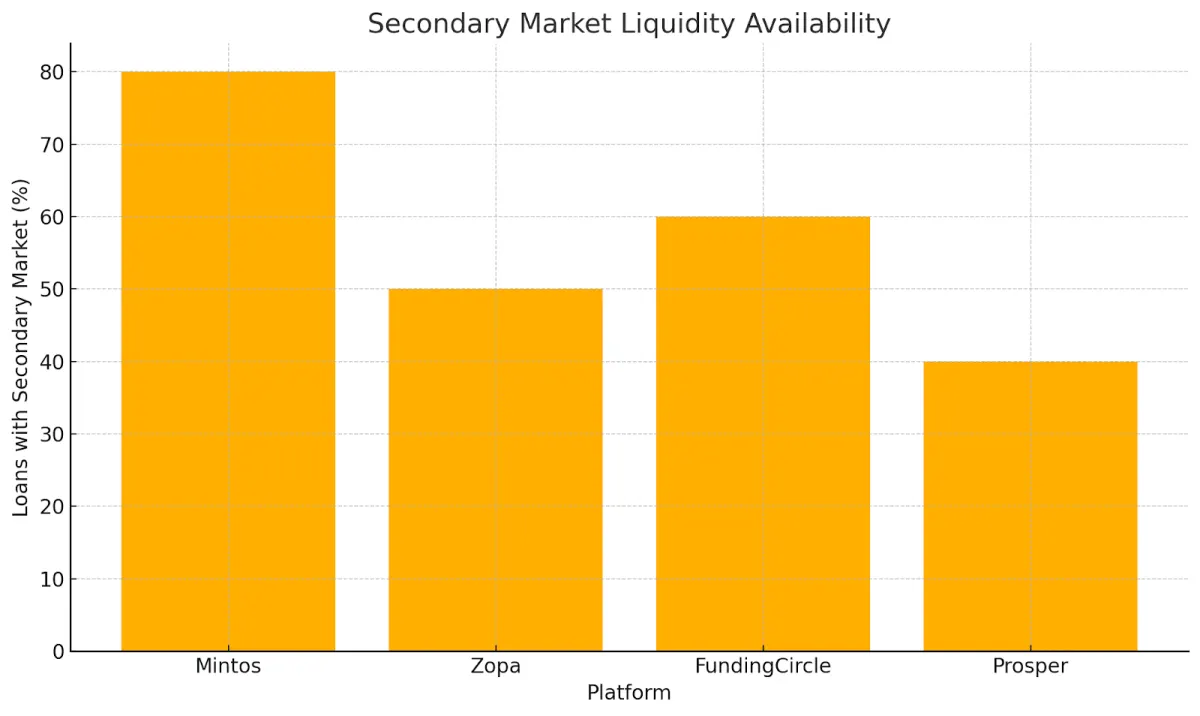
Reality: Liquidity depends on the platform. Some run a secondary market for loan sales, but that can dry up in tough times. Experts warn that if loans can’t be sold early, cash stays locked up, and you may miss other chances. Planning for possible delays is key, especially without a firm secondary market.
Misconception #8: P2P Platforms Are Immune to Cyber and Operational Risks
Myth: P2P sites never suffer hacks or outages. Lenders assume their data and money stay safe at all times.
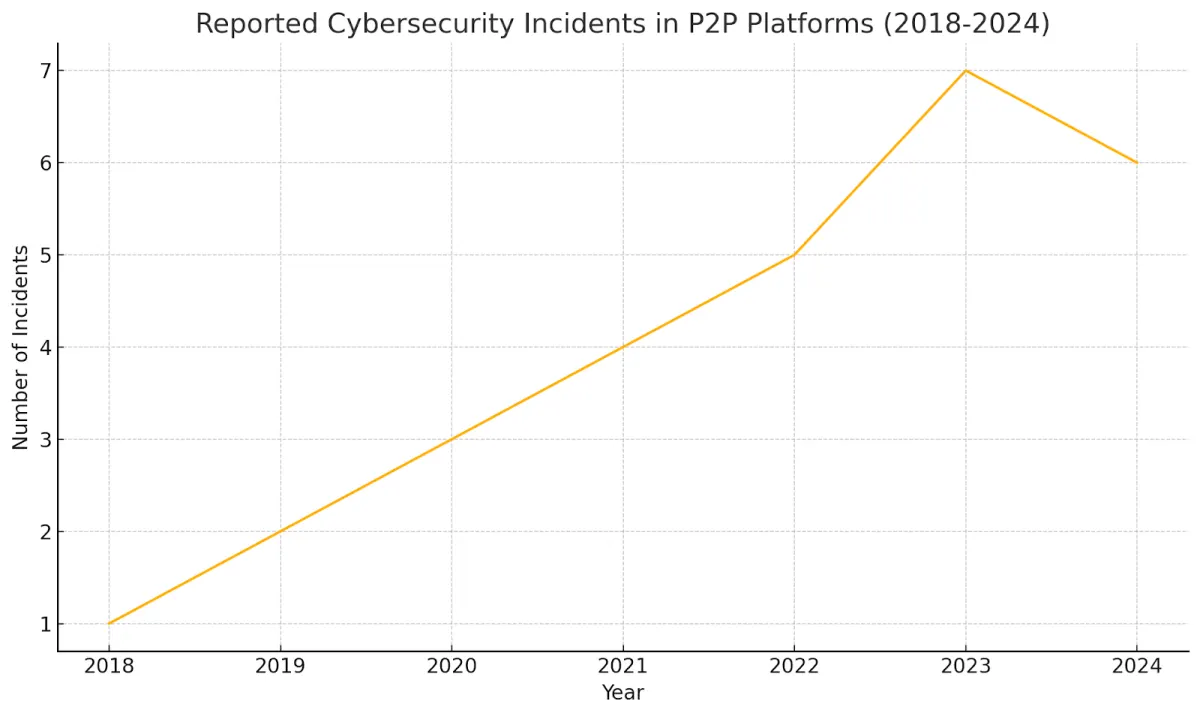
Reality: Platforms face cyberattacks and system failures that can expose personal details or lock up funds during downtime. Breaches may lead to identity theft or fraud, while outages stop loan servicing and trading.
To guard against this, solid platforms like 8lends use encryption, multi-factor authentication, regular security audits, pen tests, and clear incident-response plans. Before you lend, check a site’s security certifications and published risk controls so that you know how it handles these hidden threats.
To further illustrate, here's a table summarizing the risks and corresponding misconceptions:
| Risk Category | Misconception | Reality |
|---|---|---|
| Regulatory Risk | Unregulated and unsafe | Regulated in many countries, e.g., FCA, RBI, with consumer protection rules |
| Credit Risk | All borrowers are high-risk | Platforms assess credit, offering varied risk levels |
| Guarantee Risk | Platforms guarantee loans | Lenders bear credit risk; no guarantees are typically provided |
| Diversification Risk | Diversification eliminates all risk | Reduces but doesn't eliminate platform or systematic risks |
| Safety Risk | As safe as bank deposits | Riskier, no government insurance, higher default rates |
| Assessment Risk | Impossible to assess risk | Tools and data are available for risk evaluation |
| Liquidity Risk | Highly liquid investments | Varies, secondary markets are not always available, potential delays |
Cross-Border Lending and Regulatory Divergence
Cross-border P2P lending brings its own set of legal and regulatory headaches when money moves between countries. Each place has its own consumer safety rules, money controls, and tax laws that may hide extra fees or legal traps. Doing solid legal homework, picking platforms that lay out all their rules clearly, and learning how local fintech rules work are key steps to expand abroad safely.
Implications for Investors
Knowing these mistakes helps you handle risk better. Investors need to look into platform rules and review borrower backgrounds so that they understand who they are backing. Accept that loans can go bad. Spread your money around to lower risk.
Remember, it is riskier than banks. Use tools to check risk and plan for cash needs. The peer-to-peer lending market is growing, and AI How Due Diligence Works on 8lends: 40+ Criteria Explained brings new help, but learning remains key.
Conclusion
Peer-to-peer lending provides good opportunities to earn returns. It requires a clear view of the possible downsides though so that you do not get caught off guard or take more risks than you want. Cutting out false beliefs lets investors make choices that fit their needs and what they can handle.
So far 8lends has yet to experience a default or a late payment and while risk can never be totally eliminated, it can be managed wisely and strategically. Collateral is used to back loans in case borrowers do default though and investors are charged zero commission on their earnings.
Read next



Do You Have Any Questions?
All questionsThe platform has been audited by CertiK and Cyberscope, and all transactions are publicly visible on the Base blockchain. Two companies with clear responsibilities stand behind the platform: CLEARCHAIN CORP operates the platform and is registered as a Money Services Business with FINTRAC (Canada), and Maclear AG conducts due diligence and monitors collateral. So the platform is well regulated, transparent and accountable
If the project has BuyBack, the partner buys the loan and returns 100% of the principal once it is overdue for 60 days or more. Without BuyBack, Maclear AG initiates the sale of the collateral, and the proceeds are distributed proportionally among investors. Since launch there have been no defaults
The platform is operated by CLEARCHAIN CORP, registered in Canada as a Money Services Business (MSB) and subject to mandatory AML/CFT compliance requirements under FINTRAC. Settlements are made in USD. The platform is not a CASP, so DAC8 requirements do not apply
Small and medium-sized businesses in developing regions do not have easy access to bank financing and are willing to pay higher rates than businesses in the EU or US
You can sell your position to another investor through the Secondary Market before the end of the loan term. With Fastlending there is no fixed term: the principal and accrued income can be withdrawn at any time
The minimum investment is 100 USD
Risk of non-payment by the business, risk of changes in the value of the collateral, risk of limited liquidity if there is no buyer on the Secondary Market, and technical risk associated with the smart contract
Investments from 100 to 500 USD are available without KYC. For amounts over 500 USD, full verification is required: an identity document and proof of address