
What Happens When a Borrower Defaults? The Recovery Process in P2P Lending
September 16, 20255 min read
Picture your friend in a bind, needing an urgent loan, but instead of going to a bank, she comes to you for the money and in return promises to pay back at a set time with a little extra something on top, interest of sorts. So you note it down to follow up on later. It is pretty much a win-win; the creditor can put their money to good use in exchange for greater returns than a regular savings account would provide; meanwhile, the applicant gets to enjoy a more flexible borrowing experience with potentially more lenient interest.
Plot twist, your friend vanishes into thin air without paying back.
P2P lending is rising as a compelling competitor to the banking system of old, by connecting individual parties directly, usually through an online platform. But when a credit holder fails to make good on the loan as agreed, it triggers a chain of recovery efforts. Here, we explore what happens when a person defaults in such a scenario, what lenders can expect, and how the host typically handles recovery.
P2P Lending Defaults
A default means the P2P borrower either missed payments or was unable to pay off the loan altogether. Each platform has its own way of defining when a loan goes into default.
- Late payment: 1–30 days overdue
- Delinquent: 30–60 days overdue
- Default: thresholds differ by platform — some wait 90 days or more, while on 8lends a loan is treated as defaulted after 60 days of missed payments, which is when recovery is handed to the independent Collateral Agent.
Handling Early Warning Signs
Before a loan reaches the default stage, most platforms take proactive steps such as:
- Payment Reminders: Borrowers receive automated and manual reminders, emails, texts, or app notifications once a payment is missed.
- Grace Periods: Many platforms offer a grace period where the borrower can pay without penalty.
- Re-negotiation Attempts: Some platforms may reach out to discuss restructuring or repayment plans, especially if the credit holder established a reputable track record.
During this period, they gain the opportunity to redeem themselves and propose alternative arrangements.
How Recovery Works
When a default declaration is posted on the app, it triggers the recovery protocol, which usually goes like so.
A. Collections Process
Once they fail to respond or resolve the delinquency, the app initiates in-house recovery measures or passes the case to an outside debt collection agency, like a bloodhound to sniff out that defaulter.
Collectors are responsible for:
- Contacting the party.
- Attempting to negotiate a settlement or repayment plan.
- Sending reports to the bureaus.
In some cases, borrowers become responsive during this phase and begin repaying either partially or in full.
B. Legal Action
If the collection process doesn’t yield results, the app can entertain legal proceedings, which is mostly common for large loan amounts or repeat defaulters. Lawsuits may involve securing a judgment to garnish wages or seize assets, as well as seeking repayment through collateral if any was involved.
This process is time-consuming and costly, which is why many platforms only take this route in high-value defaults.
Not The Return You Expected
As recovery efforts are underway and hopes are held up for a good outcome, that begs the question of what the creditor deals with and how they are affected by such defaults. Here is what a P2P default on P2P means for creditors.
No More Regular Returns
Monthly payments from the borrower stop, that’s a no-brainer, and the expected interest payments cease along with it. This affects cash flow and projected investment returns.
Updates from the Platform
While the whole situation might be unpleasant, one silver lining in that cloud is that the lender is not kept in the dark, confused as to how they will get their money back. Platforms usually provide a dashboard or loan status tracker showing updates like:
- Late payment
- In collections
- Partial recovery
- Write-off
Potential Recovery
The situation is not completely hopeless because some amount of your money may still be recovered. This, however, depends on numerous contingencies, chief among them the measures for recovery put in place by the app. A lot of apps report recovery rates between 20-80% based on the loan type and recovery procedure.
Not all platforms are created equal when it comes to handling risk. 8lends is operated by Alpha Systems LLC (Saint Vincent and the Grenadines), a virtual asset service provider supervised by the FSA SVG, while collateral is held by an independent Collateral Agent, Maclear AG (Basel, Switzerland), supervised by PolyReg SRO. The platform combines a 40+ criteria borrower assessment, collateral-backed loans and a defined recovery procedure that starts after 60 days of missed payments. 8lends charges investors no commission and secures every loan with real-world collateral, but it does not insure capital and does not guarantee returns: recovery depends on the value the collateral realises.
The End Of The Road
When all measures fail though, and the money isn’t recoverable, the apps eventually write it off as a bad loan. In other words, they officially recognize it as uncollectible. For creditors, that means you lose. Essentially, the money is removed from your account and marked as a capital loss.
In some countries, loan losses may be claimed as capital losses or bad debts in taxes. Apps often issue tax statements at the end of the year, indicating which loans were written off. Write-offs are the worst possible outcome, and while these hurt, such risks are part of the game that comes with such investment.
A Lender’s Guide To Managing Risk
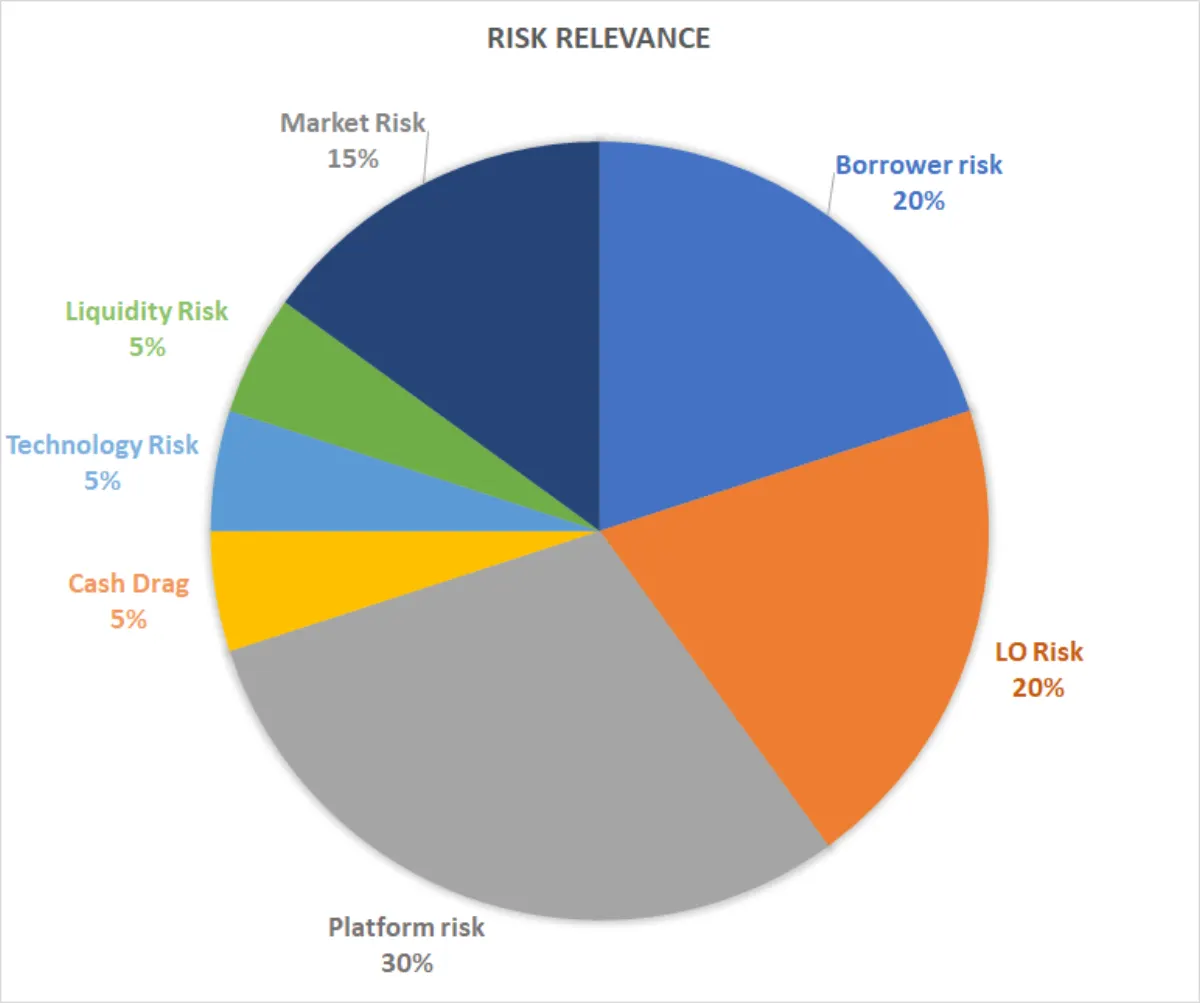
After pondering all these circumstances, when it comes to issuing P2P credit, here are some proven strategies for mitigating default losses and possibilities, foolproof means to secure your money.
- Spread out money among credit and applicant types. In classic terms, do not put all your eggs in one basket.
- Study applicants’ backgrounds, their ratings, and past transactions before lending.
- Opt for apps with active collection policies and transparent reporting. We will analyse this a little more later on.
- Don’t invest more than you can afford to lose.
- Re-invest returns into a mix of low and medium-risk loans.
Numbers Don’t Lie
Consider the track record of platforms before choosing one.
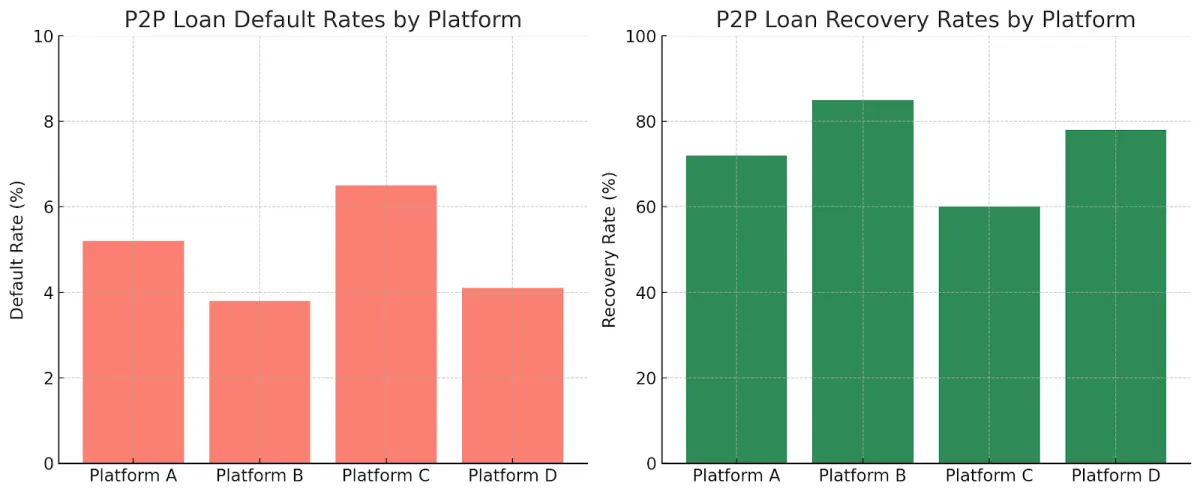
Published industry estimates put P2P default rates roughly between 3.8% and 6.5%, depending on how the borrower screening process and loan structure go. From a brighter perspective, recovery rates can reach up to 85%, though some outfits recover a paltry 60%, especially in unsecured loan cases.
Platform B has a low default rate (3.8%) and a high recovery rate (85%), suggesting strong borrower screening and aggressive follow-up. In contrast, Platform C sees more frequent ones and weaker collections, often due to a lack of collateral or lax collection procedures.
Armed with the knowledge above, creditors can make shrewder choices.
How Platforms Minimize Defaults
Frequent gaffes like these undermine lender confidence, so having a platform with the necessary security measures and proactive procedures in place to handle them properly is the best way to make sure everyone involved ends up a winner. This is how platforms do that:
Screening
Applicants get vetted through credit checks, income statements, debt-to-income analysis, and bank account review usually. Only borrowers who meet certain criteria are approved.
Risk-Based Interest Sums
Those that are riskier have to pay a premium.
Loan Diversification Tools
Most platforms encourage lenders to spread funds across many loans (e.g. N5,000 across 100 borrowers instead of N500,000 to one). This cushions any borrower who fails to repay their debt.
Collateral that could be physical assets like cars or houses or even savings and investments.
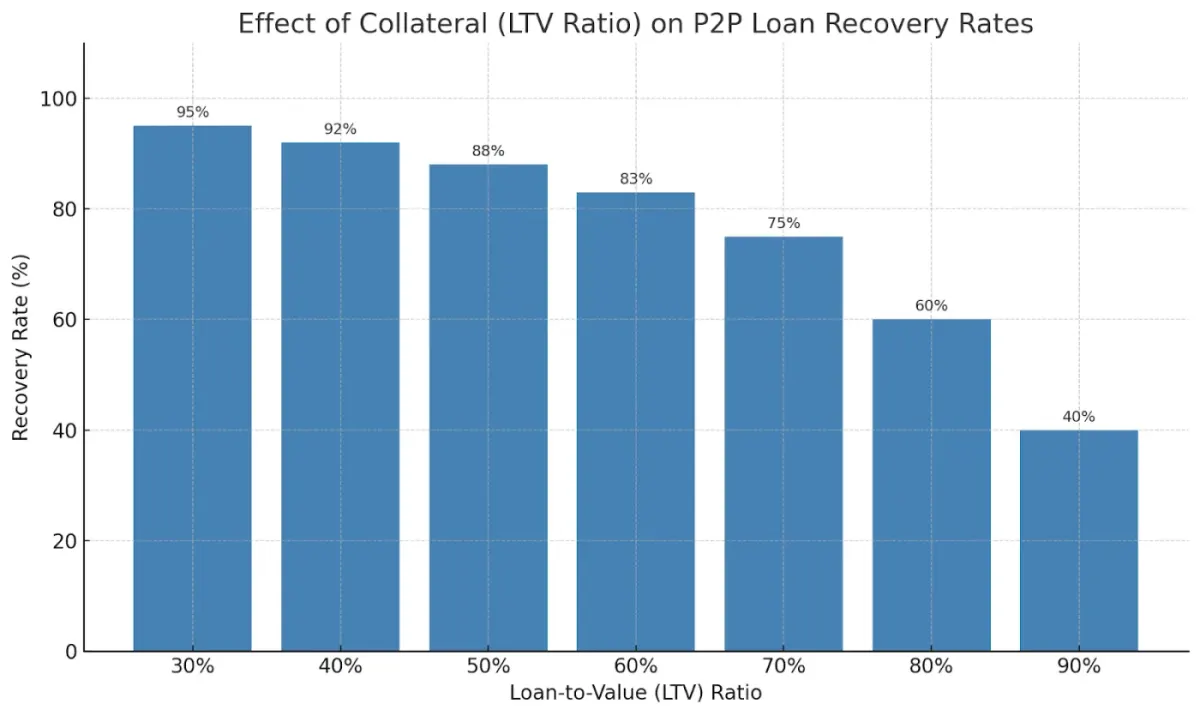
This chart illustrates how collateral enhances P2P loan recovery.
When a loan is secured with real-world assets, the platform can legally reclaim and liquidate the collateral in the event of default. LTV ratios typically hover around 60%, protecting lenders even in the case of moderate market fluctuations. The chart shows that recovery likelihood remains high until asset values decline beyond the LTV cushion.
Managing Risk, Maximizing Return
Defaults in P2P lending are inevitable, so it is important to understand the recovery process. Recovery is not guaranteed, but it is often possible, especially on platforms that are well-regulated and proactive.
For borrowers, defaulting may mean damaged credit, persistent collection efforts, and legal trouble. For lenders, it means reassessing strategies, trusting the platform’s recovery system, and being patient through the process. In the end, P2P lending is not just about high returns; it is about balancing opportunity and risk and being prepared for every possible outcome.
Read next on 8lends
If you're looking for a crowdlending platform that takes risk seriously and treats your capital with the care it deserves, check out 8lends. You’ll join a community of smart investors funding real-world businesses with robust protections and powerful returns.
Read next



Do You Have Any Questions?
All questionsThe platform has been audited by CertiK and Cyberscope, and all transactions are publicly visible on the Base blockchain. Two companies with clear responsibilities stand behind the platform: CLEARCHAIN CORP operates the platform and is registered as a Money Services Business with FINTRAC (Canada), and Maclear AG conducts due diligence and monitors collateral. So the platform is well regulated, transparent and accountable
If the project has BuyBack, the partner buys the loan and returns 100% of the principal once it is overdue for 60 days or more. Without BuyBack, Maclear AG initiates the sale of the collateral, and the proceeds are distributed proportionally among investors. Since launch there have been no defaults
The platform is operated by CLEARCHAIN CORP, registered in Canada as a Money Services Business (MSB) and subject to mandatory AML/CFT compliance requirements under FINTRAC. Settlements are made in USD. The platform is not a CASP, so DAC8 requirements do not apply
Small and medium-sized businesses in developing regions do not have easy access to bank financing and are willing to pay higher rates than businesses in the EU or US
You can sell your position to another investor through the Secondary Market before the end of the loan term. With Fastlending there is no fixed term: the principal and accrued income can be withdrawn at any time
The minimum investment is 100 USD
Risk of non-payment by the business, risk of changes in the value of the collateral, risk of limited liquidity if there is no buyer on the Secondary Market, and technical risk associated with the smart contract
Investments from 100 to 500 USD are available without KYC. For amounts over 500 USD, full verification is required: an identity document and proof of address