
How Borrower and Lender Feedback Loops Improve Platform Quality
September 11, 20255 min read
No matter how brilliant your lending platform is, it’s never going to be perfect right out of the gate. The best platforms aren’t built in a vacuum. They’re shaped and reshaped over time, based on the people who actually use them, thus, your borrowers and lenders.That’s where feedback loops come in. If you’re not familiar with the term, don’t worry. We’re gonna break it down, chat about why it matters, and show how creating strong, ongoing conversations between platforms and users can literally change the game for everyone involved. So grab a coffee, kick back, and let’s talk feedback.
First Off, What Is a Feedback Loop?
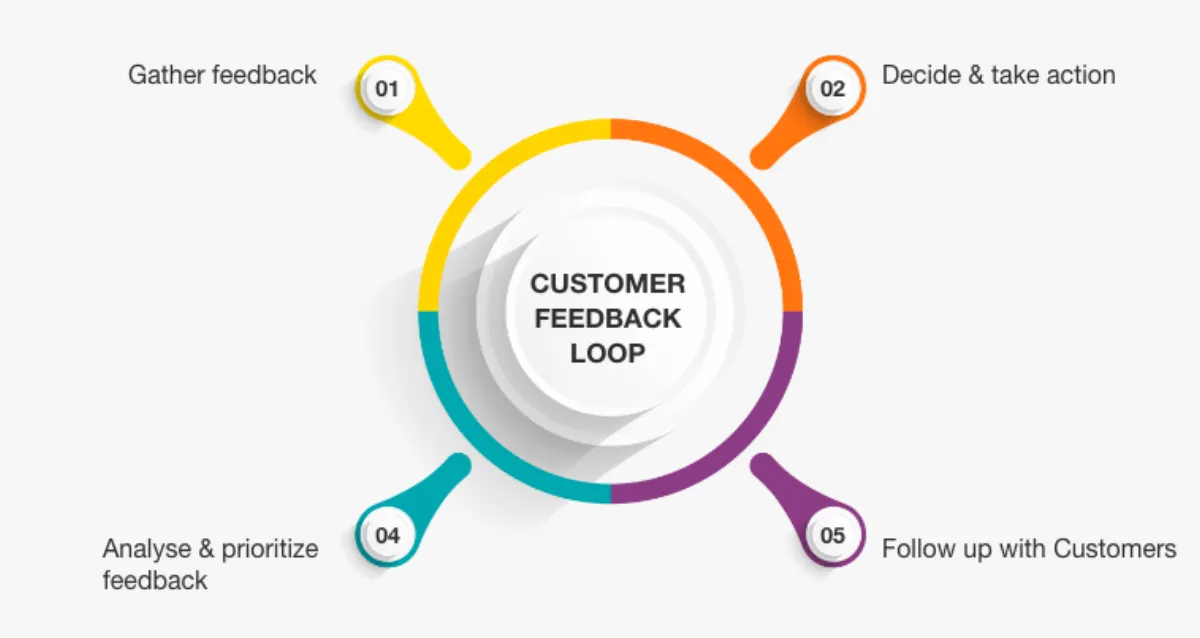
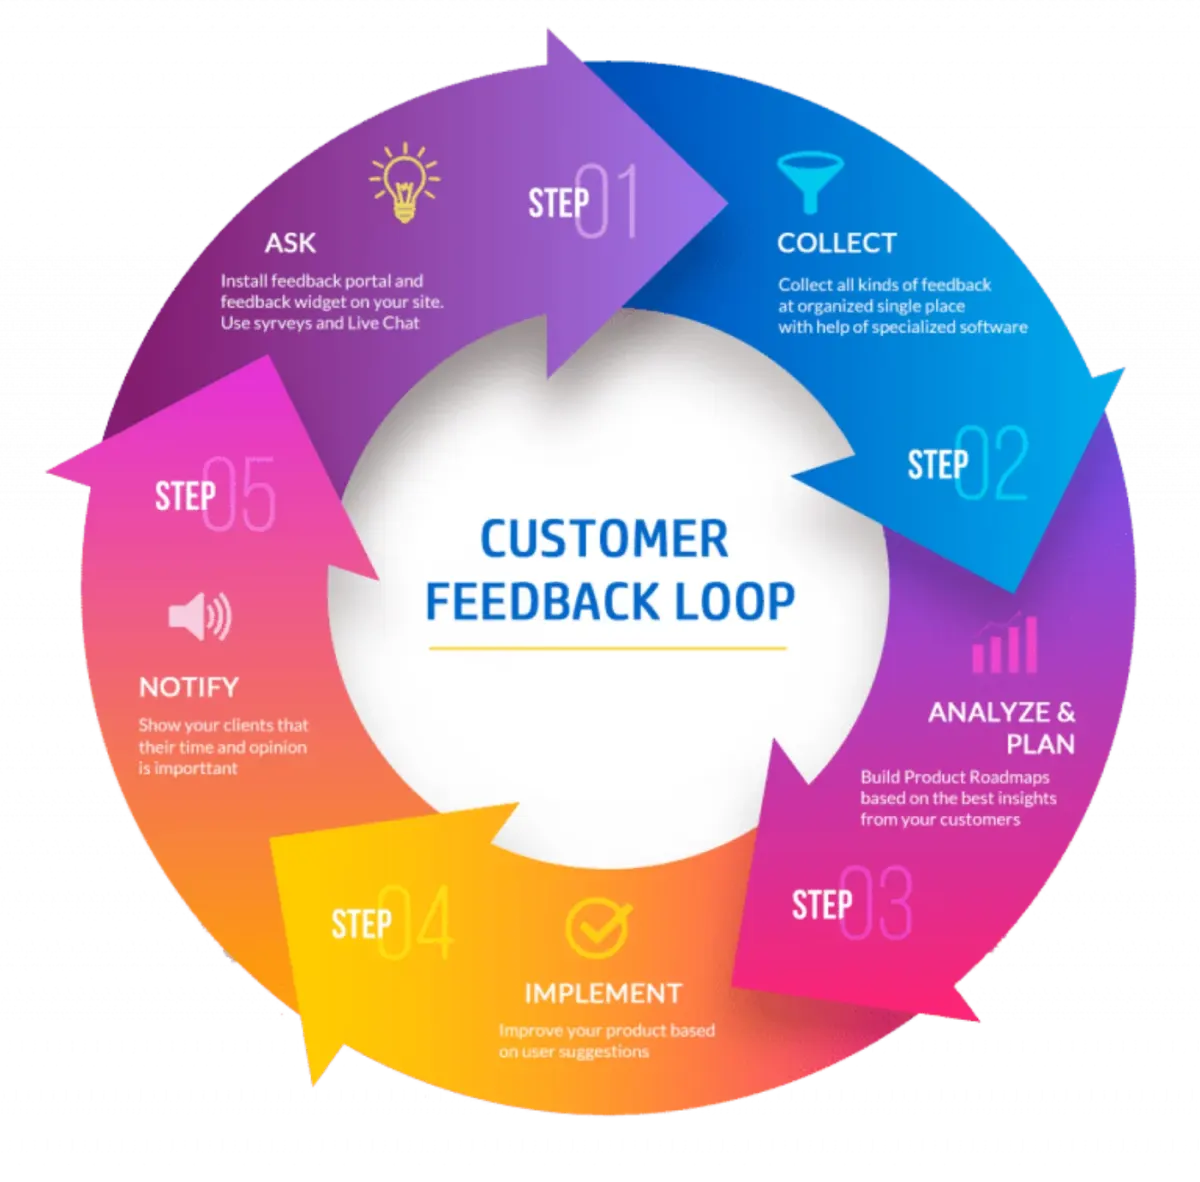
Think of a feedback loop like a conversation that never really ends. A borrower or lender uses your platform, they share their experience (the good, the bad, and the ugly), and then you take that information and use it to make things better. That improvement gets noticed, and the user feels heard. They trust you more. They give better feedback. And the loop keeps going.
In short:
Use → Feedback → Adjust → Repeat.
It sounds simple, but this little cycle can be the backbone of platform improvement. Without it, you're guessing. With it, you're building something people actually want to use.
One of the popular technologies people use today is crowdlending. They extend credit to people who are creditworthy yet would’ve had no access to it previously, as well as protecting lenders against defaults by providing collateral. One such platform is 8lends.
Why Feedback Loops Are Game-Changers
You might think feedback is just about fixing bugs or answering complaints. But it goes way deeper than that. Feedback loops help platforms to build trust, identify real pain points before they become a problem, create features people actually need, retain users, and spot trends in user behavior. In an industry where competition is fierce and trust is fragile, these things matter.
Borrowers: The Voice of the Everyday User
Let’s start with borrowers. These are your day-to-day users, the ones taking out loans, navigating repayment plans, and hopefully paying everything back on time.
When borrowers give feedback, they often highlight things like:
- Confusing language or loan terms
- Poor user experience during onboarding
- Issues with repayments or account visibility
- Lack of reminders or support options
- Frustration with customer service delays
Now here’s the rub: if even one borrower brings something up, there’s a good chance ten more are experiencing the same issue and just haven’t said anything. So don’t shrug off a complaint. See it as a clue. Also, borrowers are usually super honest. They’ll tell you when something is not working. They’ll also tell you what worked great. Both are gold.
Pro tip:
Add a short “Was this helpful?” button next to your key platform features or explanations. It’s a low-pressure way to gather insights fast.
Lenders: The Investors You Can’t Ignore
Lenders may not log in every day like borrowers, but when they do? Their feedback can be just as valuable. These are the people putting real money into your platform. If they feel like something’s off, or their returns aren’t lining up with expectations, they’ll either tell you, or quietly walk away.
Here’s what lenders tend to flag:
- Lack of transparency about borrower risk
- Delays in repayment or unexplained losses
- Difficult-to-understand reporting dashboards
- Poor communication during platform issues
- Concerns about default rates or platform stability
Platforms that listen and respond to lender concerns build stronger reputations in the investment space. And that means more capital flowing into your ecosystem. And let’s face it: you want both sides of the marketplace happy. If one side’s struggling, the whole thing wobbles.
Closing the Loop: What Happens After Feedback?
Okay, so let’s say you’re collecting feedback. Nice work. But what happens next? If the answer is “nothing,” then what’s the point?
Feedback without action is like asking someone how they feel and then ignoring their answer.
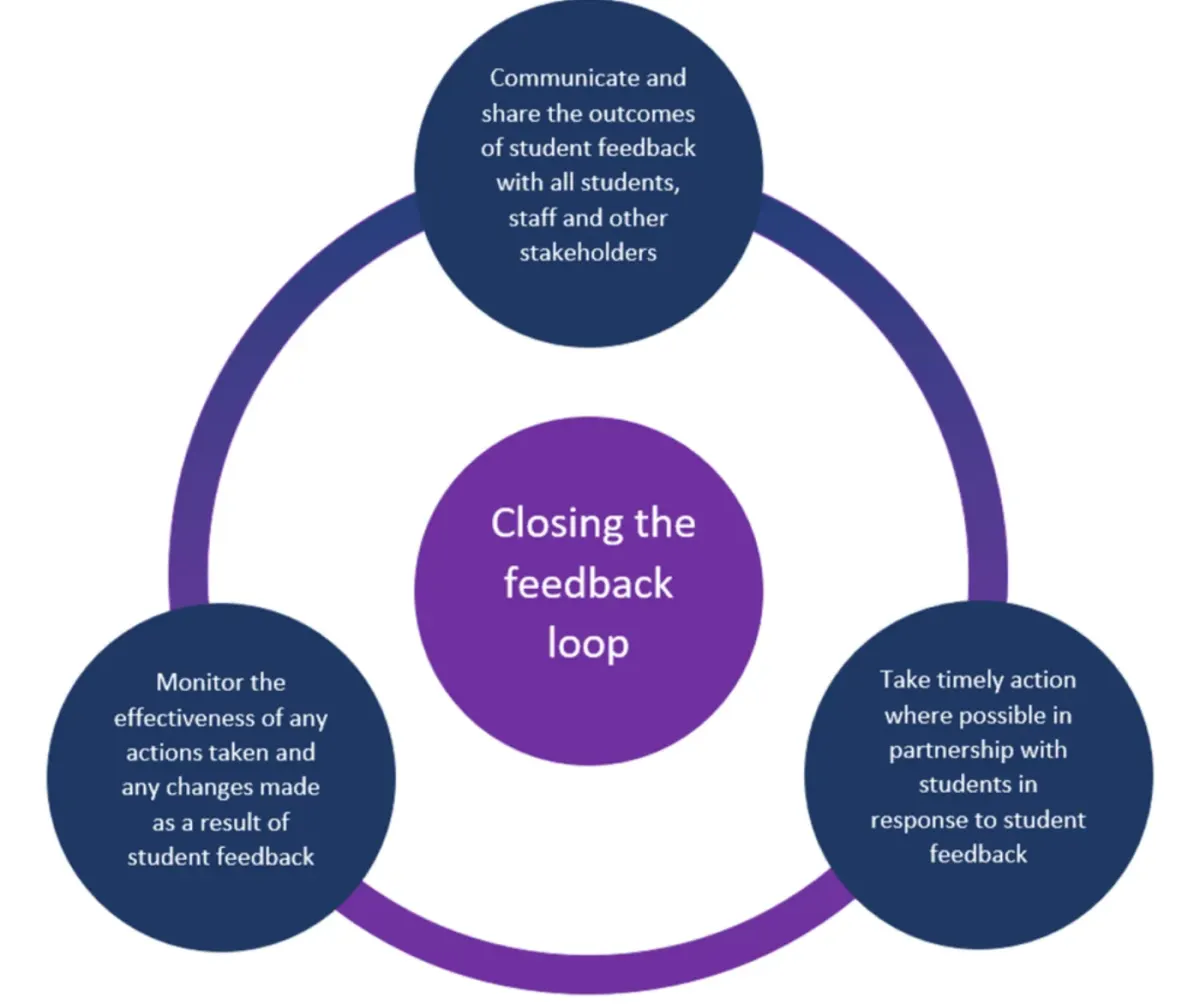
Here’s what good platforms do after they get feedback:
- Acknowledge it; Let the user know you heard them.
- Prioritize it; Not every request needs to be solved immediately, but at least categorize it.
- Act on it; When something’s clearly broken or annoying, fix it.
- Communicate improvements; This part’s huge. Let users know that their feedback made a difference.
That last one is where most platforms drop the ball. Don’t let that platform be you.
Real-World Example: A Tiny Tweak That Made a Huge Difference
There’s this mid-sized P2P lending platform, and for months they kept getting vague complaints about their repayment notifications. Nothing too dramatic, just people saying things like “I didn’t see it” or “I missed the reminder.” It turns out, the email subject lines were super generic, like “Monthly Update from Platform.” People were just ignoring them.
After digging through borrower feedback, the team changed the subject line to:
“Your Loan Payment is Due in 3 Days – Avoid Late Fees”
Open rates jumped. So did on-time payments. And the number of support tickets dropped by 23% the next month. Just from a single tweak.
That’s the power of listening.
Feedback as a Community Builder
One thing that often gets overlooked is how feedback loops create community.
When users see their ideas being implemented, or even just acknowledged, they start to feel like they’re part of something. They’re not just customers anymore. They’re contributors. Stakeholders. Partners.
Some platforms even run community polls or beta groups to test new features before launch. Not only does that produce better outcomes, but it makes your users feel valued.
It’s a lot harder to leave a platform that treats you like a partner than one that treats you like a number.
So, What Should You Be Doing Now?
If you’re not already building feedback loops into your platform, don’t stress. You can start small. Here are a few ideas:
Simple ways to collect feedback:
- Quick surveys after actions (e.g. “How was your loan application experience?”)
- Anonymous comment boxes inside the dashboard
- Monthly email asking users what can be improved
- Social media polls (you’d be surprised how well those work)
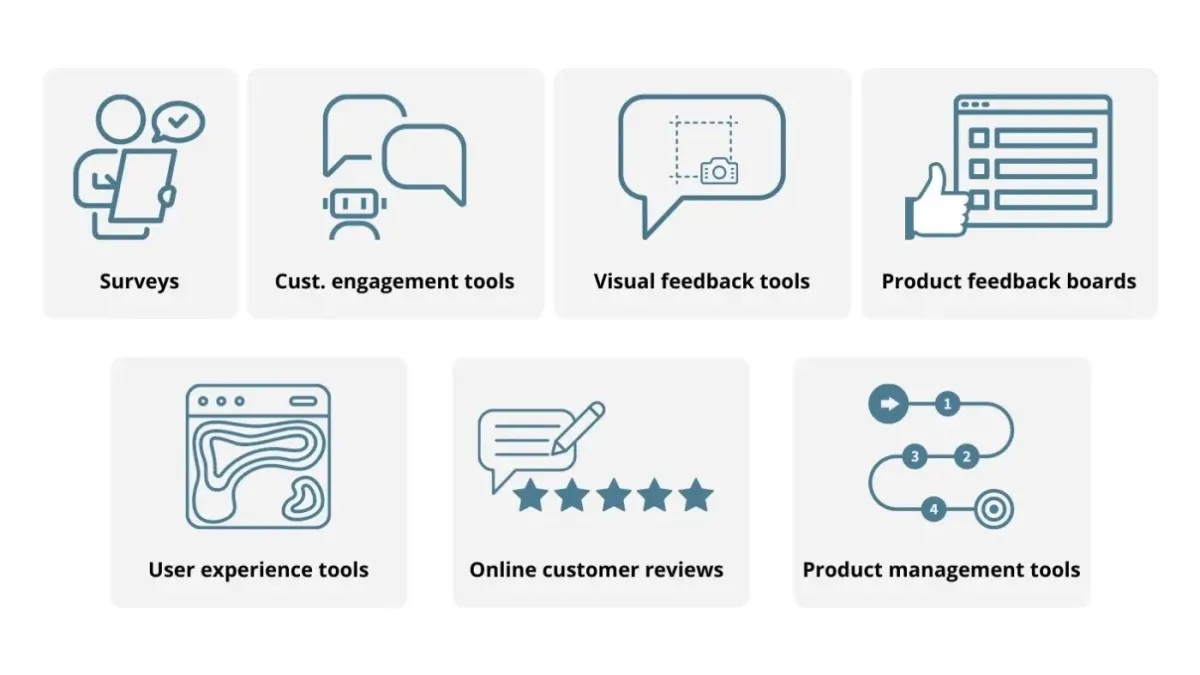
Tools that help:
- Typeform or Google Forms for surveys
- Intercom or Zendesk for tracking support feedback
- Productboard for managing feature requests
Feedback you should act on:
- Repeated complaints about the same issue
- Confusion around payments, timelines, or fees
- Suggestions for obvious improvements (like better navigation or clearer terms)
- And always, thank your users for their input. Even if you can’t act on it right away.
A Quick Note on Negative Feedback
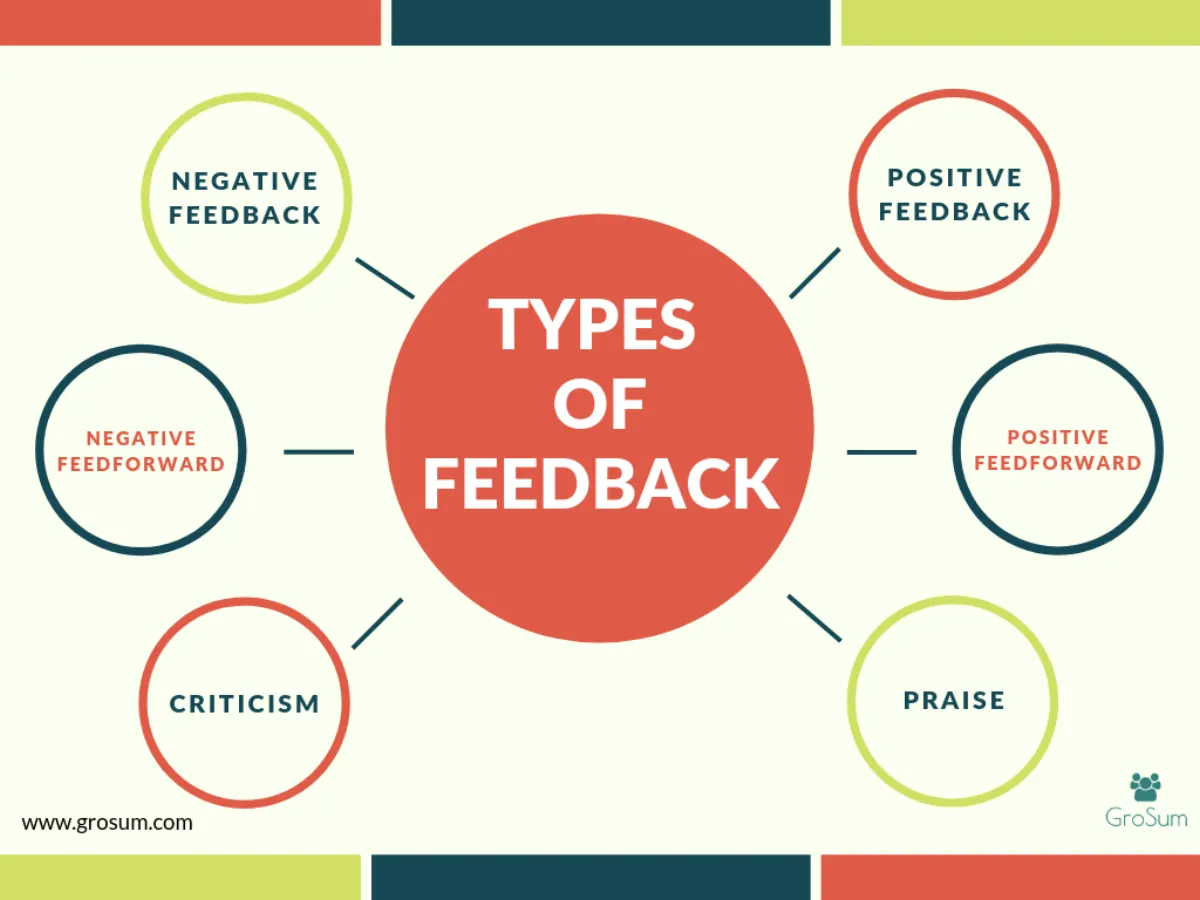
There is no denying that negative feedback stings. No one likes being told their platform isn’t living up to expectations. But it’s better than the alternative: silence. When users stop complaining, it usually means they’ve already checked out. If they’re still talking to you, they’re still hopeful. That’s your chance to turn things around.
Don’t take complaints personally. Take them seriously.
Final Thoughts
Borrowers and lenders are your best critics, your most loyal users, and your smartest advisors, if you let them be. Creating strong feedback loops isn’t just good customer service. It’s how great platforms are built and refined. When you listen, act, and close the loop, amazing things happen. Trust grows. Features improve. People stick around. And your platform becomes more than just a tool; it becomes a trusted part of someone’s financial journey.
So if you haven’t been taking borrower and lender feedback seriously, now’s the time to start. Open up the lines of communication, make it easy to speak up, and show people their voices matter. Because, at the end of the day, the platforms that succeed long-term are the ones built with their users, not just for them.
If you’re interested in uses a crowdlending platform with efficient communication, 8lends codes every detail of the transactions on the blockchain and establishes immediate channels for lenders and borrowers to easily interact while keeping risk to the minimum and opportunities to the maximum.
Read next on 8lends
Read next



Do You Have Any Questions?
All questionsThe platform has been audited by CertiK and Cyberscope, and all transactions are publicly visible on the Base blockchain. Two companies with clear responsibilities stand behind the platform: CLEARCHAIN CORP operates the platform and is registered as a Money Services Business with FINTRAC (Canada), and Maclear AG conducts due diligence and monitors collateral. So the platform is well regulated, transparent and accountable
If the project has BuyBack, the partner buys the loan and returns 100% of the principal once it is overdue for 60 days or more. Without BuyBack, Maclear AG initiates the sale of the collateral, and the proceeds are distributed proportionally among investors. Since launch there have been no defaults
The platform is operated by CLEARCHAIN CORP, registered in Canada as a Money Services Business (MSB) and subject to mandatory AML/CFT compliance requirements under FINTRAC. Settlements are made in USD. The platform is not a CASP, so DAC8 requirements do not apply
Small and medium-sized businesses in developing regions do not have easy access to bank financing and are willing to pay higher rates than businesses in the EU or US
You can sell your position to another investor through the Secondary Market before the end of the loan term. With Fastlending there is no fixed term: the principal and accrued income can be withdrawn at any time
The minimum investment is 100 USD
Risk of non-payment by the business, risk of changes in the value of the collateral, risk of limited liquidity if there is no buyer on the Secondary Market, and technical risk associated with the smart contract
Investments from 100 to 500 USD are available without KYC. For amounts over 500 USD, full verification is required: an identity document and proof of address