
Understanding Platform Risk: What If the P2P Company Fails?
September 23, 20255 min read
Individuals seeking greater returns, greater diversification, and direct exposure to buyers have flocked to peer-to-peer lending. But while borrower profiles and interest rates are often scrutinized by investors, there’s a more troubling risk that’s often ignored: platform risk, a fundamental risk.That is the risk that the P2P company you're using will fail, freeze withdrawals, or go bankrupt. And then your money could be stuck. You might be lucky enough to survive temporarily, but that does not eliminate the risk of permanent losses.As the P2P lending space matures and attracts a lot more customers, understanding what occurs if a platform fails is now not merely helpful, but vital to safeguarding your capital.In this article, we are going to discuss what platform risk is, what happens to your cash in case a platform shuts down, and also how to defend yourself from such disruption.
Why Platform Risk is Often Overlooked
Whenever individuals think about risk in peer-to-peer lending, they typically consider the borrower. What happens to the borrowers when they default on the loan? Do they have a good credit history? Those are good concerns. However, they are just part of the story. The platform is probably the biggest unaccounted-for risk in P2P lending.
Investors assume that a platform is running if it is safe. But sometimes that isn't so. A platform may be poorly managed, underfunded, or poorly overseen. And even borrowers making repayments might not save investors from losing access to their money if that platform fails.
Many retail investors skip this altogether. However, understanding platform risk is as important as evaluating a loan on a case-by-case basis.
Why Platform Risk Matters
P2P platforms facilitate the entire loan lifecycle by matching investors with borrowers. They:
- Vet and list borrowers
- Handle payments & repayment schedules
- Manage communication and collection
- Offer investor dashboards and updates
When this middleman collapses, things get messy. If a borrower continues to pay, who collects that payment anyway? Who makes sure it reaches you? Who handles disputes?
Without strong safety measures, your investment may be stranded, or even worse, completely lost.
What Happens if a P2P Platform Fails?
A platform failure does not necessarily mean your money is gone. However, recovering is complicated by many factors. These include:
Disrupted Loan Servicing
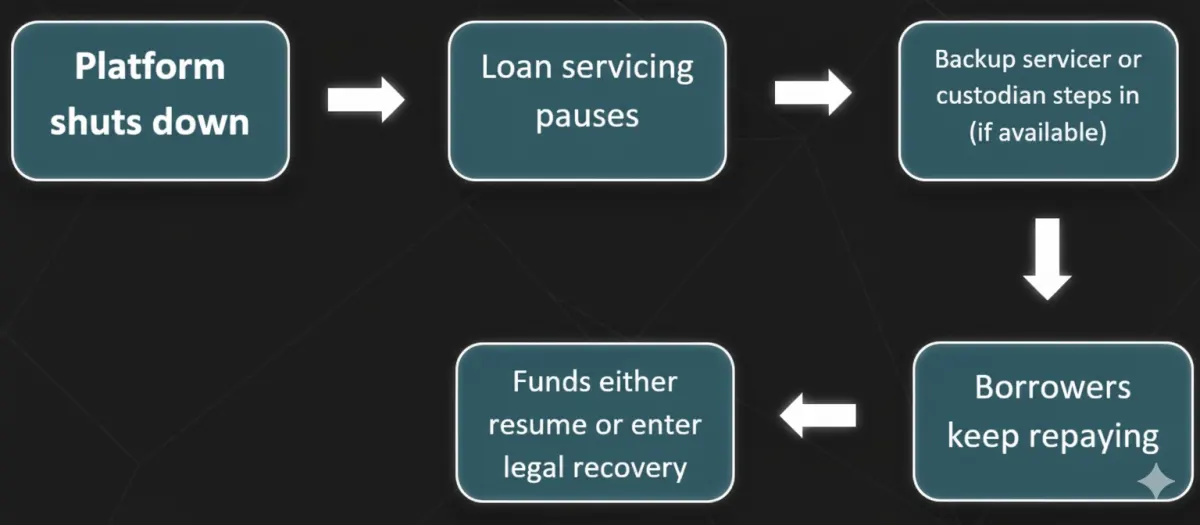
Backup servicers keep track of repayments and borrower communications if the platform fails. If the platform goes down and no backup servicer is available, payments from borrowers could stop. Communications would break down, and you may not receive your expected income.
Custodian Account / SPV
Reputable platforms often protect investor money through Custodian accounts / Special Purpose Vehicles (SPVs). This keeps investor funds separate and ensures they are less likely to disappear with the platform.
Activation of Backup Servicer
Some platforms have agreements with third-party servicers that can take over loan management when required. This may keep repayments up and limit losses.
Bankruptcy and Legal Process
Investors become unsecured creditors if the platform goes bankrupt. What this means is that you might get only a fraction of your money back. And even that may take months or years.
Real-World Examples of Platform Failure
Lendy (UK, 2019)
Lendy was once one of the top peer-to-peer lending platforms in the UK and yet things went wrong. The firm entered administration in 2019 after there was an increase in default rates and increased concern over poor transparency. The failure of the loans was worth more than 160 million pounds and years later there are still investors waiting to be paid back in full.
Grupeer (Latvia, 2020)
Grupeer, a P2P platform operating in Latvia, suffered platform failure; its sudden freezing of the withdrawals caught its users completely unexpectedly. It would be later realized that all the listed loans on the platform had some fake loans. Most investors sustained huge losses, especially with the lack of a straightforward plan of recovery and legal options. In most of the instances, the amount recovered was less than 20% of the original amount invested.
These examples demonstrate that a platform's power and regulation create a significant impact on whether investors retrieve funds or not.
8lends is a Swiss-based crowdlending company built with platform security and long-term investor protection at its core. With regulated operations, robust credit vetting, and transparent loan structuring through SPVs, 8lends offers not just strong returns – but peace of mind that your capital isn’t left exposed to platform chaos.
How To Know if a Platform is At Risk
Several signs can suggest trouble is coming.
| Red Flag | Why It Matters |
|---|---|
| Delayed interest payouts | May indicate liquidity problems |
| No recent audits published | Lack of transparency |
| Management turnover | Can signal internal instability |
| Poor communication | Often precedes operational shutdown |
| Withdrawal restrictions | A serious warning sign |
Red flags also include sudden shifts in strategy. For example, switching from low-risk consumer loans to high-risk digital assets without sufficient transparency. If you notice one or more of these, it's wise to consider exiting early.
Factors That Determine Recovery Success
Recovery depends on several technical and legal factors:
| Factor | Impact on Recovery |
|---|---|
| Custodian Account | Keeps investor funds separate from platform |
| SPV Loan Structure | Loans are easier to transfer and manage |
| Regulatory Oversight | Regulated platforms are more likely to have protocols |
| Jurisdiction | Strong legal frameworks help enforce recovery |
Visual Guide: What Happens When a Platform Collapses
Zopa’s Pandemic Response
Zopa, a regulated UK P2P platform established in 2005, ended the early 2020 market turmoil quite differently. Zopa implemented some protections and still operated despite investor withdrawals.
They froze new loan listings and capped withdrawals temporarily to maintain liquidity.
Weekly updates on portfolio and loan book performance were sent to investors. Zopa used its well-capitalised reserve and backup mechanisms to keep borrower repayments flowing.
Consequently, the platform did not collapse, and most investors continued to receive repayments. Zopa was transparent and prepared. And this proved to be pivotal in weathering a stressful period. This crisis-tested resilience bolstered Zopa's reputation and later helped it to gain traction as it transitioned to a fully licensed bank.
Risk Types
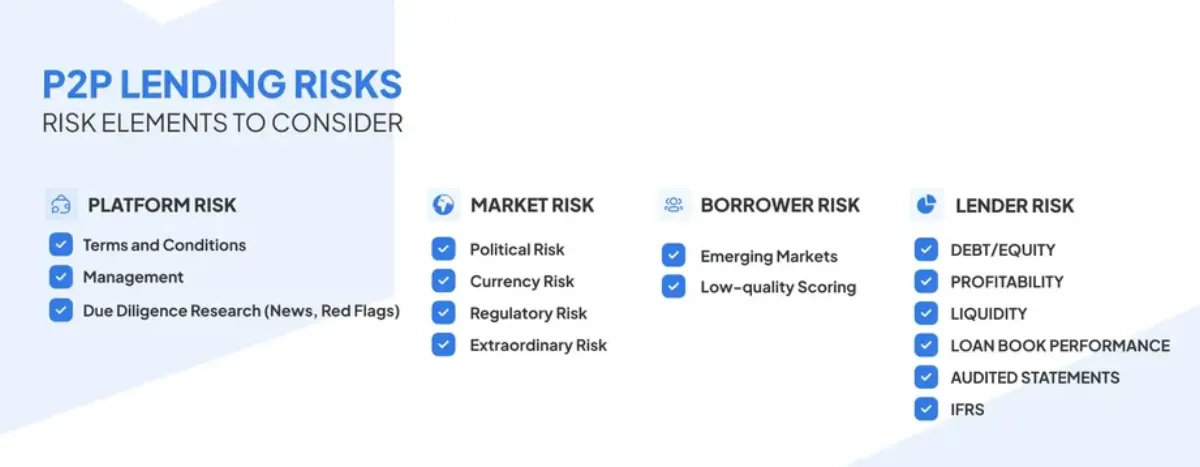
It’s important not to confuse platform failure with borrower default or other types.
| Type of Risk | Description | Can You Control It |
|---|---|---|
| Platform Risk | Platform collapses or goes bankrupt | Limited |
| Borrower Risk | Borrower misses payment | Medium |
| Currency Risk | FX losses on cross-border loans | Yes (Hedging) |
| Economy Risk | Recession causes widespread defaults | No |
Even if a borrower is paying on time, you won’t get your money unless there’s someone to process and pass on that payment.
Steps to Protect Yourself
Here’s what you can do:
- Confirm Custody Arrangements Verify that the platform uses separate accounts or custodians. Avoid platforms that jumble investor money with operating cash.
- Understand the Legal Setup Do loans under your name exist as SPVs or security? If so, they can be transferred more easily if there’s a collapse.
- Know Where It’s Regulated Licensed platforms are generally safer, for example, the UK's FCA. Other jurisdictions are more risky.
- Diversify Across Platforms Don’t put all your money on one platform. Consider 2-3 reliable ones, as they will reduce your risk tremendously.
- Monitor Platform Health Watch for delayed withdrawals, broken dashboards, or long silence. They are all early warnings of trouble.
- Keep Your Own Records Download contracts, payment schedules & communications. They might be crucial in legal proceedings.
Summary Table: Platform Risk at a Glance
| Risk Area | What it Means | What Can You Do? |
|---|---|---|
| No Custodian | Funds may disappear with the platform | Confirm use of third-party custodian |
| No SPV | Ownership of loans unclear | Ask how loans are legally structured |
| Weak Regulation | No protections during failure | Favour regulated platform |
| Single Platform Use | All eggs in one basket | Diversify your portfolio |
| Poor Transparency | Trouble can sneak up on you | Monitor platform communications and audits |
Final Thoughts
Platform risk isn't flashy, but it's real. It can be easy to get lost in interest rates and borrower profiles and not consider the platform itself as the glue holding everything together. The good news? You can minimize this risk by doing a little homework upfront: Pick regulated platforms, custodians & SPVs, lend across different asset classes, and be on the lookout.
Looking for a platform that takes your capital seriously? 8lends is redefining peer-to-peer lending with one of the most advanced risk-management frameworks in the industry. Whether you care about borrower quality, loan transparency, or long-term platform viability – 8lends delivers on every front.
Related on 8lends
Read next



Do You Have Any Questions?
All questionsThe platform has been audited by CertiK and Cyberscope, and all transactions are publicly visible on the Base blockchain. Two companies with clear responsibilities stand behind the platform: CLEARCHAIN CORP operates the platform and is registered as a Money Services Business with FINTRAC (Canada), and Maclear AG conducts due diligence and monitors collateral. So the platform is well regulated, transparent and accountable
If the project has BuyBack, the partner buys the loan and returns 100% of the principal once it is overdue for 60 days or more. Without BuyBack, Maclear AG initiates the sale of the collateral, and the proceeds are distributed proportionally among investors. Since launch there have been no defaults
The platform is operated by CLEARCHAIN CORP, registered in Canada as a Money Services Business (MSB) and subject to mandatory AML/CFT compliance requirements under FINTRAC. Settlements are made in USD. The platform is not a CASP, so DAC8 requirements do not apply
Small and medium-sized businesses in developing regions do not have easy access to bank financing and are willing to pay higher rates than businesses in the EU or US
You can sell your position to another investor through the Secondary Market before the end of the loan term. With Fastlending there is no fixed term: the principal and accrued income can be withdrawn at any time
The minimum investment is 100 USD
Risk of non-payment by the business, risk of changes in the value of the collateral, risk of limited liquidity if there is no buyer on the Secondary Market, and technical risk associated with the smart contract
Investments from 100 to 500 USD are available without KYC. For amounts over 500 USD, full verification is required: an identity document and proof of address