
2025年9月4日4 分钟阅读
P2P(点对点)借贷通过绕开银行等中介机构,改变了人们借款和放贷的方式。但它并不完美。当借款人无法偿还贷款时,出借人会蒙受损失,整个体系也会受到冲击。回顾那些出问题的贷款,能让我们看清它们失败的真正原因,并为所有参与者指明一条明智的前进道路。在这里,我们将深入探讨是什么让P2P贷款出问题,分享一些发人深省的案例,并归纳出实用的经验教训,帮助这个行业收紧风险管控,健康、持久地发展。
Understanding P2P Lending and Loan Defaults
P2P lending platforms like 8lends make borrowing easy by linking people who need cash with those ready to lend it based on credit checks. Even with clever systems, someone can still miss a payment or not pay back what they owe. This slip happens when borrowers skip interest or the main sum, and it feels risky. Both the borrower’s situation and how the site works play a part in figuring out what’s behind these misses.
Determinants of P2P Loan Defaults
Real-world studies show exactly why some peer-to-peer loans go south. A deep dive into data from 2008 through 2014 pulled out the top warning signs.
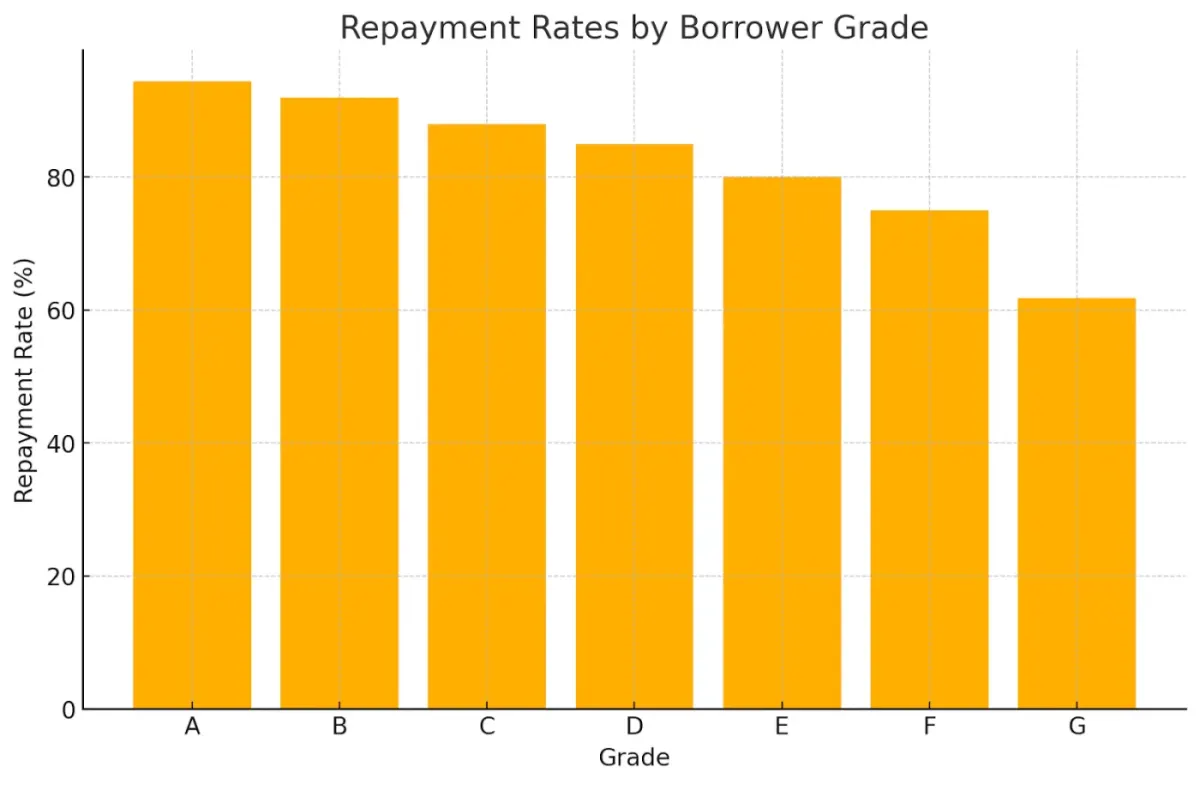
The table below lays out these factors to guide your understanding.
| Category | Determinants | Details/Findings | Exact Numbers/Stats |
|---|---|---|---|
| Borrower Assessment | Grade | Most predictive, A to G, A is safest. | 94.4% A-grade repaid, 61.8% G-grade. |
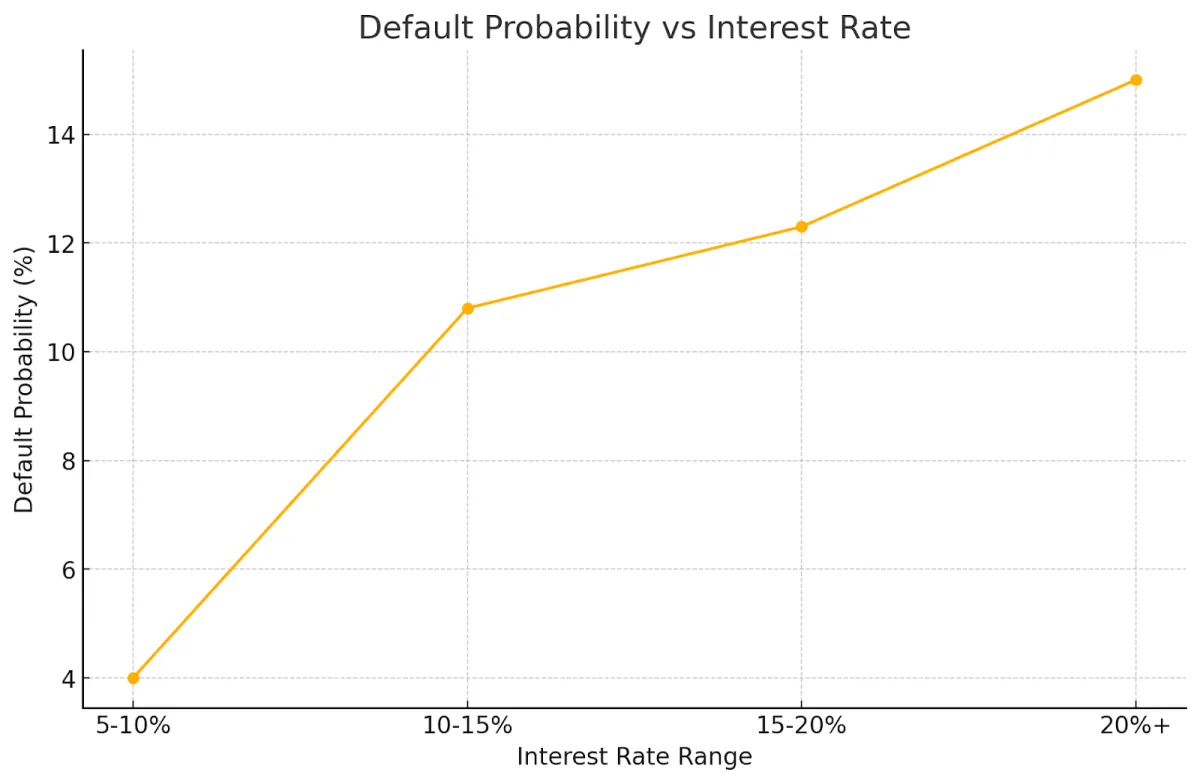
| Interest Rate | Higher rates correlate with higher default probability. | Defaulted: 12.3%, Non-defaulted: 10.8%, p<0.001. | |
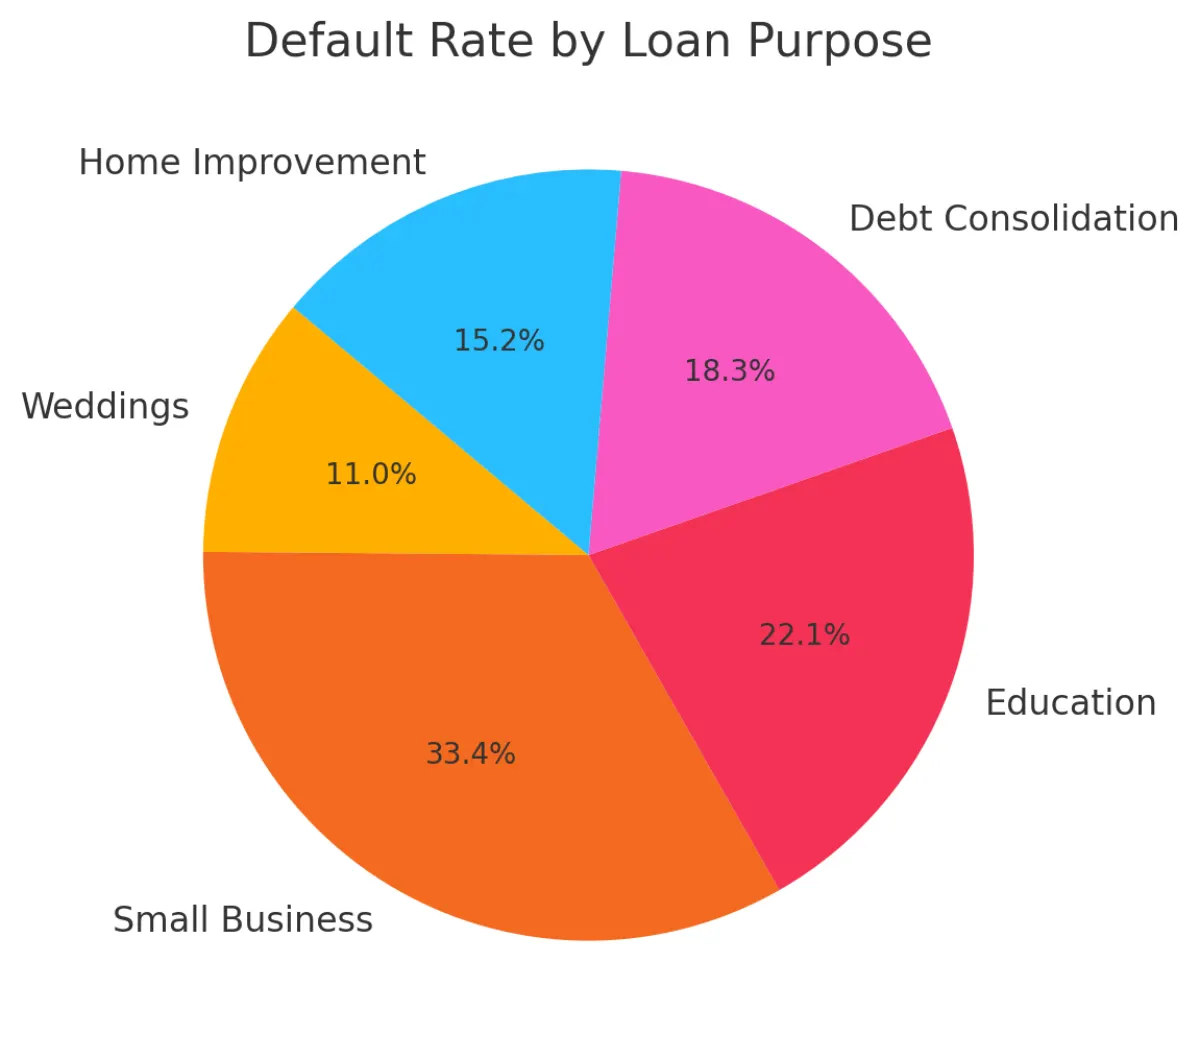
| Loan Characteristics | Loan Purpose | Weddings least risky (92.8%), and small businesses most risky (78.1%). | Significant for 10/14 purposes, p<0.001. |
| Loan Amount | Not significantly related to default. | T-test: -0.997, not significant. | |
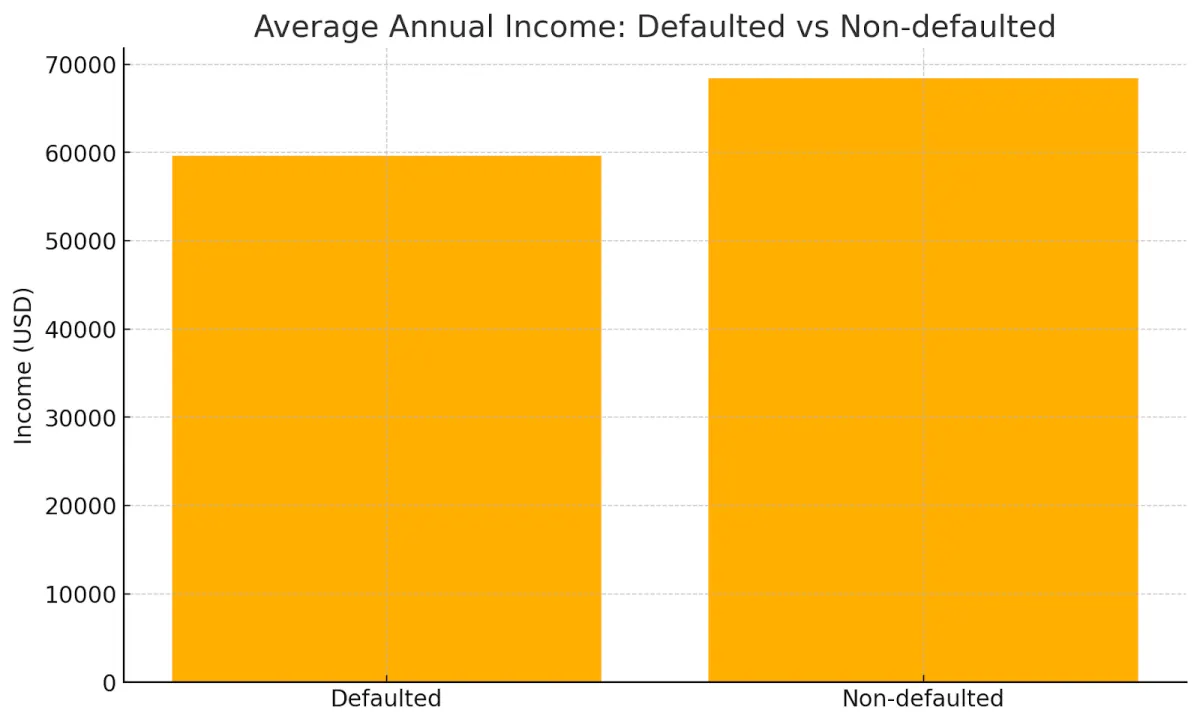
| Borrower Characteristics | Annual Income | Lower income is associated with higher default probability. | Defaulted: $59,595, Non-defaulted: $68,391, p<0.001. |
| Current Housing Situation | Mortgage/own is less risky than rent/other. | Mortgage: 90.1% repaid, Rent: 88.3%, p<0.001. | |
| Employment Length | Not significantly related to default. | Defaulted: 4.60 years, Non-defaulted: 4.68 years, p≥0.05. | |
| Credit History | Various metrics | All significant except Months Since Last Delinquency. | E.g., Delinquency 2 Years: Defaulted 0.18, Non-defaulted 0.14, p<0.001. |
| Borrower Indebtedness | Loan Amount to Income, Debt to Income | Higher ratios correlate with higher default probability. | E.g., Loan Amount to Income: Defaulted 0.183, Non-defaulted 0.163, p<0.001. |
This study showed a 10.9% default rate – 2,666 out of 24,449 loans – and makes it clear that who the borrower is (their income and past credit) and what the loan looks like (its size, term, interest) really matter. The mix of those personal traits and loan details can make or break repayment.
Digging into China’s P2P world adds more color. One look at Renrendai data found that people who passed quick checks like video calls or phone confirmations actually missed payments more often, while those who provided solid ID or asset proof cut their risk, and the models nailed it with over 90% accuracy, to predict defaults well.
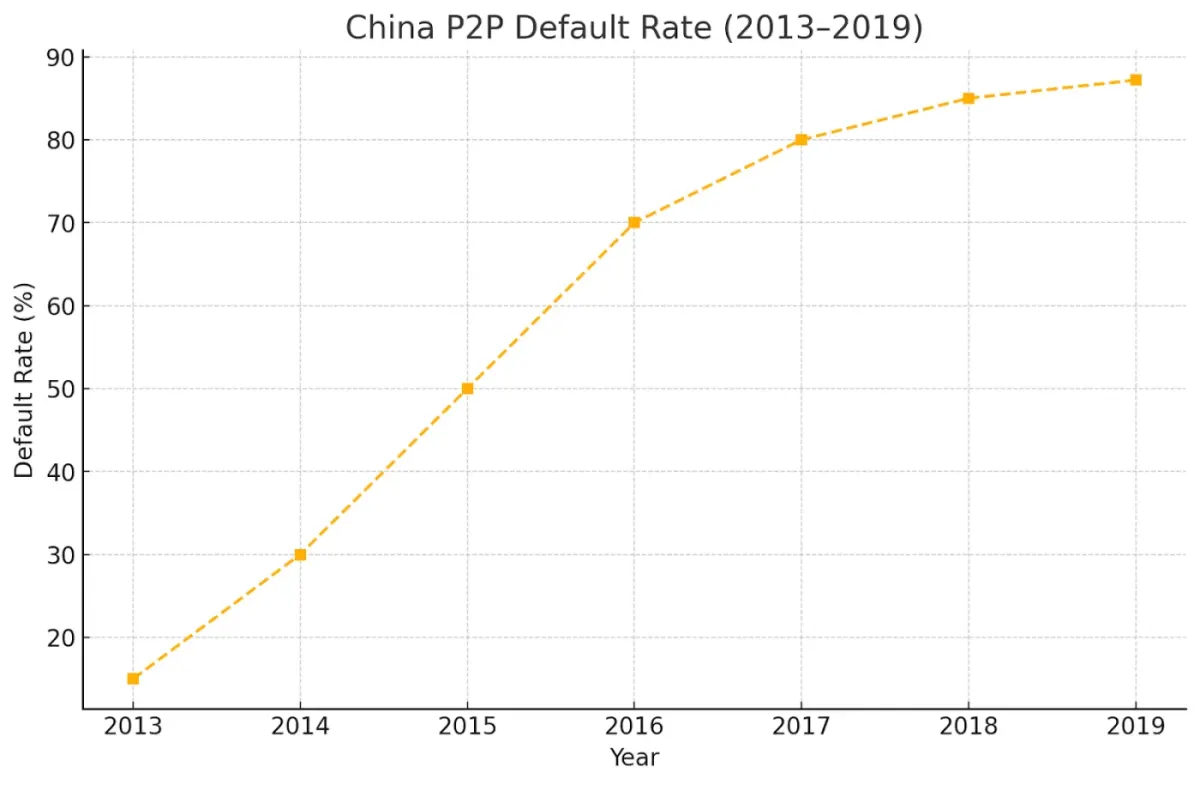
Then there’s the shocker: by 2019, defaults in China hit 87.2%. That sky-high rate got blamed on a poor match between borrowers and backers, investors flying blind on finance, and rules that just weren’t strong enough.
Case Studies: Notable Failures and Their Postmortems
Looking at real-life cases of P2P lending failures helps uncover deep-rooted problems in the system. Take China’s P2P crisis, which hit its worst point in 2015. Out of around 3,500 platforms, two-thirds collapsed. Many failed because of scams, fake investment schemes, or acting like illegal banking operations.
Regulators couldn’t keep up, with just a handful of staff trying to monitor thousands of platforms, so things spiraled out of control. Close ties between platforms and local governments often meant loans went to risky ventures. When officials started warning investors, panic spread. By July 2018, active investors dropped by a fifth, and total loans plunged from over 1.3 trillion yuan to below 1 trillion.
LendingClub in the U.S. had its own troubles. For a time, they limited transparency around loan details during their “Quiet Period,” and their CEO was caught altering data. These moves made investors uneasy, adding to the sense of risk.
In China, Renrendai faced similar challenges. Weak regulations, high rates of defaults, and sudden cash shortages exposed flaws unique to the platform. Each story shows how fragile these systems can be, especially when rules aren’t clear or risks aren’t managed with care.
Lessons Learned from Failure Postmortems
Looking at past mistakes teaches us valuable lessons for building better systems. Here’s what we’ve learned:
- Being Open Matters: When platforms don’t share clear, updated details about their work, people stop trusting them. Take GraduRates or Encash—both shut down quietly, leaving lenders confused. Sharing honest, timely updates helps everyone stay informed and confident.
- Rules Aren’t Optional: Ignoring guidelines can lead to big problems. In China, weak oversight allowed fraud and risky behavior to spiral. Sticking to regulations, like India’s RBI rules, keeps platforms legally safe and protects everyone involved.
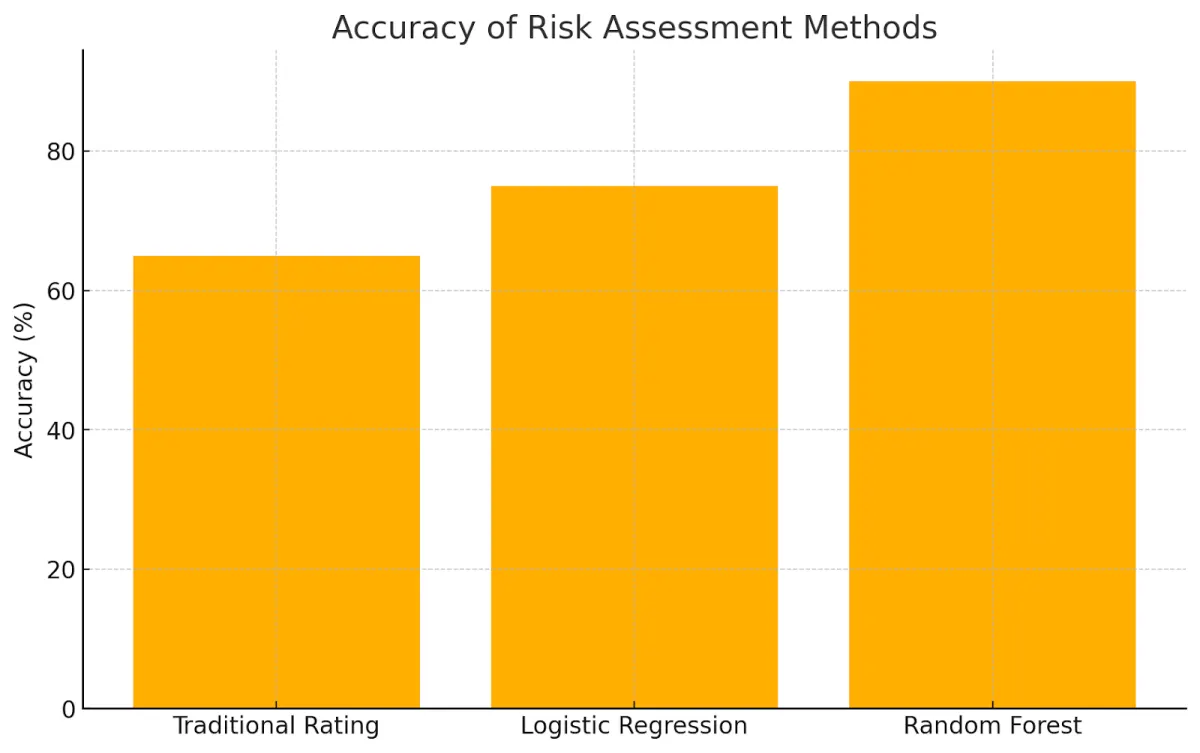
- Smarter Risk Checks: New tools are changing how risks are spotted. Research shows methods like Random Forest (a type of machine learning) work better than old-school systems. Even small details, like how borrowers describe themselves or their connections, help predict who might struggle to repay.
- Spread Out, Stay Safe: Putting all funds into one loan is risky. Platforms like Prosper learned this the hard way when defaults hurt their lenders. Splitting investments across many loans softens the blow if one fails.
- Keep Growing, Keep Learning: Success isn’t static. Platforms like LendingClub built trust by openly sharing data and teaching users. Others tweak their systems using lessons from past errors. Over time, these steps create stronger, more reliable systems.
By focusing on these areas, platforms can build safer, more trustworthy spaces for everyone. Small changes, when done thoughtfully, add up to big improvements.
Advancements in Risk Management Practices
Looking back at past experiences has sparked new ideas in managing financial risks. Platforms now use things like social information or community activity to assess creditworthiness more accurately, so that lending decisions better reflect real-life situations.
Advanced techniques, like machine learning and survival analysis, often work better than traditional platform ratings, uncovering hidden chances for smarter investments while encouraging fairer rates for borrowers.
Tools like SHAP help explain how these complex models make choices, shining a light on familiar risks as well as unexpected ones that might otherwise go unnoticed. Some systems even analyze relationships between borrowers, like shared connections or networks, to spot patterns that improve predictions.
Together, these steps lower the chance of loans going unpaid, which helps investment portfolios grow steadier over time and keeps platforms running smoothly for the long haul. By blending technology with deeper insights into human behavior, the whole process becomes both safer and more balanced for everyone involved.
Conclusion
Looking back at why P2P loans flop shows how the borrower, the platform, and the rules all mix. We need to learn from each flop so that we keep things clear, check risks well, and follow the rules. We can keep getting better with smarter data tools and by spreading out our bets. That way, P2P lending can stick around as a solid choice alongside regular banks.
8lends backs up lender investments using borrower collateral. This significantly adds to the security of their loans, even if risk can never be completely eliminated. Opportunities meanwhile abound with 0% commission charged to investors and over 15% returns.
接着读
有任何疑问吗?
全部问题平台已通过 CertiK 和 Cyberscope 审计,所有交易在 Base 区块链上公开可查。平台背后是两家职责清晰的公司:CLEARCHAIN CORP 负责平台运营,并在加拿大以 Money Services Business 身份在 FINTRAC 注册;Maclear AG 负责尽调与抵押物监管。平台受到良好监管,公开透明且责任清晰
若项目带有 BuyBack,逾期满 60 天后合作方将买断贷款并返还 100% 本金。若无 BuyBack,Maclear AG 将启动抵押物出售,所得按比例分配给投资者。平台上线以来从未发生违约
平台由 CLEARCHAIN CORP 运营,其在加拿大注册为 Money Services Business(MSB),并须在 FINTRAC 下履行强制性 AML/CFT 合规要求。结算以 USD 进行。平台并非 CASP,因此 DAC8 要求不适用
发展中地区的中小企业难以获得银行融资,愿意支付比欧盟或美国企业更高的利率
到期前可在二级市场将头寸卖给其他投资者。Fastlending 没有固定期限:本金和收益随时可提取
最低投资额为 100 USD
企业不还款的风险、抵押物价值波动的风险、二级市场无买家时的流动性受限风险,以及智能合约相关的技术风险
100 至 500 USD 的投资无需 KYC。超过 500 USD 需完成完整认证:身份证件和地址证明