
ブロックチェーンレンディング用語解説:APY、TVL、担保比率ほか
2025年6月3日5 分で読めます
分散型金融は、ブロックチェーン技術を用いて人々のお金の扱い方を変えました。誰でも使え、その動きを誰でも見られる仕組みを作り出しています。プロトコル型のレンディングでは、銀行を介さずにデジタル資産を貸し借りします。手続き全体はブロックチェーンに組み込まれた自動契約の上で動きます。これにより金融サービスは利用しやすくなり、資金の行き先が正確に見え、従来の選択肢より高い収益の可能性が生まれることも少なくありません。APY、TVL、担保比率といった用語を知っておけば、想定外の事態を避けられます。本稿では各用語の意味、なぜ重要なのか、そしてプロトコル型レンディングの利用者にとって何を意味するのかを説明します。
The Basics
ブロックチェーンレンディングとは、自動で稼働するプラットフォーム上でデジタル資産を貸し借りすることを指します。保有するデジタル資産をプールに預けて利息を得ることもできますし、一部を担保として預け入れて別のデジタル資産を利用することもできます。
このシステム全体は仲介者なしで動くため、ブロックチェーン上で相手と直接取引します。スマートコントラクトがすべての詳細を処理し、ローンのルールは自動で実行されます。貸し手は利息を得られ、借り手は保有するデジタル資産を売却せずに資金を手にできます。デジタル資産の価格は短期間で大きく変動しやすいため、一定のリスクを伴います。
Annual Percentage Yield (APY)
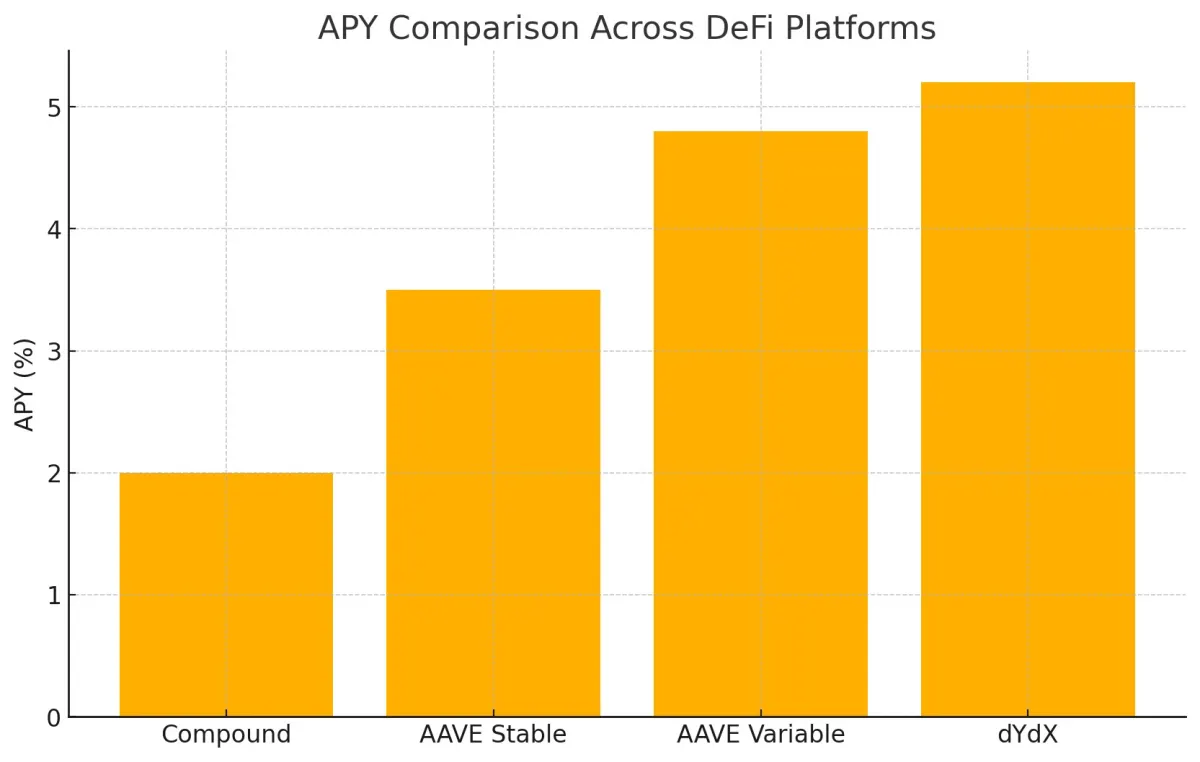
Annual percentage yield shows the yearly return on an investment, taking into account compound interest. In such P2P loans, it tells you how much interest you earn on assets you lend, or how much you have to pay when you borrow. Unlike banks, where charges stay the same for a set time, platforms often change APYs as users come and go.
Knowing APY helps you see possible gains or costs. A higher APY means better returns, so these types of loans are often seen as appealing when bank rates are low. These charges shift all the time because smart contracts adjust them to balance supply and demand. Some platforms calculate interest every few seconds on chains like Ethereum. You might even pick a “stable” APY on crowdlending sites such as 8lends, which stays the same for a while if you want predictability.
There is a trade-off. Higher APYs could yield higher rewards, but they also bring more risk. Smart contracts have weaknesses too. Markets may swing up and down. So it is wise to keep an eye on both the figures and the health of the platform you choose.
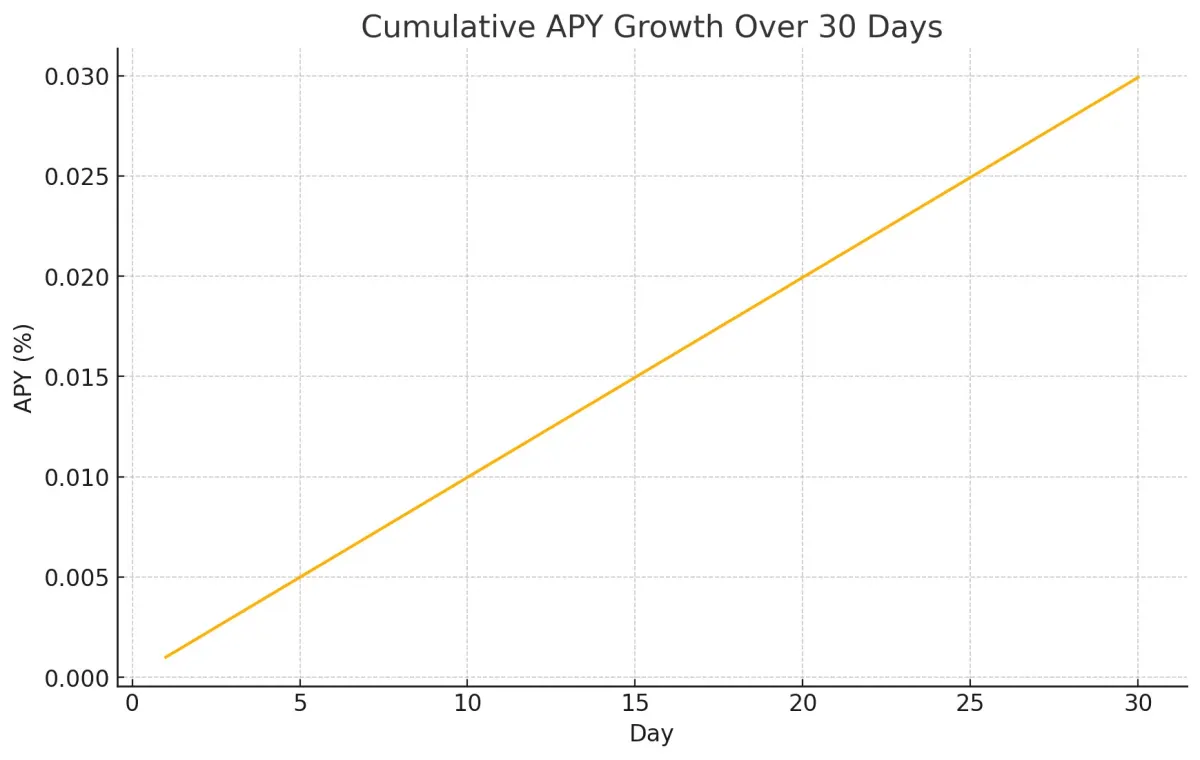
Here’s a quick example based on Compound Finance. If the cETH to ETH course grows by 0.0000000003 each block, and about five blocks happen every minute, your supply APY for a month will work out to roughly 2.005%.
On a 10 Ethereum deposit, that means about 0.2592 Ethereum in interest over thirty days. Frequent compounding like this might boost your earnings, but it also means you need to watch things closely.
Total Value Locked (TVL)
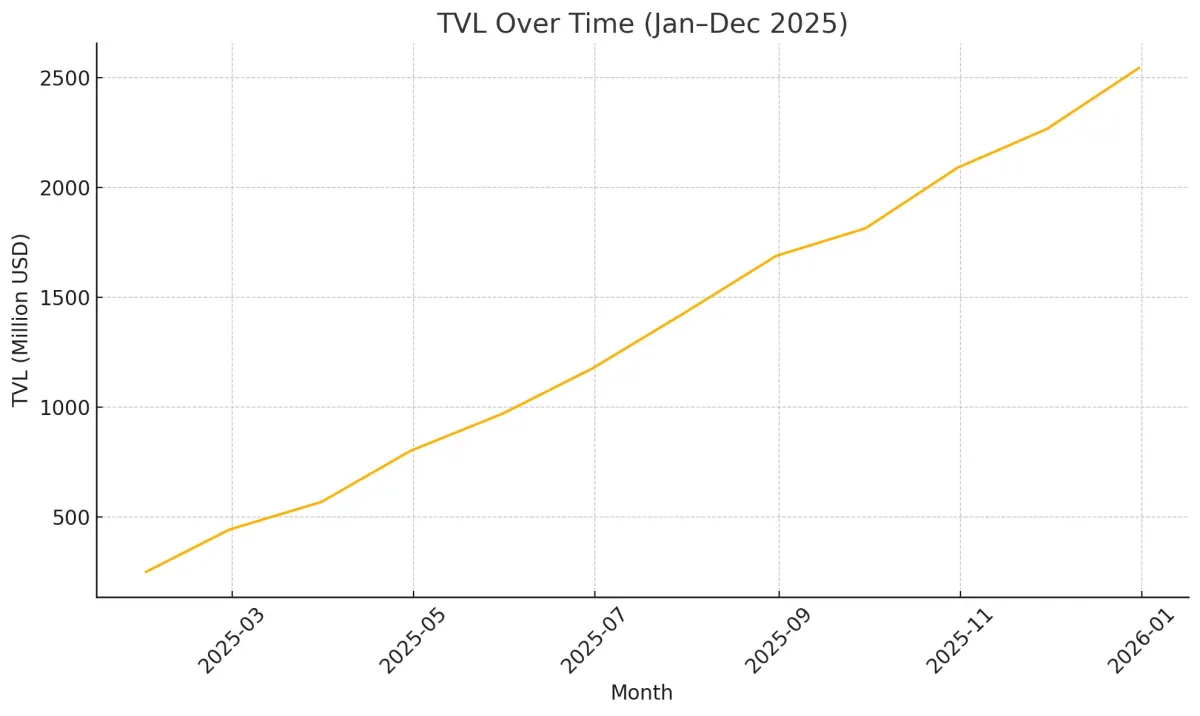
Total Value Lockedは、ある時点でブロックチェーンレンディングプロトコルにどれだけの資金が預けられているかを示します。通常は米ドル建て、またはEthereumプロジェクトにおけるETHのように、そのプロトコル独自のデジタル資産で計算されます。レンディングプールにおけるTVLは、貸し手がそれらのプールに預け入れた資金の総額を意味します。
TVL matters because it tells us how popular and liquid a protocol is. More TVL means more money is up for borrowing, so trades might happen more smoothly and the interest may stay steadier. It also shows that people trust the protocol and use it, making it easy to compare different projects. TVL tends to jump around with market ups and downs, and it only measures what is locked in, not the earnings generated from it.
Imagine someone puts $1,000 worth of Ethereum into a protocol. Another user then takes up $500, backed by that deposit. The TVL here becomes $1,500, counting both what is deposited and what is used. Investors watch this number closely, using it to decide if a protocol, like MakerDAO or Compound, looks ahead to a bright future. So TVL gives a clear snapshot of a project’s health and size at any time.
Collateral Ratio
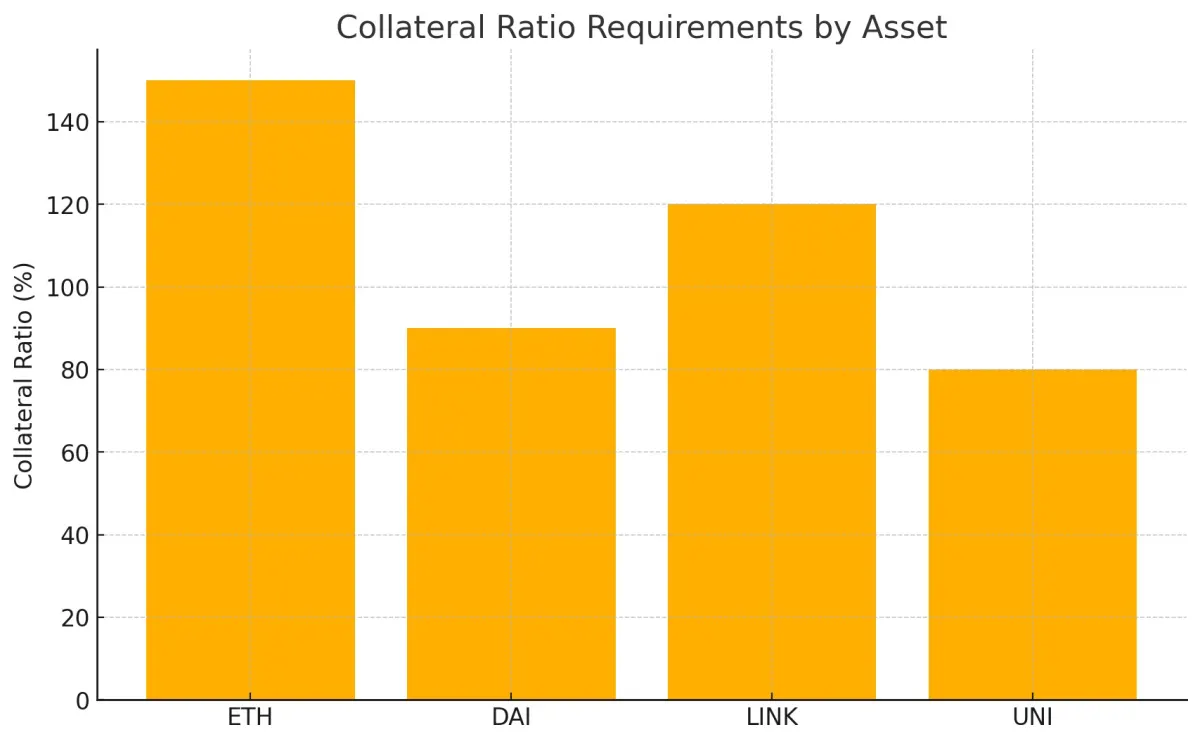
This shows how much value you lock up compared with the loan you take out. In these loans, you usually need to lock up more value than you borrow. This extra cushion guards against sudden price swings. For instance, MakerDAO asks you to lock up $150 worth of Ethereum to use $100 in DAI. That works out to a 150% ratio.
保有するEthereumの価値がその水準を下回ると、ローンは清算される可能性があります。これにより貸し手は保護されます。資産ごとに独自の上限が設定されています。リスクの高いデジタル資産では担保率が50%までしか認められない場合もあります。デジタルドルでは90%まで認められることもあります。
Let’s say you lock up $150 in Ethereum and take up $100 in DAI. If ETH’s price drops so that your security backing falls below $150, your position will face liquidation, and you’ll lose a bit extra as a penalty. This system protects lenders but could also cost borrowers. Keeping an eye on your collateral ratio is big.
Utilization Ratio
This measures how much of the total supply in a credit pool is actually borrowed. You find it by dividing the total borrowed by the total supplied. High-level utilization pushes interest rates up. Lower numbers result when there is more supply than demand. Most of these platforms adjust rates automatically based on that number.
Take a pool with $1,000 supplied and $800 borrowed. Its utilization ratio is 80%. With so much of the pool in use, rates rise to attract more suppliers and slow down utilization. Compound employs a simple formula: interest rate = 5% + 15% x the utilization ratio.
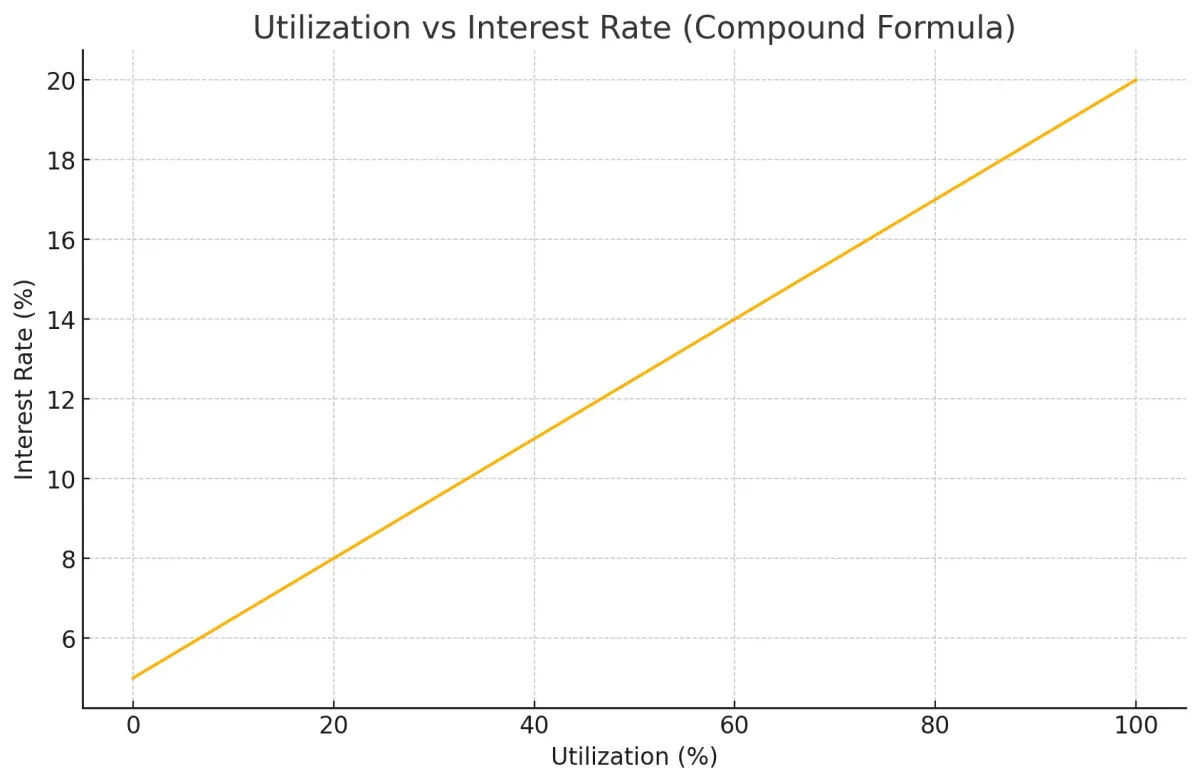
That means figures move from 5% at zero utilization up to 20% at full utilization. Other platforms like dYdX and DDEX apply steeper curves for faster rate changes. This ongoing innovation keeps blockchain lending credit both flexible and balanced.
Liquidation
Liquidation happens when a borrower’s collateral is sold to pay back their loan after its value drops too low. The protocol sets a safety score, often called a health factor, to make sure there is always enough of a guarantee. If the security backing falls below that score, it could be sold so that the loan stays covered. This keeps the system stable and the lenders protected.
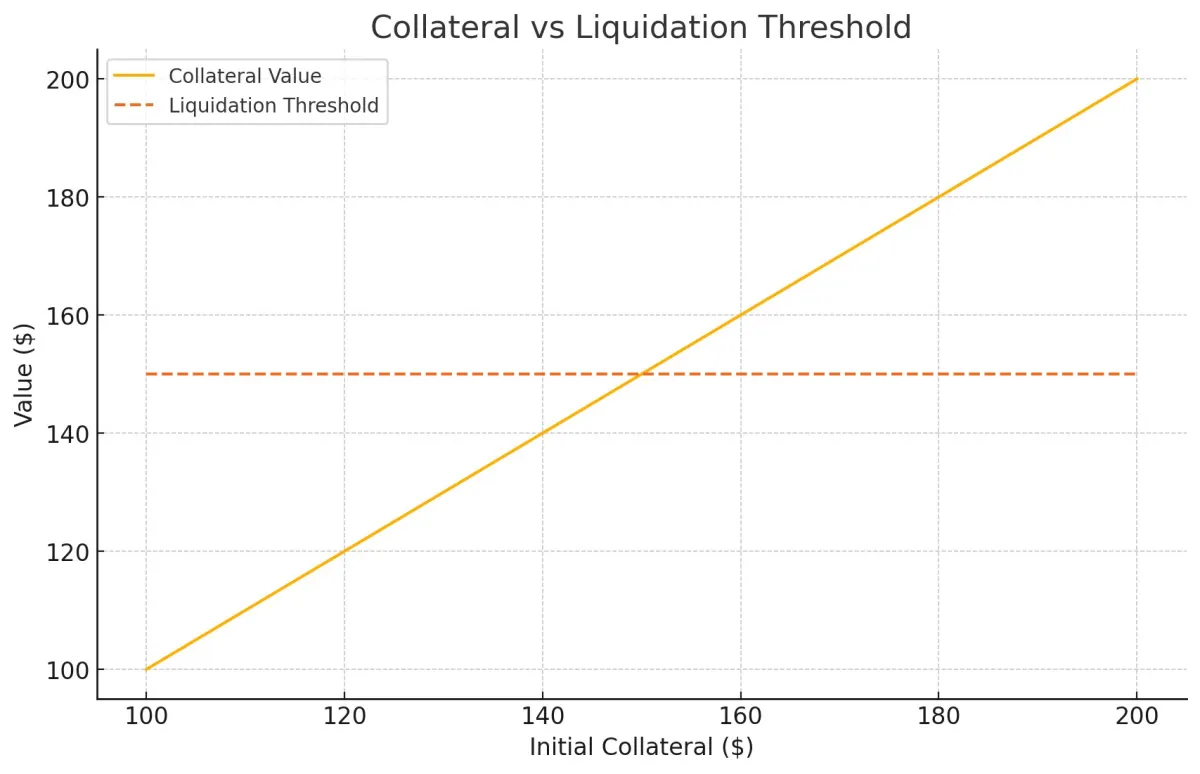
Blockchain lending has no credit checks or courts to step in. Instead, overcollateralization and liquidation handle the risk. When a position becomes undercollateralized, anyone could trigger a sale. They repay part of the loan and receive the collateral at a small discount. In some projects, if the health factor drops below 1, up to 50% of the debt can be paid off this way, and the liquidator earns a fee. This protects lenders but may be painful for borrowers.
Imagine you lock up 10 Ethereum worth $3,000 as collateral and use $2,000 DAI. Your liquidation limit is 80%. If Ethereum’s price falls and your guarantee dips below $2,500, your position could be liquidated. A liquidator steps in, pays part of your debt, and takes some of your Ethereum at a discount. You lose some collateral, but your remaining debt goes down.
Health Factor
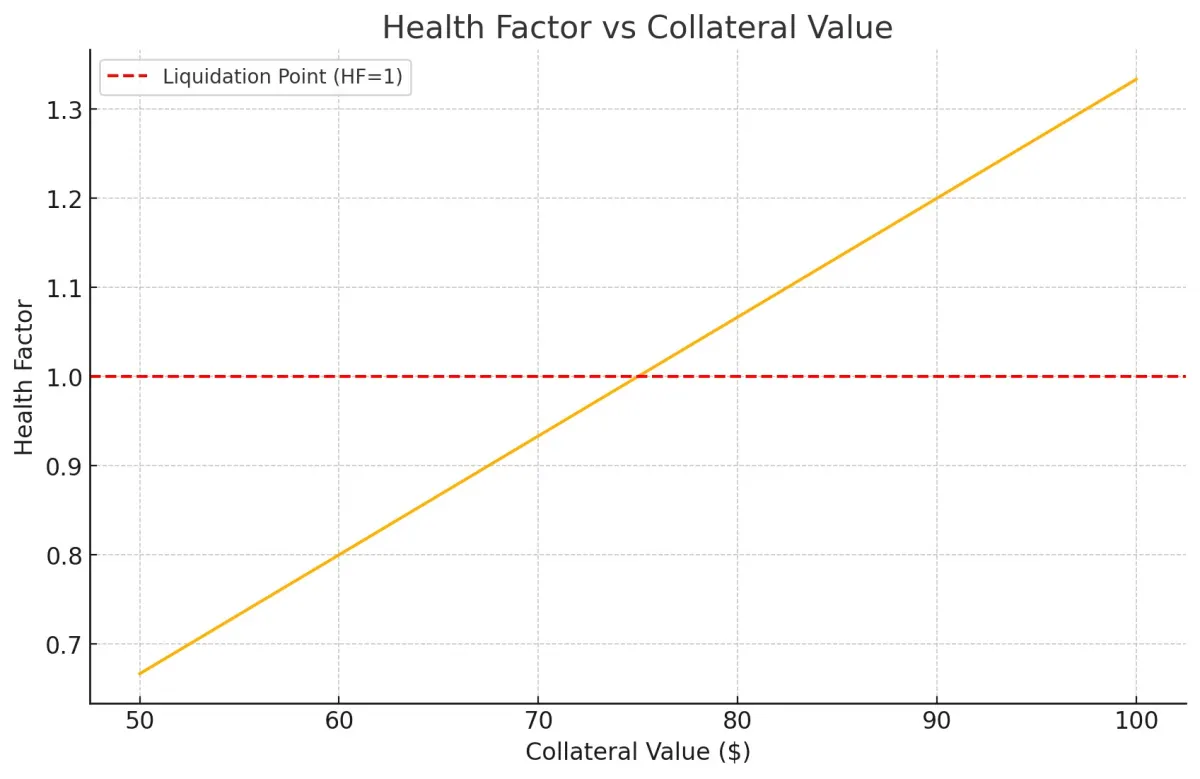
The health factor shows how safe a loan is. It is calculated as: (the sum of each collateral’s value × its liquidation cutoff) ÷ total borrowed
All values are usually in Ethereum.
A health factor above 1 means your loan has enough backing. If it falls below 1, you don’t have enough security, and your position can be liquidated. This number gives you a simple signal so you can add more collateral or pay back some debt.
デジタルドルは高いしきい値(80%前後)を維持することが多い一方、リスクの高いデジタル資産は65%程度にとどまります。この差は、その資産の価格変動の起こりやすさを反映しています。市場が活発なときは、清算者がヘルスファクターの低いポジションを探し出そうと競い合い、価格が動いた瞬間に素早く行動します。
For example, say you lock up $10,000 as a guarantee with an 80% cutoff and borrow $ 6,000. Your health factor is: (10,000 × 0.8) ÷ 6,000 = 1.33
That is above 1 and shows your position is safe. If the security value drops, pushing the health factor under 1, you face liquidation.
Conclusion
ブロックチェーンレンディングは、デジタル資産を貸し借りする新しい方法を切り開きます。用語を理解することで賢い判断ができ、リスクを管理して、より主導権を持てるようになります。最新情報を追い、監査済みのスマートコントラクトを備えた信頼できるプラットフォームを使うことが成功の鍵です。ちなみに、最近注目されている低リスクで大きな利益を狙える手段の一つがクラウドレンディングです。8lendsは、担保に裏付けられた複数のプロジェクトにリスクを均等に分散し、15%の利回りを提供します。
次に読む



ご質問はありますか?
すべての質問プラットフォームはCertiKとCyberscopeの監査を受けており、すべての取引はBase上で公開されています。明確な役割を持つ2社が支えています:CLEARCHAIN CORP(プラットフォームの運営、カナダのFINTRACにMSBとして登録)、Maclear AG(デューデリジェンスと担保)。適切に規制され、透明性と説明責任のある運営です
BuyBack付きの案件なら、60日以上の延滞でパートナーがローンを買い取り、元本の100%を返還します。BuyBackがない場合はMaclear AGが担保の売却を開始し、収益は投資家に比例配分されます。ローンチ以来デフォルトはありません
プラットフォームを運営するのはCLEARCHAIN CORPで、カナダでMoney Services Business(MSB)として登録され、FINTRACのもとで義務的なAML/CFTコンプライアンス要件の対象となっています。決済はUSDで行われます。プラットフォームはCASPではないため、DAC8の要件は適用されません
発展途上地域の中小企業は銀行融資へのアクセスが難しく、EUや米国の企業より高い金利を受け入れています
満期前にセカンダリーマーケットで他の投資家にポジションを売却できます。Fastlendingには固定期間がなく、元本と収益はいつでも引き出せます
最低投資額は100 USDです
企業の不払いリスク、担保価値の変動リスク、セカンダリーマーケットで買い手がいない場合の流動性リスク、スマートコントラクトに関わる技術的リスク
100〜500 USDの投資はKYC不要です。500 USD超は本人確認書類と住所証明による完全な認証が必要です