
What an Independent Collateral Agent Does When a Loan Fails
1 października 20267 min czytania
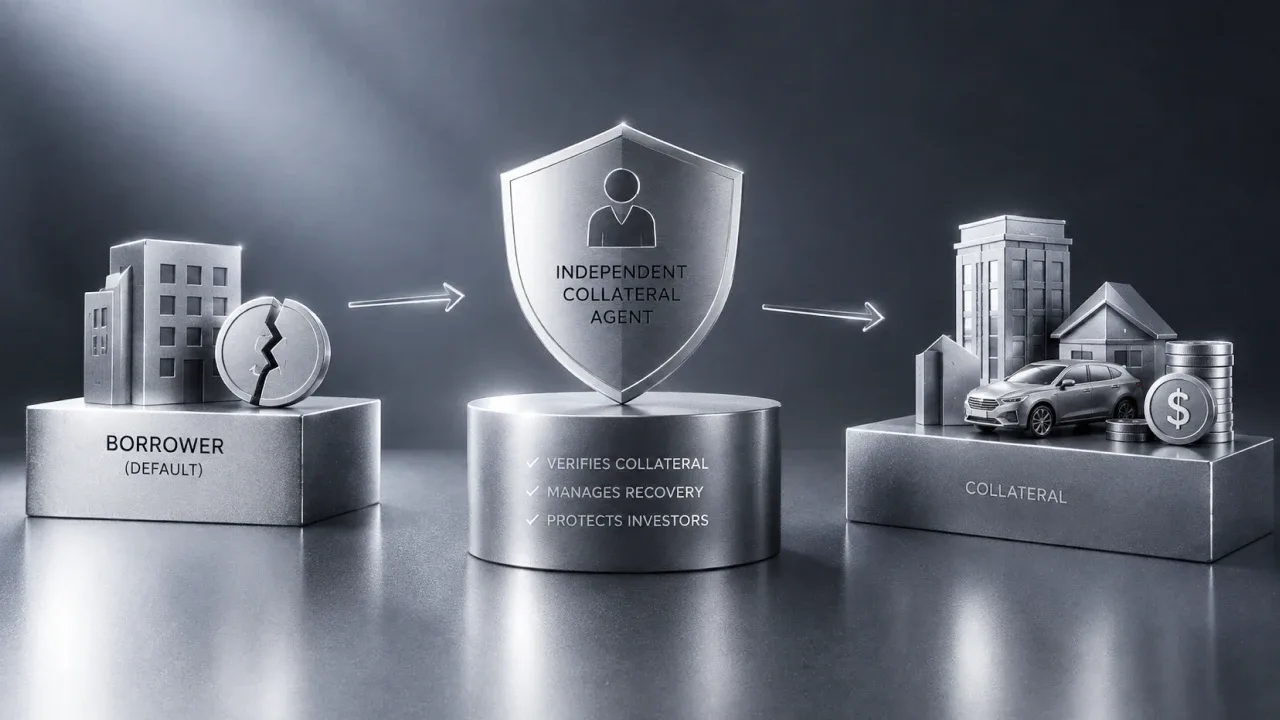
When a borrower stops paying, an investor cannot personally seize collateral in a foreign jurisdiction. That responsibility sits with an independent Collateral Agent, a separate legal entity from the platform operator, which holds the collateral claim and, when necessary, enforces and liquidates the assets before distributing recovered proceeds proportionally among investors.
When a borrower stops paying, an investor cannot personally seize collateral in a foreign jurisdiction. That responsibility sits with an independent Collateral Agent, a separate legal entity from the platform operator, which holds the collateral claim and, when necessary, enforces and liquidates the assets before distributing recovered proceeds proportionally among investors.
What is a collateral agent, and why is it a separate legal entity from the platform?
A secured loan involves at least 5 separate tasks between underwriting and recovery. Keeping those tasks apart matters because the party that approves a loan should not also control every decision once that loan becomes distressed.
| Task | Who performs it | What happens if the same entity did both |
|---|---|---|
| Underwriting the loan | The platform operator | The same party would profit from loan volume and decide whether to lend. |
| Structuring and registering the collateral claim | The independent Collateral Agent | The security would be prepared by the party already interested in the deal closing. |
| Holding custody of collateral documents and title records | The independent Collateral Agent | The party managing the lending process would also control the paperwork needed for enforcement. |
| Deciding whether and when to declare default and enforce | The independent Collateral Agent | The timing decision could favour giving the borrower longer to repay rather than moving toward recovery. |
| Distributing recovered proceeds among investors | The independent Collateral Agent | Allocation would be decided by the same entity already controlling the lending process. |
After a loan stops performing, the key question is who has authority to act on the security and move recovery forward for investors.
What would change if the same entity ran the platform and enforced collateral?
Origination, collateral documentation, enforcement decisions, and distribution would all sit with one organization. That creates a conflict when the same party must choose between allowing more time for repayment and starting enforcement.
Who actually enforces collateral when a borrower stops paying?
On 8lends, 2 separate entities have different responsibilities once a loan is in trouble. The platform operator runs the lending platform; the independent Collateral Agent handles collateral and enforcement on behalf of investors.
8lends is operated by Alpha Systems LLC, a VASP under FSA supervision (Saint Vincent and the Grenadines). Maclear AG (Switzerland), a member of PolyReg SRO, acts as the independent Collateral Agent – it does not operate the platform, is not its parent company, and does not hold investor funds.
If enforcement is required, Maclear AG takes the relevant legal steps in the jurisdictions connected with the borrower and the pledged collateral.
In this context, PolyReg supervision relates primarily to anti-money-laundering obligations.
Who is the collateral agent for loans on 8lends specifically?
Maclear AG is the independent Collateral Agent for loans on 8lends. It is a Swiss company and a member of PolyReg SRO, but remains separate from Alpha Systems LLC. It does not operate the platform, is not the parent company, and does not hold investor funds. Its role is to act for investors in matters involving borrowers, pledged assets, and enforcement.
What is the step-by-step timeline from missed payment to distributed proceeds?
Formal default follows 60 days of continued non-payment; a missed due date does not trigger immediate seizure or sale. Once enforcement begins, liquidation commonly takes around 1-12 months, depending on the borrower’s jurisdiction and the type of collateral involved.
The process develops in six stages:
- Missed payment. The due date passes without repayment.
- Notice and negotiation. The Collateral Agent contacts the borrower, establishes the cause, and tries to negotiate a resolution.
- Formal default declaration. If non-payment continues for 60 days, the loan is formally declared in default.
- Enforcement. The Collateral Agent takes the legal steps required in the borrower’s jurisdiction.
- Liquidation. The collateral is sold or converted into recoverable value. This commonly takes 1-12 months.
- Distribution. Recovered proceeds are allocated proportionally among investors holding a claim.
Timing varies by asset. Real estate may involve registries or court procedures that do not apply to equipment, while inventory raises different issues. The 1-12 month range is an indication, not a promise.
How soon after a missed payment does formal default get declared?
Formal default is declared after 60 days of continued non-payment. Before then, the Collateral Agent contacts the borrower to understand the missed payment and see whether it can be resolved. If the arrears continue through the 60-day period, enforcement can proceed under the relevant legal framework.
What does an investor see and can ask for at each stage?
There are 4 practical information points for an investor: delinquency, formal default, enforcement, and distribution. The investor can follow the case and ask for information, but does not personally direct the legal process.
When a payment becomes overdue, the loan status changes on the platform. An investor can ask what steps the Collateral Agent has taken.
Once formal default is declared, a public notice is issued. Investors can then ask which jurisdiction applies to enforcement.
During enforcement and liquidation, periodic updates show how the case is progressing. Investors can ask about timing and whether the current recovery outlook may cover outstanding principal, although neither can be fixed in advance.
After distribution, the investor can see the amount allocated to their participation relative to the amount invested.
Can an investor speed up or influence the enforcement process?
No. An individual investor does not decide when collateral is seized, which legal route is used, or when an asset is sold. Those decisions sit with the Collateral Agent under the transaction documents and applicable law. The investor can follow the case, request information, and receive a proportional share of any recovered proceeds.
Does separating roles guarantee full recovery or a faster process?
The 60-day default threshold and the typical 1-12 month liquidation range describe parts of the process, not its outcome. Neither figure tells an investor how much will be recovered or when a particular enforcement case will finish.
Separating the platform operator from the collateral agent reduces conflicts of interest, but it does not guarantee full recovery, a fixed timeline, or protection from principal loss.
A separate Collateral Agent keeps enforcement decisions apart from platform operation. It cannot, however, remove the risks that arise once recovery begins.
Court procedures may take longer than expected. Collateral can sell for less than its earlier valuation, while legal or sale costs may reduce the amount left for investors. The structure clarifies who acts on investors’ behalf; it does not determine the final recovery.
Investing involves risk, including possible loss of principal. Returns are not guaranteed.
Najczęściej zadawane pytania
A collateral agent is an independent party that manages the legal claim over pledged collateral and can initiate enforcement when a borrower fails to meet its obligations. The role exists because individual investors are usually not in a practical position to pursue collateral themselves in another jurisdiction.
Maclear AG is the independent Collateral Agent for loans on 8lends. It is a Swiss company and a member of PolyReg SRO. It does not operate the platform, is not its parent company, and does not hold investor funds. It works with borrowers and collateral on behalf of investors when recovery action is required.
The first missed payment is usually followed by contact with the borrower, not by immediate enforcement. The Collateral Agent will first try to establish why the payment was missed and whether the situation can still be resolved. If the loan remains unpaid for 60 days, it is formally treated as being in default. Only then does the process move on to enforcement and, if needed, the sale of the collateral.
There is no fixed timetable. Liquidation often takes somewhere between 1 and 12 months, but the actual timing depends on where the borrower is based, what type of collateral is involved, and which legal steps are required. A property, a piece of equipment, and inventory may each follow a different recovery process.
No. Separating the Collateral Agent from the platform operator reduces the conflict of interest around enforcement decisions, but it does not determine the recovery outcome. How much is returned to investors depends on athe value of the collateralhttps://www.8lends.io/blog/collateral-valuation-and-ltv, and the cost of the enforcement and the legal process in the relevant jurisdiction. Sometimes the proceeds may not be enough to pay the whole principal.
Przeczytaj dalej


Masz pytania?
Wszystkie pytaniaPlatformę zaudytowały CertiK i Cyberscope, a wszystkie transakcje są publicznie widoczne w blockchainie Base. Za platformą stoją dwie firmy o jasno rozdzielonych obowiązkach: CLEARCHAIN CORP prowadzi platformę i jest zarejestrowana jako Money Services Business w FINTRAC (Kanada), a Maclear AG wykonuje due diligence i nadzoruje zabezpieczenie. Platforma jest więc dobrze uregulowana, przejrzysta i rozliczalna
Jeśli projekt ma BuyBack, partner odkupuje pożyczkę i zwraca 100% kapitału po 60 dniach opóźnienia lub więcej. Bez BuyBack Maclear AG rozpoczyna sprzedaż zabezpieczenia, a wpływy są dzielone proporcjonalnie między inwestorów. Od startu nie było ani jednej niewypłacalności
Platformę prowadzi CLEARCHAIN CORP, zarejestrowana w Kanadzie jako Money Services Business (MSB) i podlegająca obowiązkowym wymogom AML/CFT w ramach FINTRAC. Rozliczenia odbywają się w USD. Platforma nie jest CASP, więc wymogi DAC8 jej nie dotyczą
Małe i średnie firmy w regionach rozwijających się nie mają łatwego dostępu do finansowania bankowego i są gotowe płacić wyższe stawki niż firmy w UE czy USA
Możesz sprzedać swoją pozycję innemu inwestorowi na Secondary Market przed końcem okresu pożyczki. W Fastlending nie ma stałego terminu: kapitał i naliczony dochód można wypłacić w dowolnym momencie
Minimalna inwestycja to 100 USD
Ryzyko braku spłaty przez firmę, ryzyko zmiany wartości zabezpieczenia, ryzyko ograniczonej płynności, gdy na Secondary Market nie ma kupującego, oraz ryzyko techniczne związane ze smart kontraktem
Inwestycje od 100 do 500 USD są dostępne bez KYC. Powyżej 500 USD wymagana jest pełna weryfikacja: dokument tożsamości i potwierdzenie adresu