
플랫폼 리스크 이해하기: P2P 회사가 파산한다면?
2025년 9월 23일5 분 소요
더 높은 수익, 더 나은 분산 투자, 그리고 차입자에 대한 직접적인 노출을 원하는 개인들이 P2P 대출로 몰려들고 있습니다. 하지만 투자자들이 차입자 프로필과 금리를 자주 면밀히 검토하는 반면, 흔히 간과되는 더 심각한 위험이 있습니다. 바로 근본적인 위험인 플랫폼 리스크입니다. 이는 이용 중인 P2P 회사가 파산하거나, 출금을 동결하거나, 부도가 날 위험을 말합니다. 그렇게 되면 내 돈이 묶여 버릴 수 있습니다. 운이 좋아 일시적으로는 버틸 수 있을지 몰라도, 그것이 영구적인 손실 위험을 없애 주지는 않습니다. P2P 대출 시장이 성숙해지고 더 많은 고객을 끌어들이면서, 플랫폼이 파산할 경우 어떤 일이 벌어지는지 이해하는 것은 이제 단순히 도움이 되는 정도가 아니라 자본을 지키기 위해 필수적인 일이 되었습니다. 이 글에서는 플랫폼 리스크란 무엇인지, 플랫폼이 문을 닫을 경우 내 자금은 어떻게 되는지, 그리고 이러한 혼란으로부터 스스로를 어떻게 보호할 수 있는지 살펴보겠습니다.
Why Platform Risk is Often Overlooked
Whenever individuals think about risk in peer-to-peer lending, they typically consider the borrower. What happens to the borrowers when they default on the loan? Do they have a good credit history? Those are good concerns. However, they are just part of the story. The platform is probably the biggest unaccounted-for risk in P2P lending.
Investors assume that a platform is running if it is safe. But sometimes that isn't so. A platform may be poorly managed, underfunded, or poorly overseen. And even borrowers making repayments might not save investors from losing access to their money if that platform fails.
Many retail investors skip this altogether. However, understanding platform risk is as important as evaluating a loan on a case-by-case basis.
Why Platform Risk Matters
P2P platforms facilitate the entire loan lifecycle by matching investors with borrowers. They:
- Vet and list borrowers
- Handle payments & repayment schedules
- Manage communication and collection
- Offer investor dashboards and updates
When this middleman collapses, things get messy. If a borrower continues to pay, who collects that payment anyway? Who makes sure it reaches you? Who handles disputes?
Without strong safety measures, your investment may be stranded, or even worse, completely lost.
What Happens if a P2P Platform Fails?
A platform failure does not necessarily mean your money is gone. However, recovering is complicated by many factors. These include:
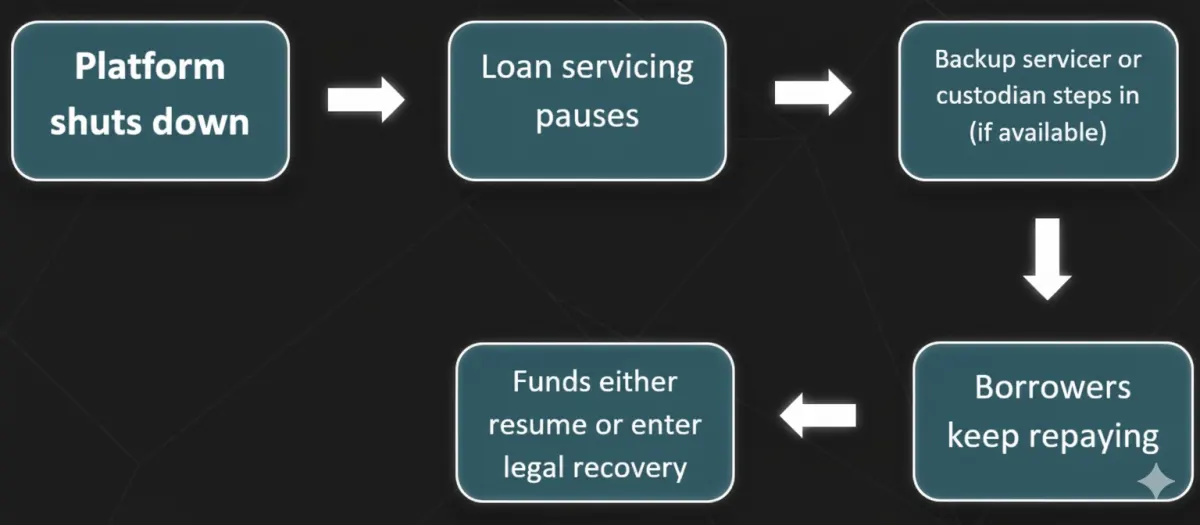
Disrupted Loan Servicing
Backup servicers keep track of repayments and borrower communications if the platform fails. If the platform goes down and no backup servicer is available, payments from borrowers could stop. Communications would break down, and you may not receive your expected income.
Custodian Account / SPV
Reputable platforms often protect investor money through Custodian accounts / Special Purpose Vehicles (SPVs). This keeps investor funds separate and ensures they are less likely to disappear with the platform.
Activation of Backup Servicer
Some platforms have agreements with third-party servicers that can take over loan management when required. This may keep repayments up and limit losses.
Bankruptcy and Legal Process
Investors become unsecured creditors if the platform goes bankrupt. What this means is that you might get only a fraction of your money back. And even that may take months or years.
Real-World Examples of Platform Failure
Lendy (UK, 2019)
Lendy was once one of the top peer-to-peer lending platforms in the UK and yet things went wrong. The firm entered administration in 2019 after there was an increase in default rates and increased concern over poor transparency. The failure of the loans was worth more than 160 million pounds and years later there are still investors waiting to be paid back in full.
Grupeer (Latvia, 2020)
Grupeer, a P2P platform operating in Latvia, suffered platform failure; its sudden freezing of the withdrawals caught its users completely unexpectedly. It would be later realized that all the listed loans on the platform had some fake loans. Most investors sustained huge losses, especially with the lack of a straightforward plan of recovery and legal options. In most of the instances, the amount recovered was less than 20% of the original amount invested.
These examples demonstrate that a platform's power and regulation create a significant impact on whether investors retrieve funds or not.
8lends is a Swiss-based crowdlending company built with platform security and long-term investor protection at its core. With regulated operations, robust credit vetting, and transparent loan structuring through SPVs, 8lends offers not just strong returns – but peace of mind that your capital isn’t left exposed to platform chaos.
How To Know if a Platform is At Risk
Several signs can suggest trouble is coming.
| Red Flag | Why It Matters |
|---|---|
| Delayed interest payouts | May indicate liquidity problems |
| No recent audits published | Lack of transparency |
| Management turnover | Can signal internal instability |
| Poor communication | Often precedes operational shutdown |
| Withdrawal restrictions | A serious warning sign |
Red flags also include sudden shifts in strategy. For example, switching from low-risk consumer loans to high-risk digital assets without sufficient transparency. If you notice one or more of these, it's wise to consider exiting early.
Factors That Determine Recovery Success
Recovery depends on several technical and legal factors:
| Factor | Impact on Recovery |
|---|---|
| Custodian Account | Keeps investor funds separate from platform |
| SPV Loan Structure | Loans are easier to transfer and manage |
| Regulatory Oversight | Regulated platforms are more likely to have protocols |
| Jurisdiction | Strong legal frameworks help enforce recovery |
Visual Guide: What Happens When a Platform Collapses
Zopa’s Pandemic Response
Zopa, a regulated UK P2P platform established in 2005, ended the early 2020 market turmoil quite differently. Zopa implemented some protections and still operated despite investor withdrawals.
They froze new loan listings and capped withdrawals temporarily to maintain liquidity.
Weekly updates on portfolio and loan book performance were sent to investors. Zopa used its well-capitalised reserve and backup mechanisms to keep borrower repayments flowing.
Consequently, the platform did not collapse, and most investors continued to receive repayments. Zopa was transparent and prepared. And this proved to be pivotal in weathering a stressful period. This crisis-tested resilience bolstered Zopa's reputation and later helped it to gain traction as it transitioned to a fully licensed bank.
Risk Types
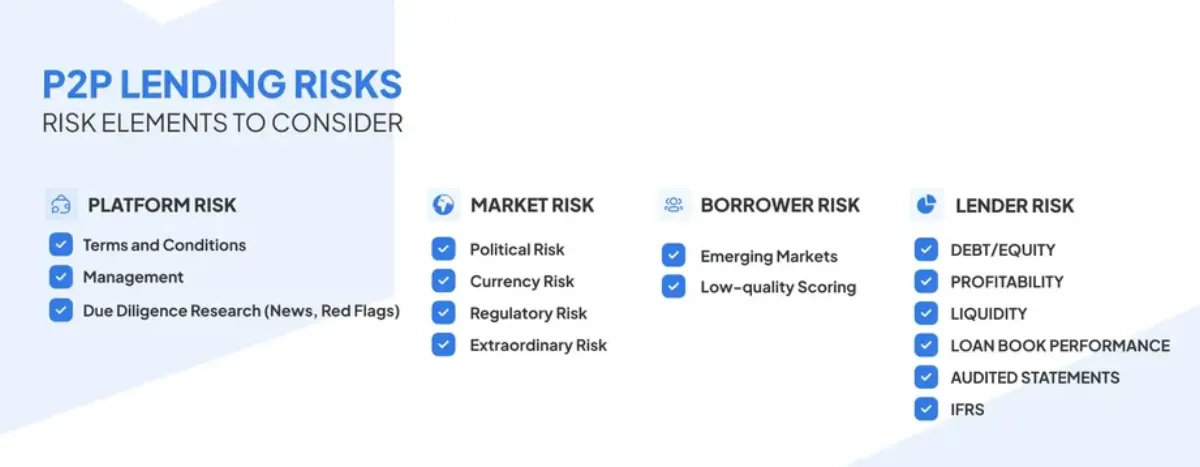
It’s important not to confuse platform failure with borrower default or other types.
| Type of Risk | Description | Can You Control It |
|---|---|---|
| Platform Risk | Platform collapses or goes bankrupt | Limited |
| Borrower Risk | Borrower misses payment | Medium |
| Currency Risk | FX losses on cross-border loans | Yes (Hedging) |
| Economy Risk | Recession causes widespread defaults | No |
Even if a borrower is paying on time, you won’t get your money unless there’s someone to process and pass on that payment.
Steps to Protect Yourself
Here’s what you can do:
- Confirm Custody Arrangements Verify that the platform uses separate accounts or custodians. Avoid platforms that jumble investor money with operating cash.
- Understand the Legal Setup Do loans under your name exist as SPVs or security? If so, they can be transferred more easily if there’s a collapse.
- Know Where It’s Regulated Licensed platforms are generally safer, for example, the UK's FCA. Other jurisdictions are more risky.
- Diversify Across Platforms Don’t put all your money on one platform. Consider 2-3 reliable ones, as they will reduce your risk tremendously.
- Monitor Platform Health Watch for delayed withdrawals, broken dashboards, or long silence. They are all early warnings of trouble.
- Keep Your Own Records Download contracts, payment schedules & communications. They might be crucial in legal proceedings.
Summary Table: Platform Risk at a Glance
| Risk Area | What it Means | What Can You Do? |
|---|---|---|
| No Custodian | Funds may disappear with the platform | Confirm use of third-party custodian |
| No SPV | Ownership of loans unclear | Ask how loans are legally structured |
| Weak Regulation | No protections during failure | Favour regulated platform |
| Single Platform Use | All eggs in one basket | Diversify your portfolio |
| Poor Transparency | Trouble can sneak up on you | Monitor platform communications and audits |
Final Thoughts
Platform risk isn't flashy, but it's real. It can be easy to get lost in interest rates and borrower profiles and not consider the platform itself as the glue holding everything together. The good news? You can minimize this risk by doing a little homework upfront: Pick regulated platforms, custodians & SPVs, lend across different asset classes, and be on the lookout.
Looking for a platform that takes your capital seriously? 8lends is redefining peer-to-peer lending with one of the most advanced risk-management frameworks in the industry. Whether you care about borrower quality, loan transparency, or long-term platform viability – 8lends delivers on every front.
다음 읽을거리
궁금한 점이 있으신가요?
모든 질문플랫폼은 CertiK와 Cyberscope의 감사를 받았으며 모든 거래는 Base에서 공개적으로 확인할 수 있습니다. 책임이 명확한 두 회사가 뒷받침합니다: CLEARCHAIN CORP(플랫폼 운영, 캐나다 FINTRAC에 MSB로 등록)와 Maclear AG(실사와 담보). 플랫폼은 잘 규제되고 투명하며 책임 있게 운영됩니다
BuyBack이 있는 프로젝트라면 60일 이상 연체 시 파트너가 대출을 매입해 원금의 100%를 돌려줍니다. BuyBack이 없으면 Maclear AG가 담보 매각을 시작하고 대금은 투자자에게 비례 배분됩니다. 출시 이후 부도는 없었습니다
플랫폼은 캐나다에서 Money Services Business(MSB)로 등록되어 FINTRAC의 의무 AML/CFT 컴플라이언스 요건을 적용받는 CLEARCHAIN CORP가 운영합니다. 정산은 USD로 이루어집니다. 플랫폼은 CASP가 아니므로 DAC8 요건이 적용되지 않습니다
개발도상 지역의 중소기업은 은행 금융에 쉽게 접근하지 못해 EU나 미국 기업보다 높은 금리를 감수합니다
만기 전에 세컨더리 마켓에서 다른 투자자에게 포지션을 판매할 수 있습니다. Fastlending은 고정 기간이 없어 원금과 수익을 언제든 인출할 수 있습니다
최소 투자액은 100 USD입니다
기업의 미상환 리스크, 담보 가치 변동 리스크, 세컨더리 마켓에 매수자가 없을 때의 유동성 제한 리스크, 스마트 컨트랙트 관련 기술 리스크
100–500 USD 투자는 KYC 없이 가능합니다. 500 USD 초과 시 신분증과 주소 증명을 통한 전체 인증이 필요합니다