
プラットフォームリスクを理解する:P2P企業が破綻したらどうなるか
2025年9月23日5 分で読めます
より高いリターン、より高い分散効果、そして借り手への直接的なエクスポージャーを求める人々が、P2Pレンディングに殺到しています。しかし、投資家は借り手のプロフィールや金利にはよく目を光らせる一方で、より厄介でありながら見過ごされがちなリスクがあります。それがプラットフォームリスク、つまり根本的なリスクです。これは、利用しているP2P企業が破綻したり、出金を凍結したり、倒産したりするリスクを指します。そうなれば、あなたのお金は身動きが取れなくなる可能性があります。運が良ければ一時的には持ちこたえられるかもしれませんが、それによって恒久的な損失のリスクがなくなるわけではありません。P2Pレンディング市場が成熟し、より多くの顧客を惹きつけるようになるにつれ、プラットフォームが破綻した場合に何が起こるかを理解しておくことは、単に役立つだけでなく、あなたの資本を守るうえで不可欠なものになっています。この記事では、プラットフォームリスクとは何か、プラットフォームが事業を停止した場合に資金がどうなるのか、そしてそうした混乱から自分自身を守る方法について解説します。
Why Platform Risk is Often Overlooked
Whenever individuals think about risk in peer-to-peer lending, they typically consider the borrower. What happens to the borrowers when they default on the loan? Do they have a good credit history? Those are good concerns. However, they are just part of the story. The platform is probably the biggest unaccounted-for risk in P2P lending.
Investors assume that a platform is running if it is safe. But sometimes that isn't so. A platform may be poorly managed, underfunded, or poorly overseen. And even borrowers making repayments might not save investors from losing access to their money if that platform fails.
Many retail investors skip this altogether. However, understanding platform risk is as important as evaluating a loan on a case-by-case basis.
Why Platform Risk Matters
P2P platforms facilitate the entire loan lifecycle by matching investors with borrowers. They:
- Vet and list borrowers
- Handle payments & repayment schedules
- Manage communication and collection
- Offer investor dashboards and updates
When this middleman collapses, things get messy. If a borrower continues to pay, who collects that payment anyway? Who makes sure it reaches you? Who handles disputes?
Without strong safety measures, your investment may be stranded, or even worse, completely lost.
What Happens if a P2P Platform Fails?
A platform failure does not necessarily mean your money is gone. However, recovering is complicated by many factors. These include:
Disrupted Loan Servicing
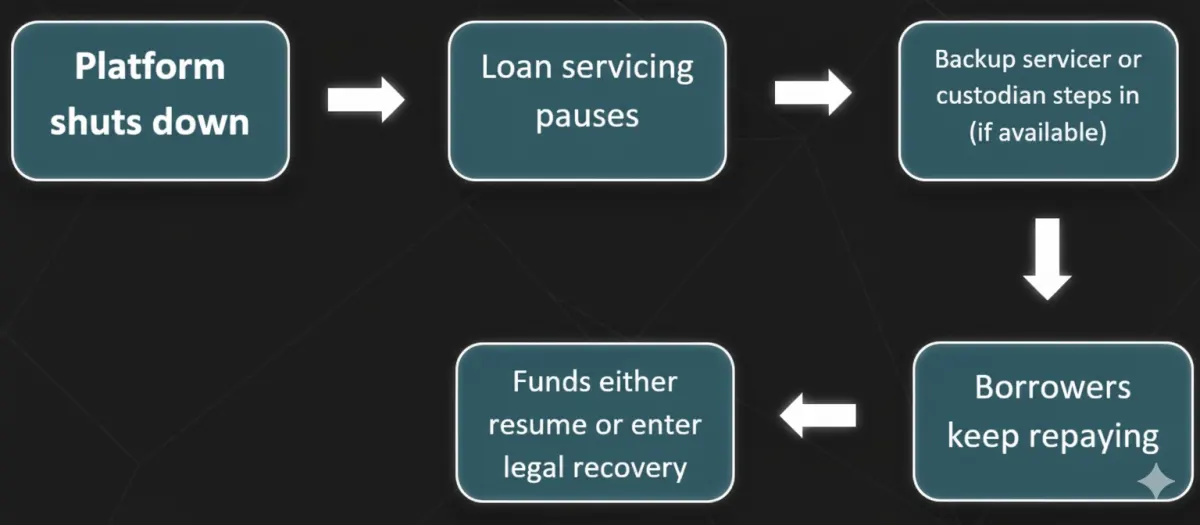
Backup servicers keep track of repayments and borrower communications if the platform fails. If the platform goes down and no backup servicer is available, payments from borrowers could stop. Communications would break down, and you may not receive your expected income.
Custodian Account / SPV
Reputable platforms often protect investor money through Custodian accounts / Special Purpose Vehicles (SPVs). This keeps investor funds separate and ensures they are less likely to disappear with the platform.
Activation of Backup Servicer
Some platforms have agreements with third-party servicers that can take over loan management when required. This may keep repayments up and limit losses.
Bankruptcy and Legal Process
Investors become unsecured creditors if the platform goes bankrupt. What this means is that you might get only a fraction of your money back. And even that may take months or years.
Real-World Examples of Platform Failure
Lendy (UK, 2019)
Lendy was once one of the top peer-to-peer lending platforms in the UK and yet things went wrong. The firm entered administration in 2019 after there was an increase in default rates and increased concern over poor transparency. The failure of the loans was worth more than 160 million pounds and years later there are still investors waiting to be paid back in full.
Grupeer (Latvia, 2020)
Grupeer, a P2P platform operating in Latvia, suffered platform failure; its sudden freezing of the withdrawals caught its users completely unexpectedly. It would be later realized that all the listed loans on the platform had some fake loans. Most investors sustained huge losses, especially with the lack of a straightforward plan of recovery and legal options. In most of the instances, the amount recovered was less than 20% of the original amount invested.
These examples demonstrate that a platform's power and regulation create a significant impact on whether investors retrieve funds or not.
8lends is a Swiss-based crowdlending company built with platform security and long-term investor protection at its core. With regulated operations, robust credit vetting, and transparent loan structuring through SPVs, 8lends offers not just strong returns – but peace of mind that your capital isn’t left exposed to platform chaos.
How To Know if a Platform is At Risk
Several signs can suggest trouble is coming.
| Red Flag | Why It Matters |
|---|---|
| Delayed interest payouts | May indicate liquidity problems |
| No recent audits published | Lack of transparency |
| Management turnover | Can signal internal instability |
| Poor communication | Often precedes operational shutdown |
| Withdrawal restrictions | A serious warning sign |
Red flags also include sudden shifts in strategy. For example, switching from low-risk consumer loans to high-risk digital assets without sufficient transparency. If you notice one or more of these, it's wise to consider exiting early.
Factors That Determine Recovery Success
Recovery depends on several technical and legal factors:
| Factor | Impact on Recovery |
|---|---|
| Custodian Account | Keeps investor funds separate from platform |
| SPV Loan Structure | Loans are easier to transfer and manage |
| Regulatory Oversight | Regulated platforms are more likely to have protocols |
| Jurisdiction | Strong legal frameworks help enforce recovery |
Visual Guide: What Happens When a Platform Collapses
Zopa’s Pandemic Response
Zopa, a regulated UK P2P platform established in 2005, ended the early 2020 market turmoil quite differently. Zopa implemented some protections and still operated despite investor withdrawals.
They froze new loan listings and capped withdrawals temporarily to maintain liquidity.
Weekly updates on portfolio and loan book performance were sent to investors. Zopa used its well-capitalised reserve and backup mechanisms to keep borrower repayments flowing.
Consequently, the platform did not collapse, and most investors continued to receive repayments. Zopa was transparent and prepared. And this proved to be pivotal in weathering a stressful period. This crisis-tested resilience bolstered Zopa's reputation and later helped it to gain traction as it transitioned to a fully licensed bank.
Risk Types
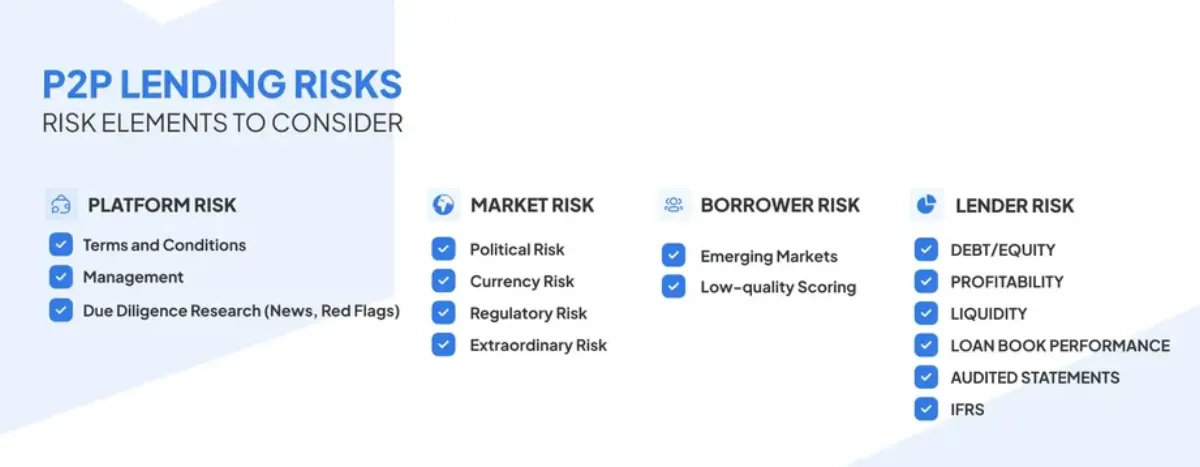
It’s important not to confuse platform failure with borrower default or other types.
| Type of Risk | Description | Can You Control It |
|---|---|---|
| Platform Risk | Platform collapses or goes bankrupt | Limited |
| Borrower Risk | Borrower misses payment | Medium |
| Currency Risk | FX losses on cross-border loans | Yes (Hedging) |
| Economy Risk | Recession causes widespread defaults | No |
Even if a borrower is paying on time, you won’t get your money unless there’s someone to process and pass on that payment.
Steps to Protect Yourself
Here’s what you can do:
- Confirm Custody Arrangements Verify that the platform uses separate accounts or custodians. Avoid platforms that jumble investor money with operating cash.
- Understand the Legal Setup Do loans under your name exist as SPVs or security? If so, they can be transferred more easily if there’s a collapse.
- Know Where It’s Regulated Licensed platforms are generally safer, for example, the UK's FCA. Other jurisdictions are more risky.
- Diversify Across Platforms Don’t put all your money on one platform. Consider 2-3 reliable ones, as they will reduce your risk tremendously.
- Monitor Platform Health Watch for delayed withdrawals, broken dashboards, or long silence. They are all early warnings of trouble.
- Keep Your Own Records Download contracts, payment schedules & communications. They might be crucial in legal proceedings.
Summary Table: Platform Risk at a Glance
| Risk Area | What it Means | What Can You Do? |
|---|---|---|
| No Custodian | Funds may disappear with the platform | Confirm use of third-party custodian |
| No SPV | Ownership of loans unclear | Ask how loans are legally structured |
| Weak Regulation | No protections during failure | Favour regulated platform |
| Single Platform Use | All eggs in one basket | Diversify your portfolio |
| Poor Transparency | Trouble can sneak up on you | Monitor platform communications and audits |
Final Thoughts
Platform risk isn't flashy, but it's real. It can be easy to get lost in interest rates and borrower profiles and not consider the platform itself as the glue holding everything together. The good news? You can minimize this risk by doing a little homework upfront: Pick regulated platforms, custodians & SPVs, lend across different asset classes, and be on the lookout.
Looking for a platform that takes your capital seriously? 8lends is redefining peer-to-peer lending with one of the most advanced risk-management frameworks in the industry. Whether you care about borrower quality, loan transparency, or long-term platform viability – 8lends delivers on every front.
次に読む
ご質問はありますか?
すべての質問プラットフォームはCertiKとCyberscopeの監査を受けており、すべての取引はBase上で公開されています。明確な役割を持つ2社が支えています:CLEARCHAIN CORP(プラットフォームの運営、カナダのFINTRACにMSBとして登録)、Maclear AG(デューデリジェンスと担保)。適切に規制され、透明性と説明責任のある運営です
BuyBack付きの案件なら、60日以上の延滞でパートナーがローンを買い取り、元本の100%を返還します。BuyBackがない場合はMaclear AGが担保の売却を開始し、収益は投資家に比例配分されます。ローンチ以来デフォルトはありません
プラットフォームを運営するのはCLEARCHAIN CORPで、カナダでMoney Services Business(MSB)として登録され、FINTRACのもとで義務的なAML/CFTコンプライアンス要件の対象となっています。決済はUSDで行われます。プラットフォームはCASPではないため、DAC8の要件は適用されません
発展途上地域の中小企業は銀行融資へのアクセスが難しく、EUや米国の企業より高い金利を受け入れています
満期前にセカンダリーマーケットで他の投資家にポジションを売却できます。Fastlendingには固定期間がなく、元本と収益はいつでも引き出せます
最低投資額は100 USDです
企業の不払いリスク、担保価値の変動リスク、セカンダリーマーケットで買い手がいない場合の流動性リスク、スマートコントラクトに関わる技術的リスク
100〜500 USDの投資はKYC不要です。500 USD超は本人確認書類と住所証明による完全な認証が必要です